


EN
Euronet Worldwide (EEFT) Stock Stumbles After Q3 Results Expose Margin Strain
Euronet Worldwide just took a hit. The stock dropped about 7.7% today to roughly US$59 after its Q3 2026 report, extending a slide that has already pulled the share price down about 29% over the past three months. On the surface, a miss against expectations and softer adjusted earnings per share of US$3.55 look like the whole story. The more important angle sits in the margin pressure inside cross border payments, where operating profit fell sharply, and that is what really matters for anyone thinking beyond today’s screen.
Like the cross border margin story in Euronet Worldwide but uneasy about pressure on earnings quality and volatility in a single ticker? You can benchmark this against a broader group of resilient balance sheet plays in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
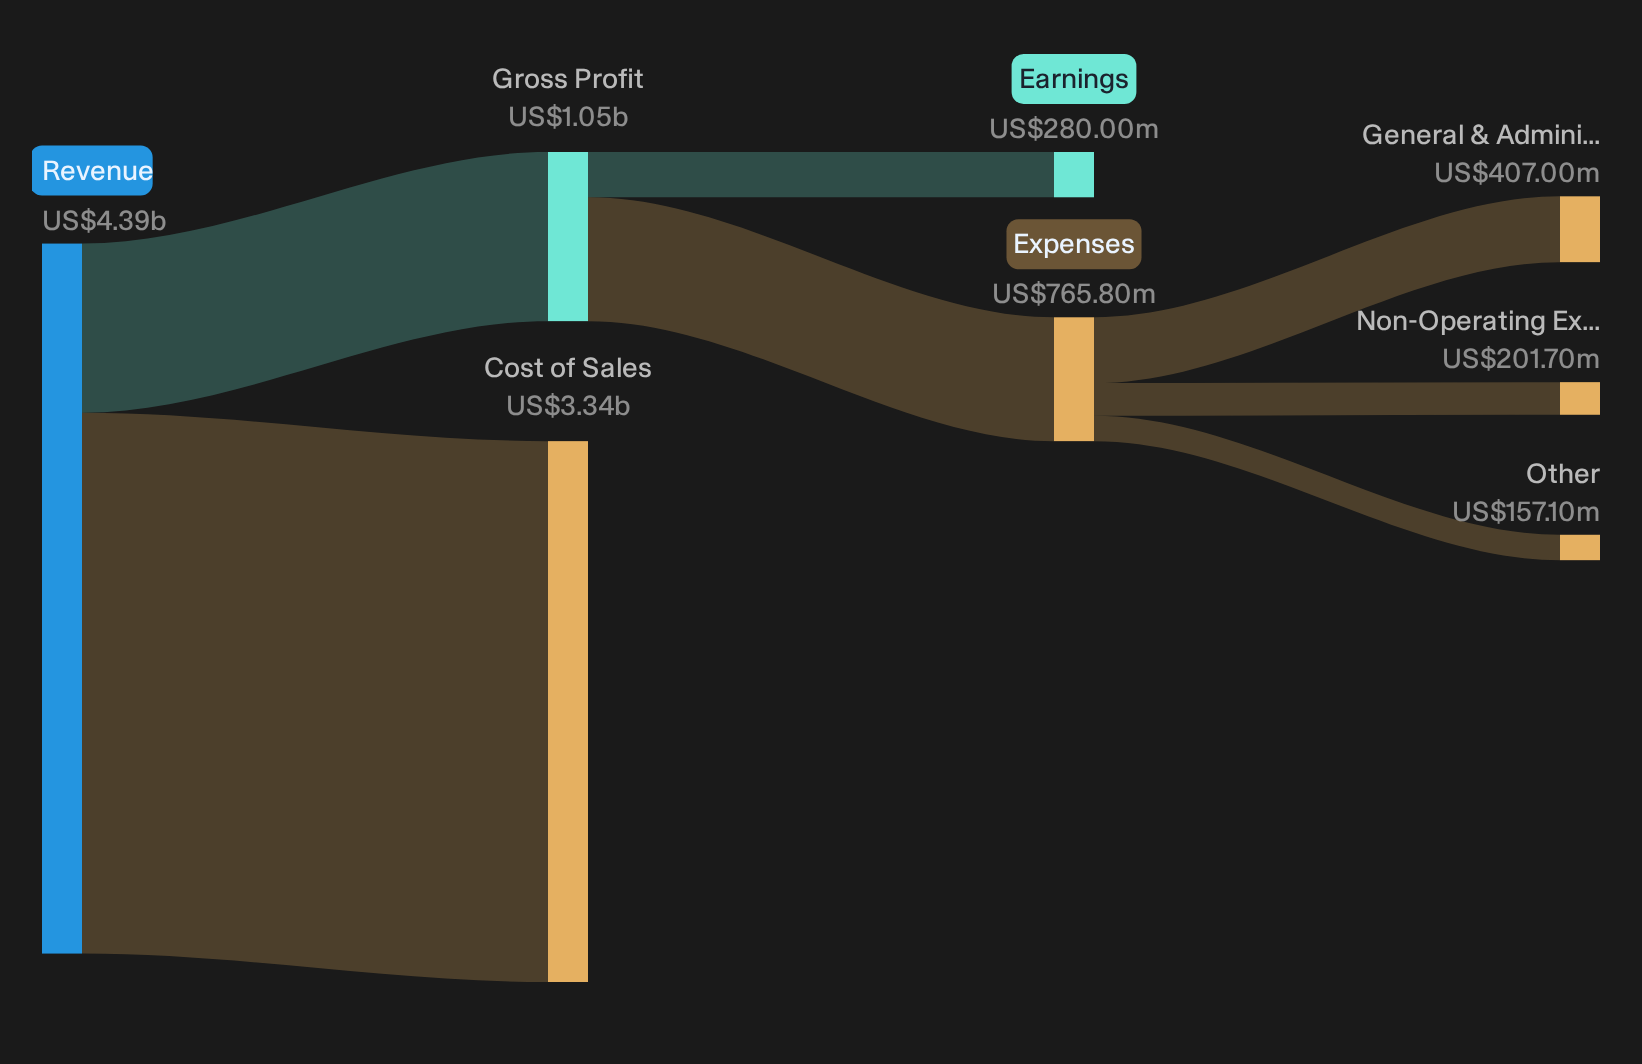
- Revenue (Q3 2026 vs. Q3 2025): US$1,161.1 million vs. US$1,145.7 million (up about 1%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$113.6 million vs. US$122.0 million (down about 7%)
- Basic EPS (Earnings Per Share, Q3 2026 vs. Q3 2025): US$2.48 vs. US$3.02 (fell about 18%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 6.6% vs. 8.0% (compressed by about 1.4 percentage points)
Digital accelerator revenue jumped over 30% even as EPS slipped. Ask Charlie what’s really driving Euronet’s digital accelerator surge.
Euronet Bull Case Hinges On Digital Scale
The upbeat story on Euronet Worldwide assumes a growing share of high value software and online volumes drives better economics across the network.
"The main thing that has to go right is that digital products such as Ria Digital, XE, Dandelion and REN or CoreCard based services keep scaling on Euronet Worldwide's global network while banks and merchants continue to adopt its outsourced infrastructure."
Here, the company is hitting a key milestone. Digital accelerator revenue grew about 30% in Q3 and digital transactions in cross border climbed 34%. These services now account for roughly 26% of payment channel revenue, up from around 21% in 2025. That confirms usage is compounding on the existing rails.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Evaluating Euronet’s Macro‑Execution Risk After Q3 Miss
The bear case argues that macro shocks and policy changes could blunt Euronet Worldwide’s execution gains just as new platforms ramp.
"Persistent global economic weakness and elevated inflation could further squeeze consumer discretionary spending on travel, gaming and digital content, slowing transaction growth in EFT and epay and limiting revenue expansion and operating margin improvement over the long term."
Q3 results give that worry teeth. Cross border revenue declined about 4% and operating income fell 35%, while adjusted EPS slid 2% and missed expectations. Management cut full year guidance and highlighted U.S. immigration policy and FX as primary drags. epay still grew, yet macro and policy pressure clearly outweighed execution wins in this quarter.
Hunt For Mispriced Execution Stories
Euronet Worldwide shows how quickly sentiment can adjust when a key segment faces a setback. The real opportunity is finding companies that could be undervalued before sentiment and fundamentals reconnect.
- Company 1 - 19% below our estimate - uses a fast growing overseas teahouse network to test franchise and company store scalability.
- Company 2 - 32% below our estimate - tightens an industrial footprint and product mix so recurring aftermarket work supports margins on mission critical flow equipment.
- Company 3 - 34% below our estimate - supplies AI oriented cloud infrastructure adopted when single platform capacity and resilience face constraints.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com