


EN
Coca-Cola FEMSA (NYSE:KOF) Stock Slips As Q3 Earnings Meet Mexico Margin Pressure
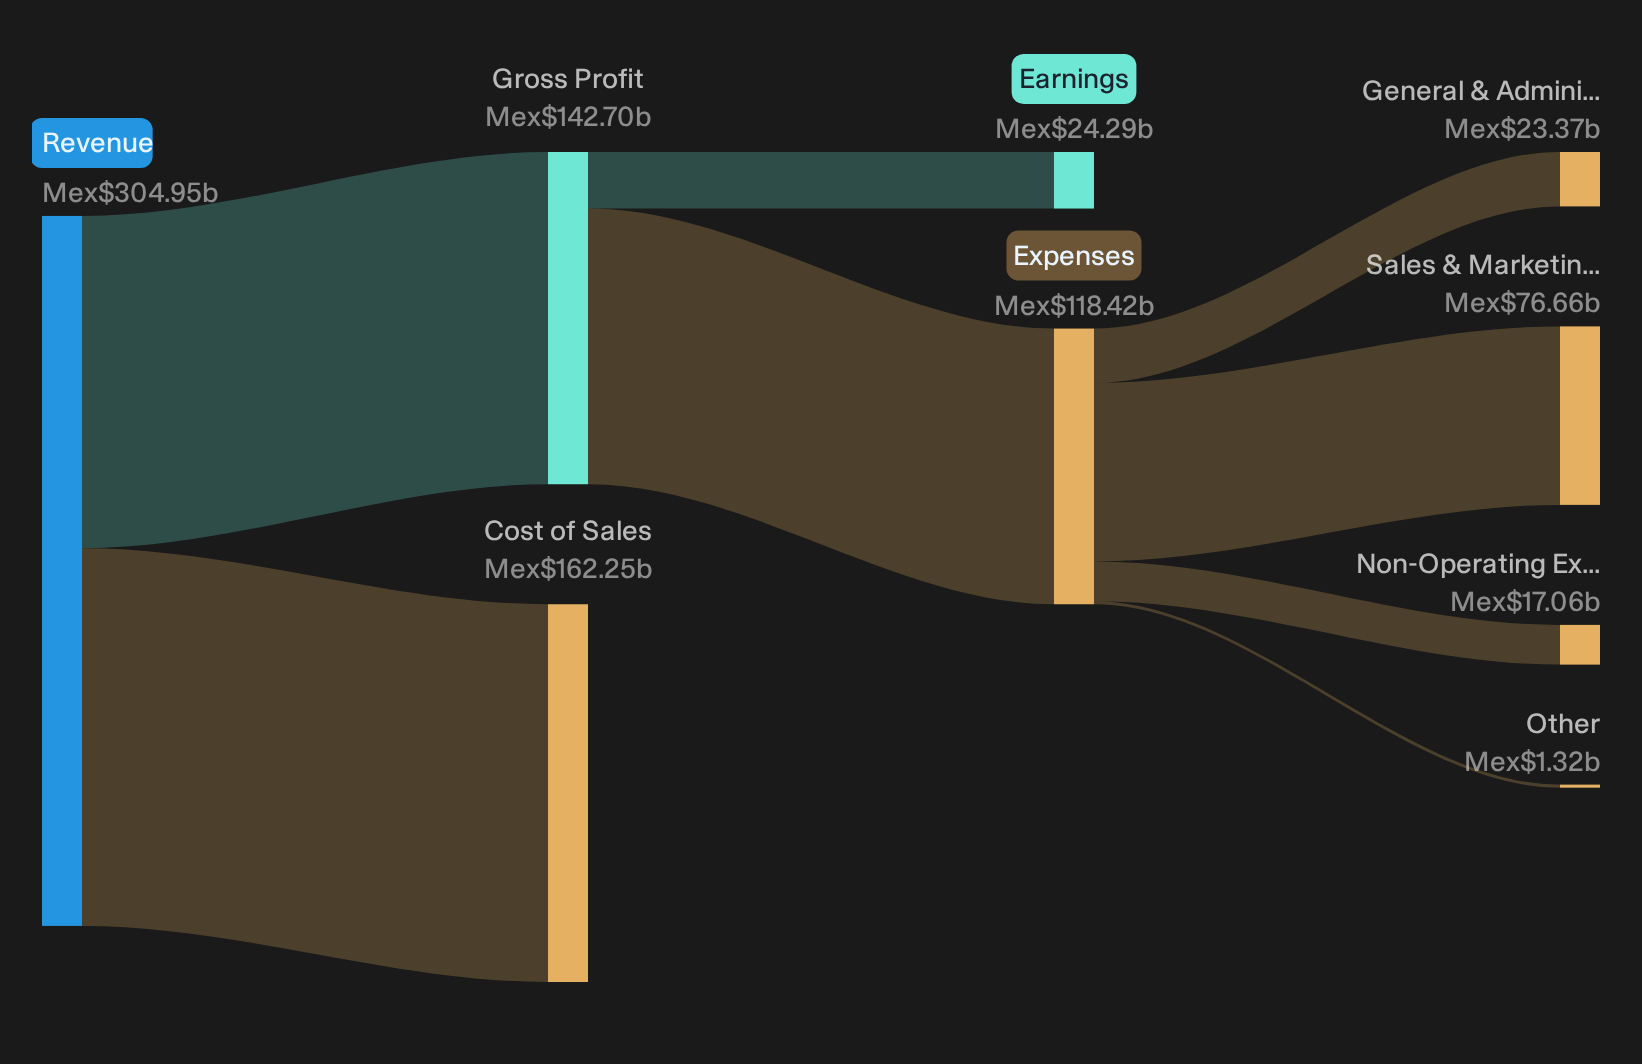
Coca-Cola FEMSA entered this Q3 2026 report with its stock only slightly ahead over the past month, then the price slipped about 2% on the day to $113.63. That looks more like a mood swing than a verdict. The business just reported record quarterly volume of 1.1b unit cases and revenue of MXN 79,718m, with adjusted EBITDA rising to MXN 16,800m and a wider margin. The reset in the share price appears inconsistent with earnings that indicate stronger underlying profitability rather than a crack in the story.
Love Coca-Cola FEMSA’s record volume and wider profitability but worried the share price reaction is sending mixed messages? Compare this earnings setup with our screener of companies that pair disciplined balance sheets with resilient cash generation in the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): MXN 79,718m vs. MXN 71,883.7m (up about 10.9%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): MXN 6,223m vs. MXN 5,897.7m (up about 5.5%)
- Basic EPS (Q3 2026 vs Q3 2025): MXN 29.62 vs. MXN 28.10 (up about 5.4%)
- Adjusted EBITDA Margin (Q3 2026 vs Q3 2025): 21.1% vs. 20.1% (expanded by 100 bps, or 1 percentage point)
Earnings tell you what Coca-Cola FEMSA. de reported this quarter, but investors who care about what they are paying for the business often study the cash moving through the system instead of just the income statement.
On Coca-Cola FEMSA. de's cash flows alone, the stock could be a hefty 32% undervalued.
Coca-Cola FEMSA: Bullish Playbook Meets Hard Numbers
The upbeat case hinges on Coca-Cola FEMSA turning digital penetration and mix into better earnings quality rather than just higher volumes.
"Bullish analysts expect Coca-Cola FEMSA to continue turning its digital tools, such as higher digital order penetration and salesforce apps, into ongoing gains in revenue quality and profitability across key markets."
Q3 provides concrete milestones. Juntos+ helped lift average ticket by 19% in Mexico and 18% in Brazil, while digital orders reached about 42% of traditional trade revenue in Brazil. At the same time, gross margin rose to 46.5% and adjusted EBITDA margin widened to 21.1%. That combination of richer tickets, higher digital mix and broader margin expansion supports the view that the digital and mix thesis is starting to appear in the income statement, even though the share price slipped about 2% on the day.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Coca-Cola FEMSA: Mexico Margin Wobble Keeps Bear Case Alive
Bearish analysts argue that affordability tactics in Mexico would show up as weaker pricing and stubbornly soft profitability.
"Despite South American operations supporting consolidated results, the contraction of operating margin in Mexico and Central America to 11.4% after higher marketing, IT, severance and depreciation costs indicates that future spending tied to digital rollouts and ERP projects may continue to dilute operating leverage and earnings if revenue growth does not keep pace."
Coca-Cola FEMSA’s Q3 numbers largely echo that concern. Mexico and Central America delivered 8.3% revenue growth and higher gross margin; however, operating income declined about 3.1% and operating margin narrowed 170 bps. Digital tools and mix are helping tickets and volumes, but regional profitability is still absorbing the cost of that investment.
Hunt For Mispriced Cash Engines
Coca-Cola FEMSA. de just showed how earnings strength and share price mood can briefly move in different directions. The real opportunity could sit in stocks where fundamentals quietly outrun current expectations.
- Company 1 - 42% below our estimate - targets large-format LED projects as customers replace static signs with software-linked displays and ongoing service contracts.
- Company 2 - 23% below our estimate - supplies liquid cooling and power equipment that data centre operators adopt when air-based systems reach physical and water-use constraints.
- Company 3 - 34% below our estimate - advises on complex capital raising and restructuring mandates as clients seek larger fee-rich private and cross-border transactions.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com