


EN
Is Tryg (CPSE:TRYG) Undervalued Or Is Its Recent Rebound Already Priced In?
Recent share performance context for Tryg
Tryg (CPSE:TRYG) has drawn fresh attention after a solid recent price run, with the stock up about 12% over the past month and modestly positive over the past 3 months.
Recent momentum in Tryg shares looks more like a short-term rebound than a full trend change, with a 12.1% 30 day share price return helping to offset an earlier year to date decline of 4.1%, and leaving the 1 year total shareholder return at 3.4%.
Scan how Tryg’s recent rebound compares with other insurers showing resilient returns by reviewing our hand picked 223 resilient stocks with low risk scores in the market right now.
Tryg looks like a solid Nordic insurer with long roots and steady business lines. After a 12% jump in 30 days, the key question is whether you are paying a fair price for that quality or stretching on valuation.
Most Popular Narrative: 4% Undervalued
Against a last close of DKK158.40, the most followed narrative on Tryg points to a fair value of about DKK165.67, suggesting a modest valuation gap built on specific assumptions about digitalisation, capital returns and underwriting discipline.
Digitalization and automation projects such as the Puzzel contact centre rollout and straight through processing of around 220,000 claims in Q3 2026 are expected to keep the expense ratio around the 13.3% to 13.4% level and to support future net margins.
See why 24 investors see Tryg as 4% undervalued.
Result: Fair Value of DKK165.67 (UNDERVALUED)
Still, this story can break if inflation keeps biting into claims before pricing catches up, or if increased customer churn in commercial lines dents premium momentum.
Find out about the key risks to this Tryg narrative.
Another view on Tryg’s valuation
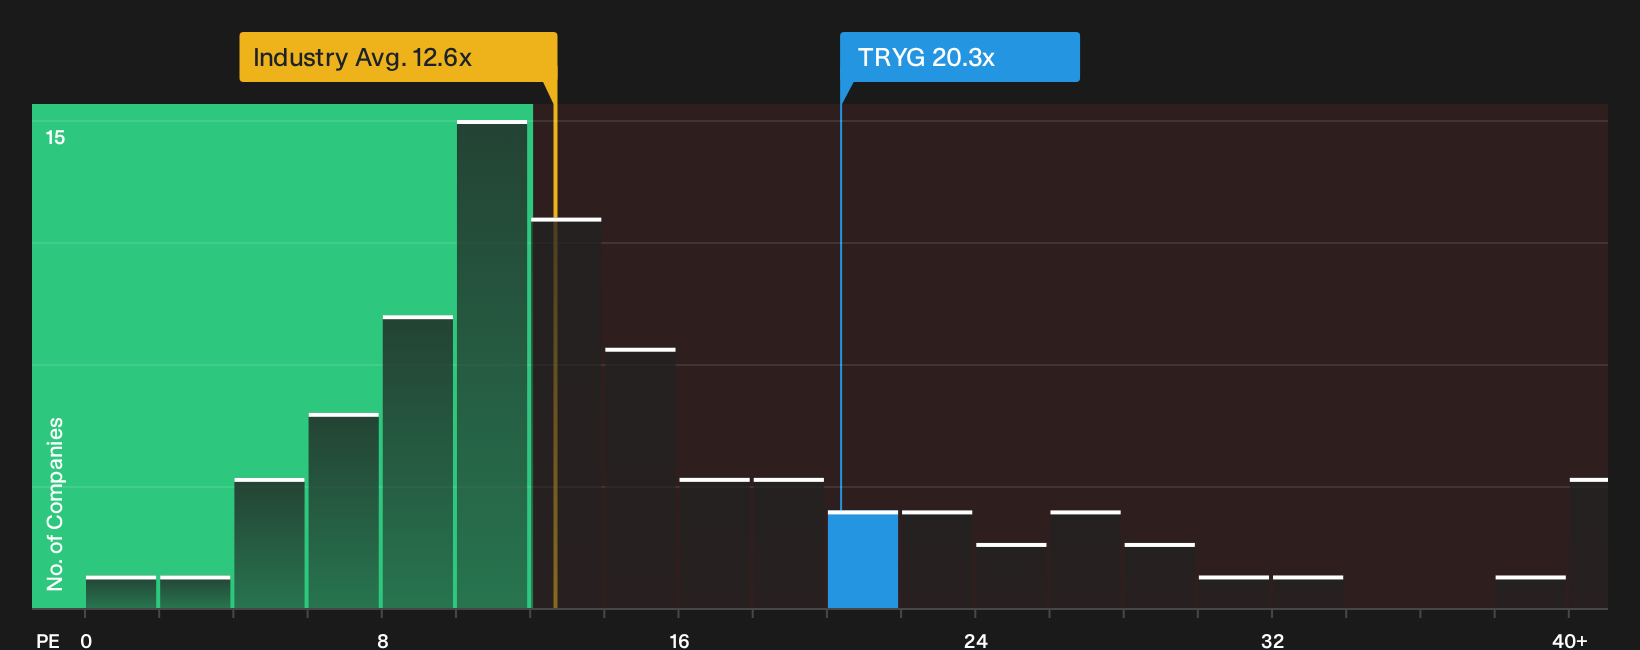
The narrative points to Tryg being modestly undervalued at DKK165.67, but the market is also putting a rich P/E of 20.3x on the shares. That is higher than both the European insurance sector at 12.6x and the peer average of 16x, even though the fair ratio is estimated at 22.6x.
A richer multiple can reflect confidence in earnings quality, yet it also leaves less room for disappointment if forecasts slip or sentiment cools. It raises a simple question for you as an investor: Is this premium something you are comfortable paying for Tryg today, or would you rather wait for the P/E to move closer to that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Tryg’s valuation and risk profile make this a judgment call for you, not the market. Act while the information is fresh and weigh both sides carefully with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tryg?
If Tryg has your attention, do not stop there. Cast the net wider and compare fresh opportunities that might fit your portfolio even better.
- Target resilient balance sheets and disciplined fundamentals by scanning our list of solid balance sheet and fundamentals (207 results) for candidates that may handle shocks more effectively than the broader market.
- Spot potential mispricings across quality companies by reviewing the 195 high quality undervalued stocks and see where current prices differ from underlying fundamentals.
- Build a watchlist of lesser known opportunities by checking the 610 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com