


EN
Whirlpool (WHR) Stock Rallies As Q3 Results Offer Margin Relief
Whirlpool just dropped its Q3 2026 scorecard, and the stock answered first. Shares climbed 3.7% on the day to US$27.42 after the release, even though the quarter featured another loss and thin profitability.
The market latched onto one thing. Management focused on margins, and ongoing EBIT margin inched up to 2.6%, with clear cost-cutting targets and fresh price increases across North and Latin America. Traders treated that as a relief rally after a rough few months, even as the broader picture still shows an unprofitable appliance company working to repair its income statement.
Like the Whirlpool turnaround story but concerned about ongoing losses and fragile margins? You can filter for appliance and consumer stocks with stronger profitability profiles using our screener of list of solid balance sheet and fundamentals stocks (24 results).
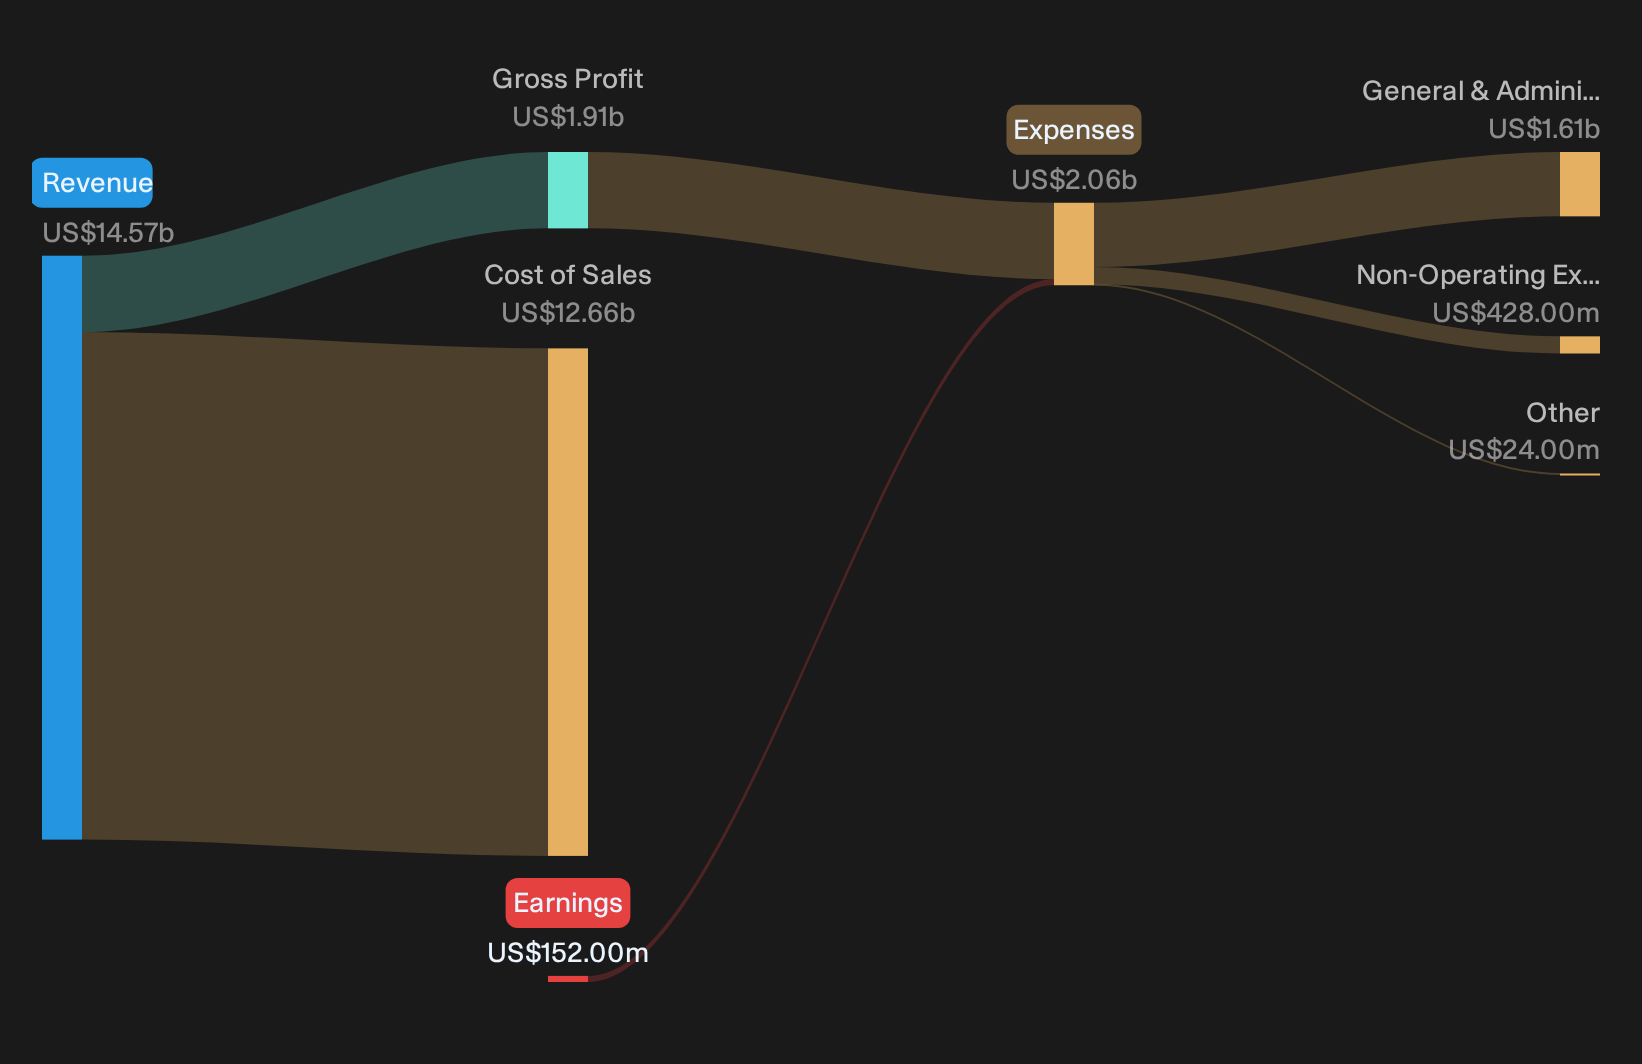
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,677 million vs. US$4,033 million (top line declined 8.8%)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$249 million vs. profit of US$73 million (moved from profit to loss)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$3.80 per share vs. profit of US$1.30 per share (shifted from per share profit to loss)
- Ongoing EBIT Margin (Q3 2026 vs. prior quarter Q2 2026): 2.6% vs. about 1.8% (sequential margin improvement of roughly 80 basis points)
Earnings tell you how Whirlpool is performing this quarter, but investors who care about what the shares might be worth often focus on cash flows instead. Based on Whirlpool's current cash flow profile alone, the stock could be a modest 8% overvalued.
Whirlpool Margin Story Meets Early Reality Check
Bulls argue Whirlpool can turn U.S. manufacturing heft, cost cuts, and product refreshes into durable margin gains. The ambition is clear.
"Bullish analysts expect Whirlpool to translate its U.S. manufacturing scale, cost takeout program, and new product launches into higher margins and a stronger market position as tariff effects and the refreshed appliance lineup flow through."
Q3 shows early, partial progress. Ongoing EBIT margin moved to 2.6% with about 80 basis points sequential improvement, and North America margins improved by about 230 basis points on pricing and product launches. At the same time, full year EBIT margin guidance came down to 2.0% to 2.2%, and Whirlpool reported another net loss. Execution on the margin goal is underway but not yet on target.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Whirlpool Bear Case Finds Fresh Support In Q3 Misses
Bearish commentary argued that Whirlpool might struggle to turn its cost plan into real cash while losses pile up.
"Despite a detailed program targeting about US$150 million of cost takeout in 2026 and further benefits from factory and logistics moves into 2027 and 2028, the company is still reporting very low ongoing EBIT margins and has already consumed more than US$2.0b of free cash flow in the first half of 2026."
Q3 results lean toward that concern. Ongoing EBIT margin sits at 2.6%, full year guidance has been cut to a range of 2.0% to 2.2%, and free cash flow again moved out, with management relying on year-end working capital actions to reach US$300 million.
Hunt For Mispriced Earnings Stories
Whirlpool just showed how a single quarter can shift sentiment without fixing every problem. The real opportunity is finding stocks that could be undervalued before patient buyers close that gap.
- Company 1 - 46% below our estimate - convert a record backlog of advanced data center and modular construction projects into installation and service work.
- Company 2 - 31% below our estimate - supply high-performance processors and integrated software that support enterprise artificial intelligence data center workloads.
- Company 3 - 34% below our estimate - expand an advisory platform shifting from pure dealmaking toward higher fee capital markets and private capital mandates.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com