


EN
Filter Press Startup Could Change The Case For Eldorado Gold Stock (TSX:ELD)
- Eldorado Gold reported that the first two of six Metso tailings filter presses at the Skouries mine in Greece are now running, allowing continuous plant operation as commissioning advances toward commercial production.
- This filtration milestone is important because four presses are needed to support commercial output on sulphide ore. As a result, investors have a clearer line of sight on when Skouries could start contributing meaningfully to group throughput and cash generation.
- We will now assess how Eldorado Gold's investment narrative could shift as Skouries moves closer to commercial production with key filtration capacity online.
Scan how other gold producers are positioned for the same kind of ramp up Eldorado Gold is targeting at Skouries by reviewing our hand picked 35 elite gold producer stocks.
Eldorado Gold Investment Narrative Recap
To own Eldorado Gold, you need to be comfortable that Skouries and McIlvenna Bay will move from heavy spend to reliable output without major hiccups. The filtration update at Skouries supports that story, since continuous operation is now possible, but the key near term catalyst is still clean, consistent performance as more presses are commissioned.
The biggest immediate risk remains project execution combined with cost pressure. Skouries carries a forecast capital spend of about US$1.315b and recent quarters showed growth spending driving free cash flow into a US$334 million outflow. Any delay or extra capex at Skouries or McIlvenna Bay would keep balance sheet pressure elevated.
The Skouries commissioning milestone ties directly into earlier guidance that the asset aims to reach commercial production in Q4 2026 after first copper gold concentrate in early September. With two of six filter presses running, Eldorado Gold appears closer to turning that timeline into an operational reality. This matters for when revenue from Skouries can be fully recognized.
That said, four presses are needed for commercial output on sulphide ore and five for nameplate throughput. The key catalyst is still the smooth ramp from two to at least four operating units. Any issues here would compound existing risks around inflation, higher royalties and already elevated all in sustaining costs, which previously sat at US$1,942 per ounce in Q1 2026.
What Analyst Forecasts Imply For Eldorado Gold
Eldorado Gold's narrative projects $5.3b revenue and $1.6b earnings by 2029. This is based on analyst assumptions of 37.5% yearly revenue growth and an earnings increase of about $982m from $618.1m today.
Uncover why Eldorado Gold's fair value indicates a 46% potential upside to its current price that may not last much longer.
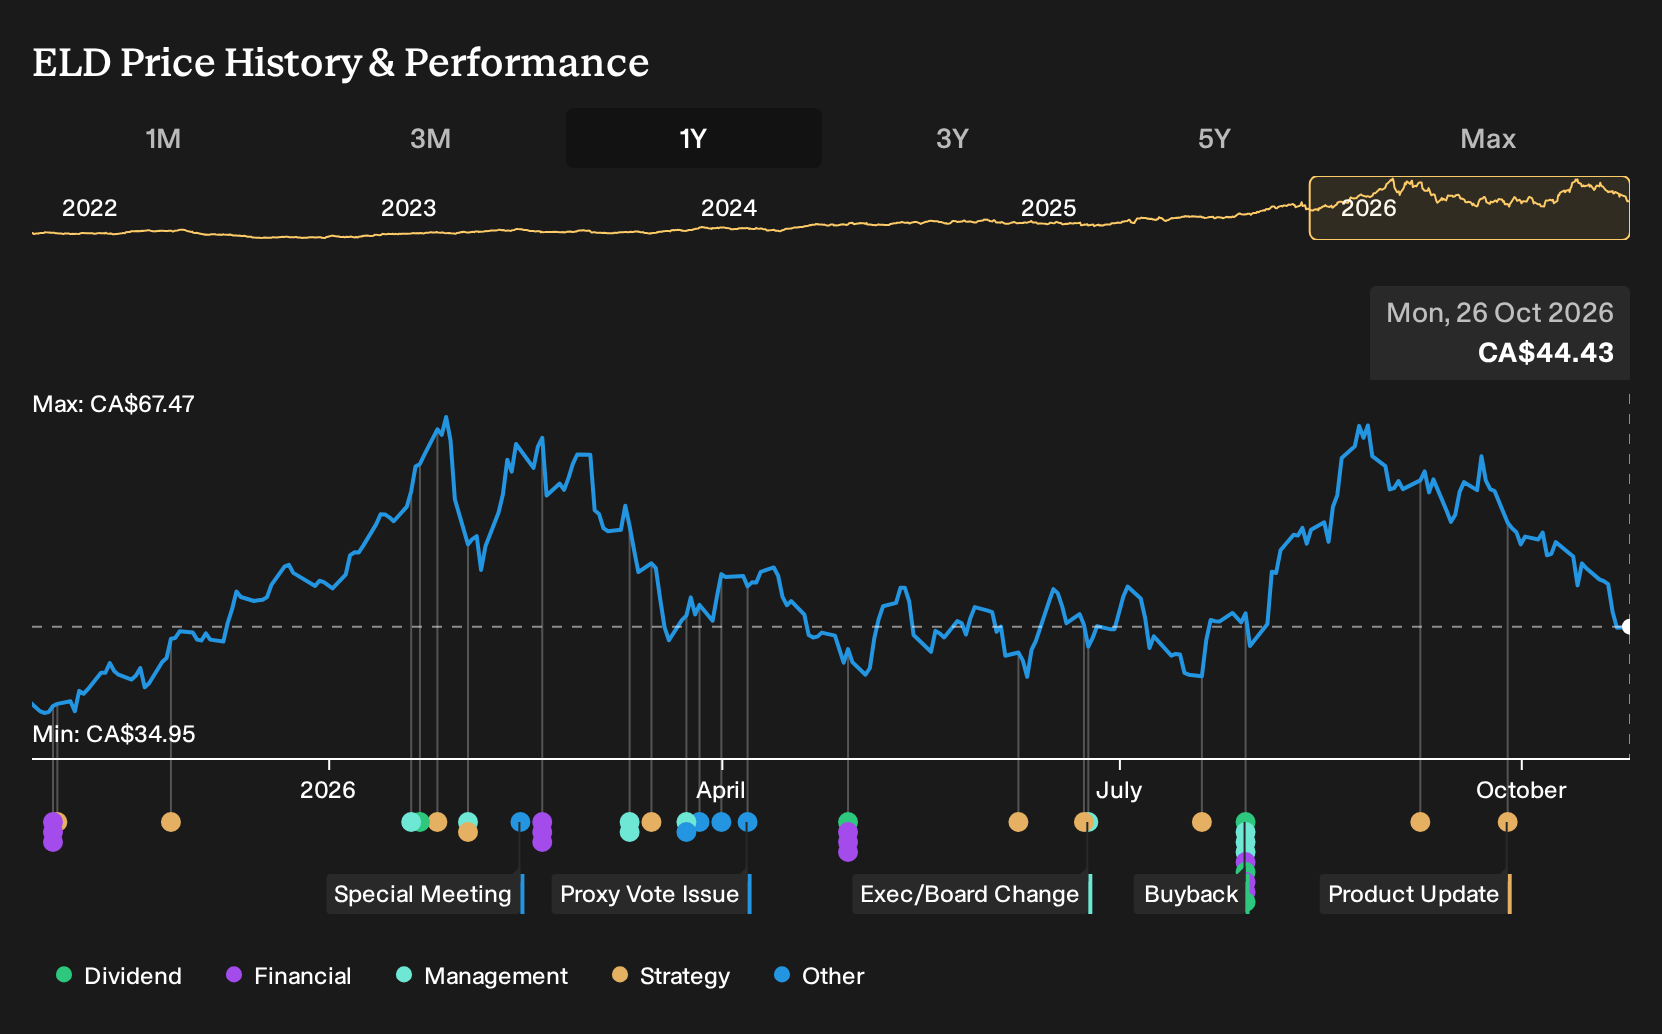
Exploring Other Perspectives
Cost pressure is the big swing factor in the alternate view on Eldorado Gold. In that story, persistent AISC near the Q2 2026 level of US$1,926 per ounce keeps a lid on the benefit from Skouries. The lowest analysts were already baking in about $4.6b revenue and $1.5b earnings by 2029 before this filtration milestone, so their case may evolve as new data lands.
Explore 5 other Eldorado Gold fair value estimates, including one that suggests it could be worth just CA$63.76.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eldorado Gold research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Eldorado Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eldorado Gold's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eldorado Gold?
If Skouries has put Eldorado Gold on your radar, it can be useful to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who want income to play a bigger role in returns, scan a curated set of higher yielding opportunities through our 3 dividend fortresses.
- If capital preservation and steadier balance sheets matter more to you than aggressive growth, filter for companies with stronger financial footing using the list of solid balance sheet and fundamentals (7 results).
- Readers hunting for mispriced potential can sift through a focused pool of opportunities that score well on both quality and value via our 3 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com