


EN
Medifast (MED) Q3 Results Deepen Losses As Coach Count Shrinks
Medifast came into this Q3 2026 report as a deeply out of favor weight management stock with a volatile track record and a share price stuck in the low teens. The print landed with a mixed message. Revenue held at about US$72.0m in a still unprofitable quarter, yet the market marked the stock up about 3% to US$12.49.
The main surprise was not the top line. It was the profit squeeze, with Medifast posting a quarterly net loss of US$17.5m as restructuring costs and a smaller coach base weighed on the income statement.
Like the Medifast story but worried about restructuring hits and ongoing losses? See a curated list that combines stronger balance sheets with cleaner income statements in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$72.0m vs. US$89.4m (revenue declined 19.4%)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$17.5m vs. loss of US$2.3m (loss widened materially)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$1.57 per share vs. loss of US$0.21 per share (per share loss increased significantly)
- Active Earning Coaches (Q3 2026 vs. Q3 2025): approximately 10,200 vs. approximately 19,500 (coach count reduced sharply, a key operational headwind)
Tired of scrolling through line after line of earnings figures and restructuring charges for Medifast? Get the full picture of the business, including a visual read on its financials, in the company report for Medifast.
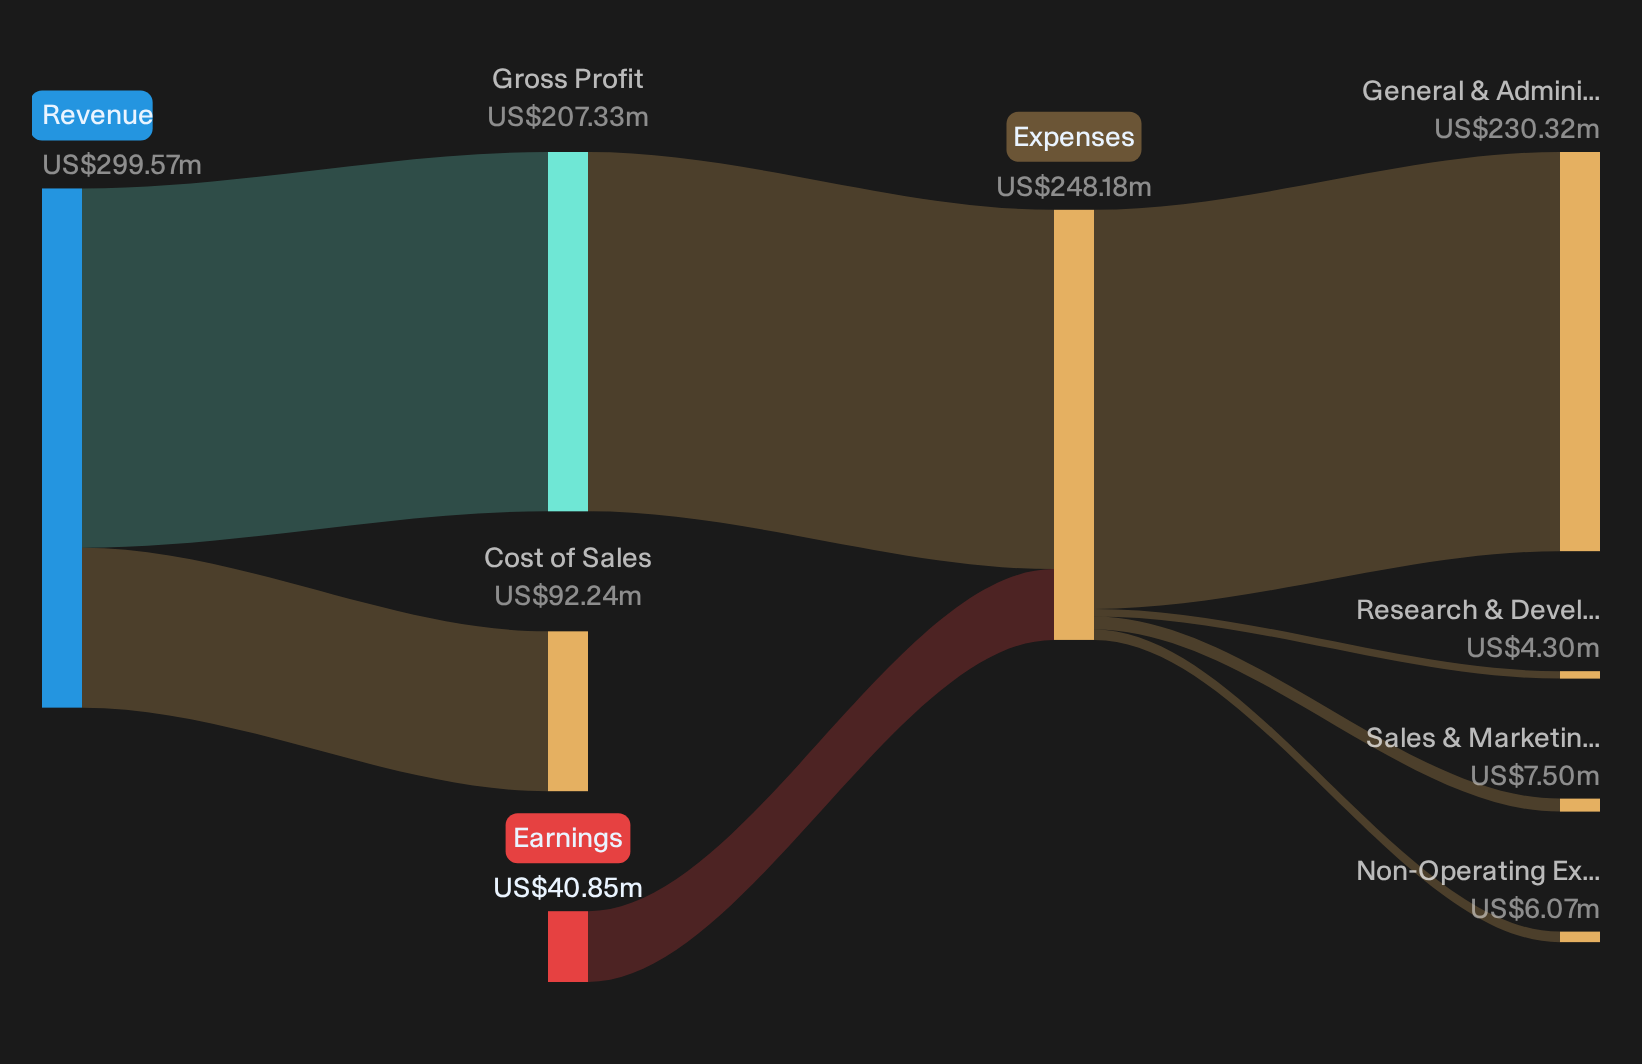
Medifast bull case leans on productivity and proof
The optimistic view hangs on Medifast turning coach productivity and metabolic health positioning into durable earnings power.
"The main thing that has to go right is that Medifast turns higher revenue per active earning coach, referral-driven client acquisition and planned cost savings into a sustainably profitable, clinically differentiated metabolic health platform, despite a smaller coach network."
Q3 shows part of that taking shape. Revenue per active earning coach reached US$7,064 and productivity improved for a fourth straight quarter, even as coach count fell to about 10,200. Non GAAP operating loss narrowed to US$4.0m and adjusted EBITDA excluding interest income turned positive, yet Medifast still reported a US$17.5m net loss and remains some distance from the profitability goal.
Medifast bear case focuses on shrinking network risk
The more cautious view argues that erosion in the coach base could choke any turnaround, regardless of branding or science.
"The number of active earning coaches fell by 44.9% year over year to about 14,000 in Q1 2026 and by 48.7% to about 11,700 in Q2 2026. If Medifast cannot stabilize or rebuild this coach base while GLP 1 drugs continue to pressure traditional weight loss, the smaller network could keep quarterly revenue under strain and limit the chance of returning to positive earnings."
Q3 did not ease that concern. Active earning coaches declined again to roughly 10,200, and quarterly revenue of US$72.0m remained well below last year. Management is guiding to another unprofitable full year and still expects coach numbers to contract near term, even while targeting Q4 profitability, so execution risk around rebuilding or at least stabilizing the network remains elevated.
One Narrative disagrees with today's price. → See where this Narrative says Medifast should trade.
Hunt Quiet Disconnects In Earnings
Medifast shows how a tough quarter can still produce a modest share price lift. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 27% below our estimate - supplies grid testing and diagnostic gear that utilities rely on as electrification and data center demand stretch aging infrastructure.
- Company 2 - 31% below our estimate - converts complex design wins in regulated hardware into long manufacturing runs once customers lock in suppliers for sensitive aerospace, medical and industrial programs.
- Company 3 - 46% below our estimate - signs long duration construction contracts tied to a backlog of mega projects that can throw off cash if legacy disputes are contained.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com