


EN
Will Hydrogen Pipeline Deal Change Kawasaki Heavy Industries Stock Narrative
- Kawasaki Heavy Industries and Romanian gas transmission operator SNTGN Transgaz SA signed a memorandum of understanding to bring Kawasaki’s hydrogen transmission technology to Europe, backed by a combined €21 million from the Japanese and Romanian governments for research centers and a new generation centrifugal compressor deployment.
- The agreement gives Kawasaki Heavy Industries a government funded route to test its hydrogen pipeline technology in a European gas grid. This can clarify real world performance, lifecycle costs, and commercial viability for future infrastructure projects.
- We will now look at how Kawasaki Heavy Industries’ investment narrative interacts with this government backed hydrogen transmission partnership in Europe.
Kawasaki Heavy Industries Investment Narrative Recap
To own Kawasaki Heavy Industries, you need to believe that its mix of hydrogen infrastructure, aerospace, rolling stock and powersports can keep translating into steady earnings growth, even while FX swings and tariffs pressure profitability. The hydrogen pipeline MoU in Romania looks directionally helpful for the hydrogen story, but on its own it does not change the near term picture.
Right now, the key near term swing factor is execution on large energy and aerospace programs so that record revenue and a stronger balance sheet keep feeding into cash flow. The biggest risk remains that FX, U.S. tariffs and planned equity and convertible issuance dilute per share outcomes faster than new projects contribute.
Against that backdrop, the planned ¥200b raise through new shares and convertible bonds is still the most important recent move around this hydrogen news. Management has flagged aircraft engines, gas turbines, robotics and hydrogen infrastructure as uses for this capital, which ties directly into projects like the Romanian transmission partnership.
For you, the link is simple. Successful deployment of hydrogen carriers, terminals and now pipeline technology in Europe would show that this funding is turning into real operating assets, while weak cash generation would leave the balance sheet more stretched and make the dilution from that capital increase harder to absorb.
Kawasaki Heavy Industries is framed around analyst expectations that revenues reach ¥2,950.3b and earnings hit ¥164.6b by 2029, based on an assumed 7.6% yearly increase in revenue and an earnings rise of ¥45.0b from ¥119.6b today.
Uncover why Kawasaki Heavy Industries' fair value indicates a 66% potential upside to its current price that could narrow quickly.
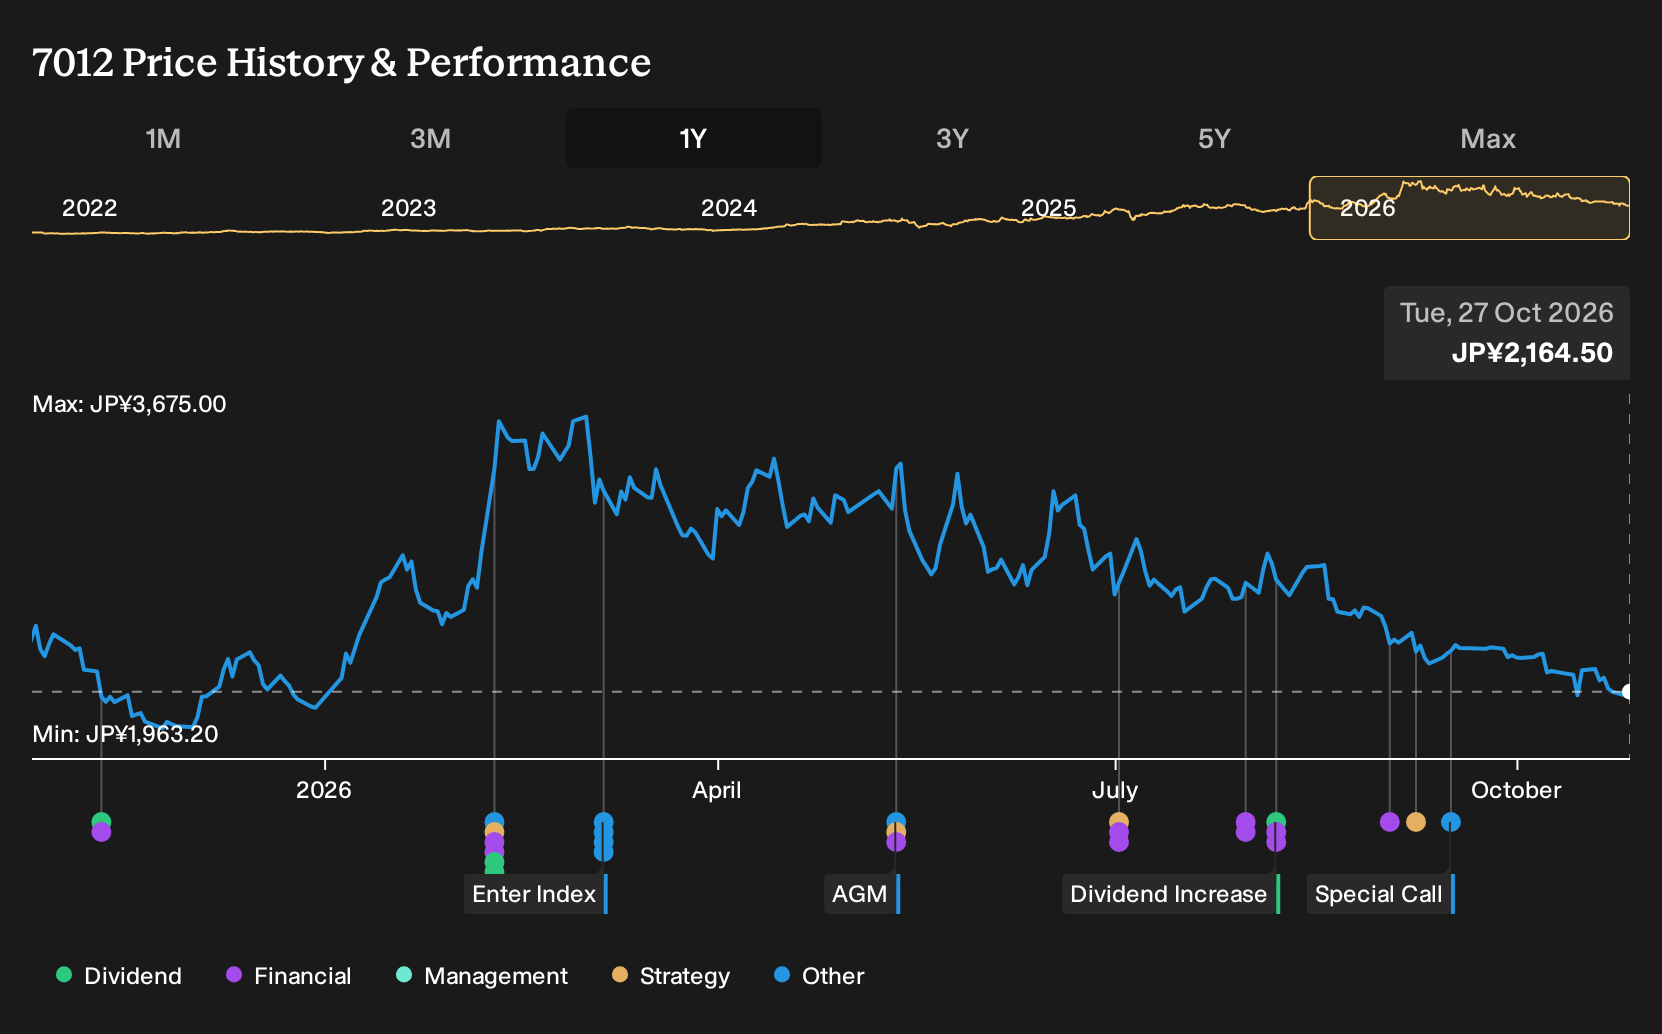
Exploring Other Perspectives
Some of the lowest Kawasaki Heavy Industries forecasts leaned hard into hydrogen execution risk. Those analysts assumed revenue of ¥2,853.3b and earnings of ¥151.0b by 2029 and saw only a modest uplift in margins. The new Romania hydrogen transmission deal could eventually push that cautious story to evolve, in either direction, so consider a range of possible outcomes and explore multiple sets of expectations before deciding how you view the stock.
Explore 3 other Kawasaki Heavy Industries fair value estimates, including one that suggests as much as 100% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Kawasaki Heavy Industries research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kawasaki Heavy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Kawasaki Heavy Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kawasaki Heavy Industries?
If you want to cross check your view on Kawasaki Heavy Industries against other opportunities, the Simply Wall St Screener can help you quickly sort through companies by quality, valuation and balance sheet strength.
- For investors who want resilient balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (23 results) and compare how other businesses stack up against Kawasaki Heavy Industries on financial strength.
- If you care most about valuation and potential mispricing, scan a focused 16 high quality undervalued stocks that filters for companies combining stronger fundamentals with lower implied expectations in their current prices.
- For those building a portfolio tilted to income, review a targeted 29 dividend fortresses that screens for higher yielding stocks where payout strength is a central part of the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com