


EN
Why Guangdong Investment (SEHK:270) Is Back In The Spotlight
Guangdong Investment (SEHK:270) just released unaudited earnings for the nine months to 30 September 2026, with both sales and net income higher than a year earlier, giving investors fresh numbers to reassess the stock.
Those fresh figures land after a strong run in Guangdong Investment’s shares, with a year to date share price return of 26.75% and a 3 month share price gain of 3.09%. The 3 year total shareholder return of 95.98% points to momentum that has built over a longer horizon, even as the 7 day share price return declined 2.97% ahead of the announcement.
Compare Guangdong Investment's latest move with a curated group of utilities and infrastructure players that currently screen as list of solid balance sheet and fundamentals (207 results).
Guangdong Investment now couples that earnings uplift with a strong multi year share run. The real question is whether the risk reward still leans toward buyers once valuation enters the frame.
Preferred P/E of 11.5x: Is it justified for Guangdong Investment?
On simple earnings terms, Guangdong Investment trades on a P/E of 11.5x, which leaves the stock looking mixed once both peers and an internal fair value P/E are brought into the picture.
The P/E ratio compares the current share price to earnings per share. For a utility style group like Guangdong Investment, that metric often reflects what the market is willing to pay for relatively steady cash generation rather than rapid expansion.
Guangdong Investment’s current earnings profile shows 13.4% earnings growth over the past year, an improvement on its 5 year record of declining profits and stronger than the wider Water Utilities industry’s 3.8% result. A P/E of 11.5x against an estimated fair P/E of 9.4x suggests investors are currently paying a richer tag than the level regression analysis points to. That could be a level the market moves toward if sentiment cools.
Set against peers, the contrast is even sharper. The same 11.5x P/E compares to an Asian Water Utilities industry average of 12x, so roughly in line at the sector level. Yet it is substantially higher than the peer group average of 7x, which implies Guangdong Investment trades at a clear premium to many closer comparables.
Explore the SWS fair ratio for Guangdong Investment.
Result: Price-to-earnings of 11.5x (OVERVALUED).
Still, Guangdong Investment faces two obvious swing factors: any drop in water segment earnings, or a harsher regulatory backdrop for utilities in Mainland China.
Find out about the key risks to this Guangdong Investment narrative.
Another View: What Does The DCF Say About Guangdong Investment?
The market may be paying a premium P/E, but the SWS DCF model points the other way. At HK$8.67, Guangdong Investment screens as trading about 63.1% below an estimated future cash flow value of HK$23.47. That raises a simple question: Are current earnings the wrong anchor?
Look into how the SWS DCF model arrives at its fair value.
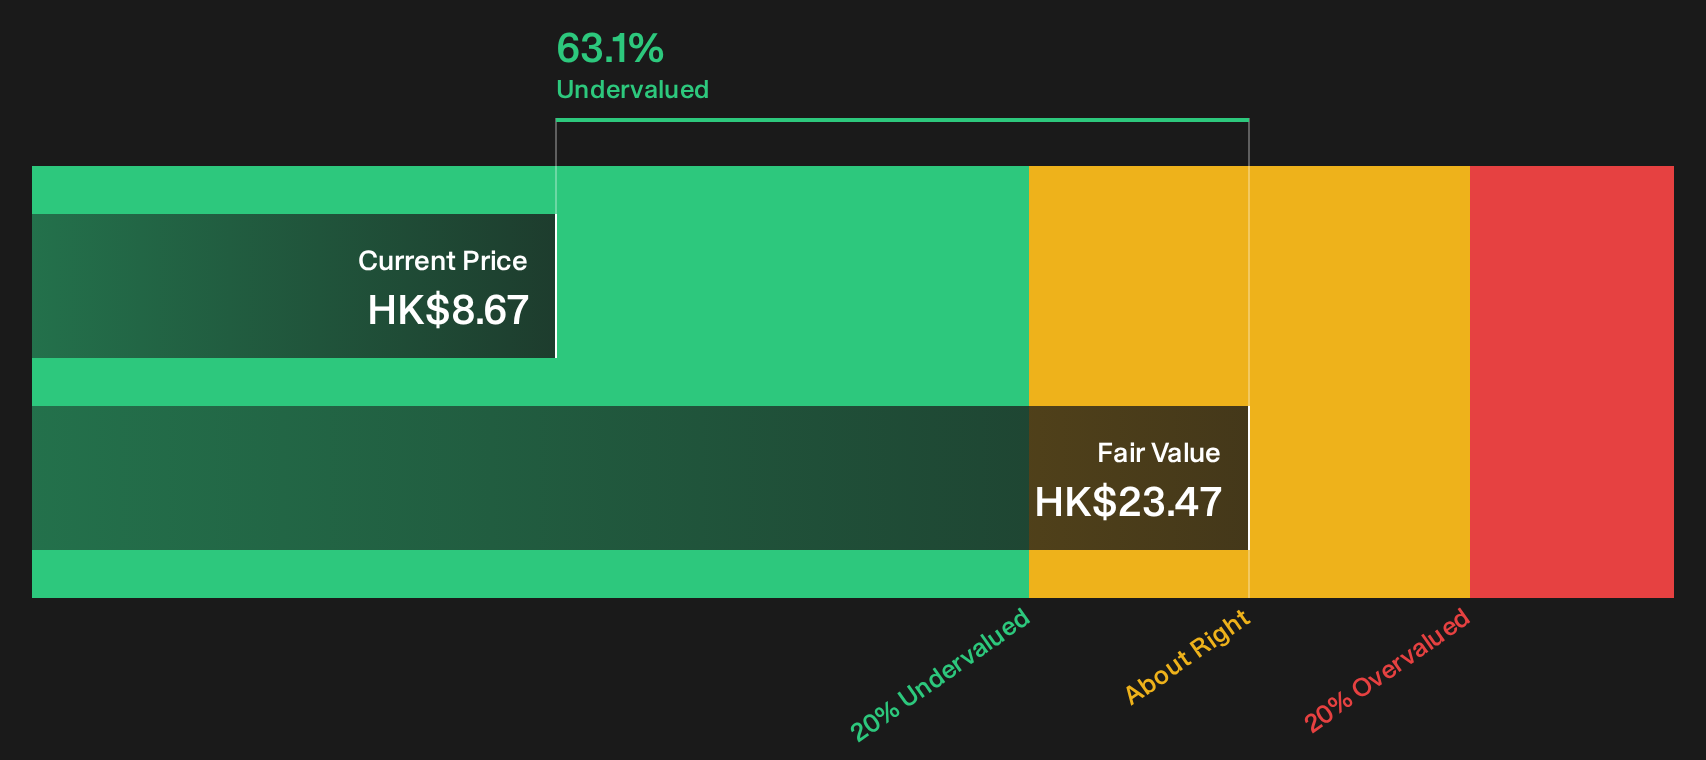
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Guangdong Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Guangdong Investment's valuation and cash flows make it a stock you need to size up directly and decide where you land. Given there is at least one risk that investors are cautious about and at least one potential reward that others are backing, start by weighing the 2 key rewards and 1 important warning sign
Looking for more Guangdong Investment ideas and beyond?
If Guangdong Investment has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted filters that surface very different kinds of opportunities.
- Hunt for quality on sale by scanning a curated pool of companies that currently screen as 195 high quality undervalued stocks.
- Build a steadier income stream by checking out businesses that show up in our rigorously filtered 224 dividend fortresses.
- Protect the downside first and look at companies that clear our resilience checks in the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com