


EN
Missed WisdomTree's Run? Here's What Early Buyers Saw
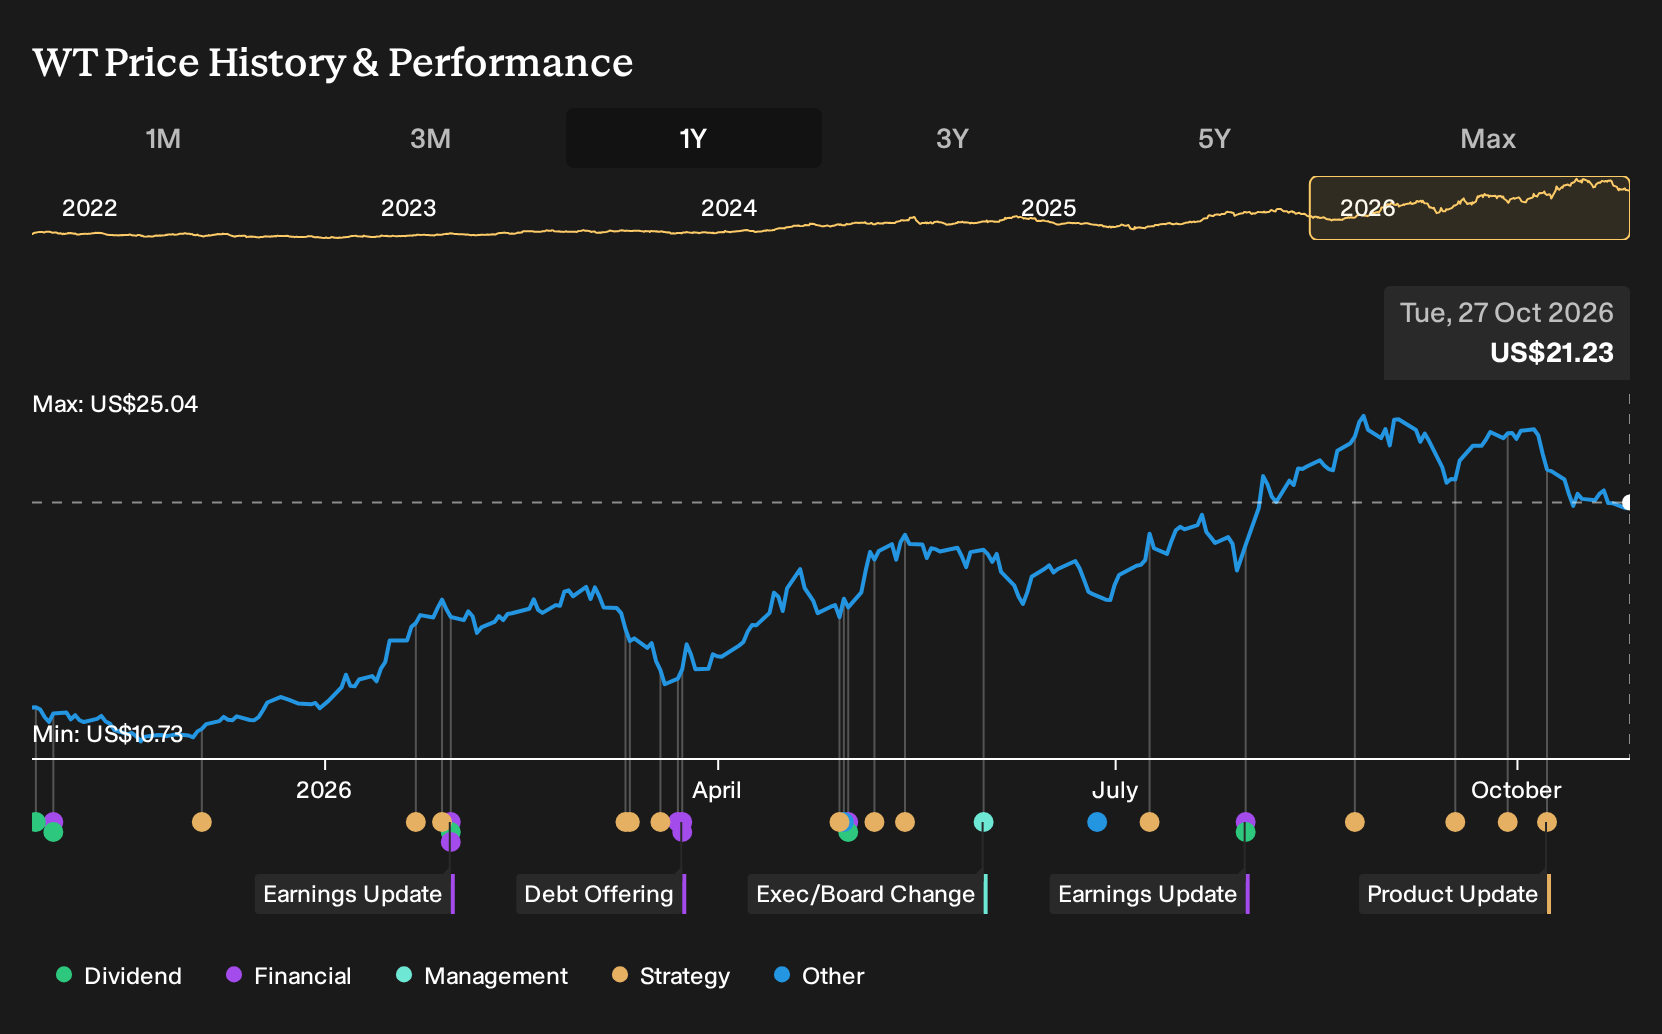
For WisdomTree shareholders, the return over the past year was 72.8%, including dividends. That kind of jump grabs attention. Yet the real story is what you knew back on 26 October 2025, when analysts disagreed on whether blockchain bets, tokenized funds and the Ceres farmland deal would justify a richer valuation. If you were weighing an investment then, which mattered more: the upside from digital and alternatives or the pressure from low fees and bigger rivals?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
WisdomTree has already moved. Pinpoint other ways to investigate the theme among 55 AI infrastructure stocks.
The Two WisdomTree Stories Investors Were Arguing About
The shares cost US$12.15 at the start of the period. Anyone looking at WisdomTree back then had to decide whether the price already reflected its digital bets and the Ceres farmland move, or whether those were still underappreciated.
The bullish Narrative set Fair Value at US$15.92, based on early blockchain infrastructure and regulatory positioning, as well as the view that tokenized money market products and stablecoins could support stronger long term earnings power.
The bearish story pointed to Fair Value of US$11.5 and leaned on fee pressure, rising regulatory costs and the risk that heavy spending on digital assets and niche acquisitions would drag on profitability if adoption disappointed.
What The Results Changed For The WisdomTree Debate
WisdomTree’s later numbers gave the bullish story fresh support. Revenue reached US$177.16 million in Q2 2026 compared with US$112.621 million in Q2 2025, while net income, excluding extra items, moved from US$24.777 million to US$44.284 million and net margin widened from 22.0% to 25.0%. That tilt in both scale and profitability backed the optimistic case more than the cautious one.
The episode turned on one assumption investors argued about back in October 2025: that digital and alternatives could improve both growth and margins. When you look at another asset manager making similar claims, check whether higher AUM products or acquisitions actually show up as rising fee revenue and a fatter net margin, not just headlines and new tickers.
What WisdomTree’s Run Leaves You Paying For Today
WisdomTree now trades at US$20.98. The selected Narrative places Fair Value above that level, based on the idea that the business is still not fully credited for its earnings power.
The focus has shifted to how fee mix, tokenized products and acquisitions support higher margins. A buyer today has to judge whether firm wide revenue yield and operating margin can stay elevated as digital assets and model portfolios scale.
"The WisdomTree thesis has been reviewed and reaffirmed. The narrative is now shifting from a largely forward-looking expectation to one that leans more on visible data points across model portfolios, tokenized assets, higher-yielding acquisitions, and firm-wide margins."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 26% below our estimate - sells weight-loss and diabetes injectables into an already strong demand base.
- Company 2 - 39% below our estimate - expands device trade-in and refurbishment operations as supportive policies and preferences grow.
- Company 3 - 22% below our estimate - shifts new manufacturing capacity toward higher value AI data-center optics and photonics solutions.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com