


EN
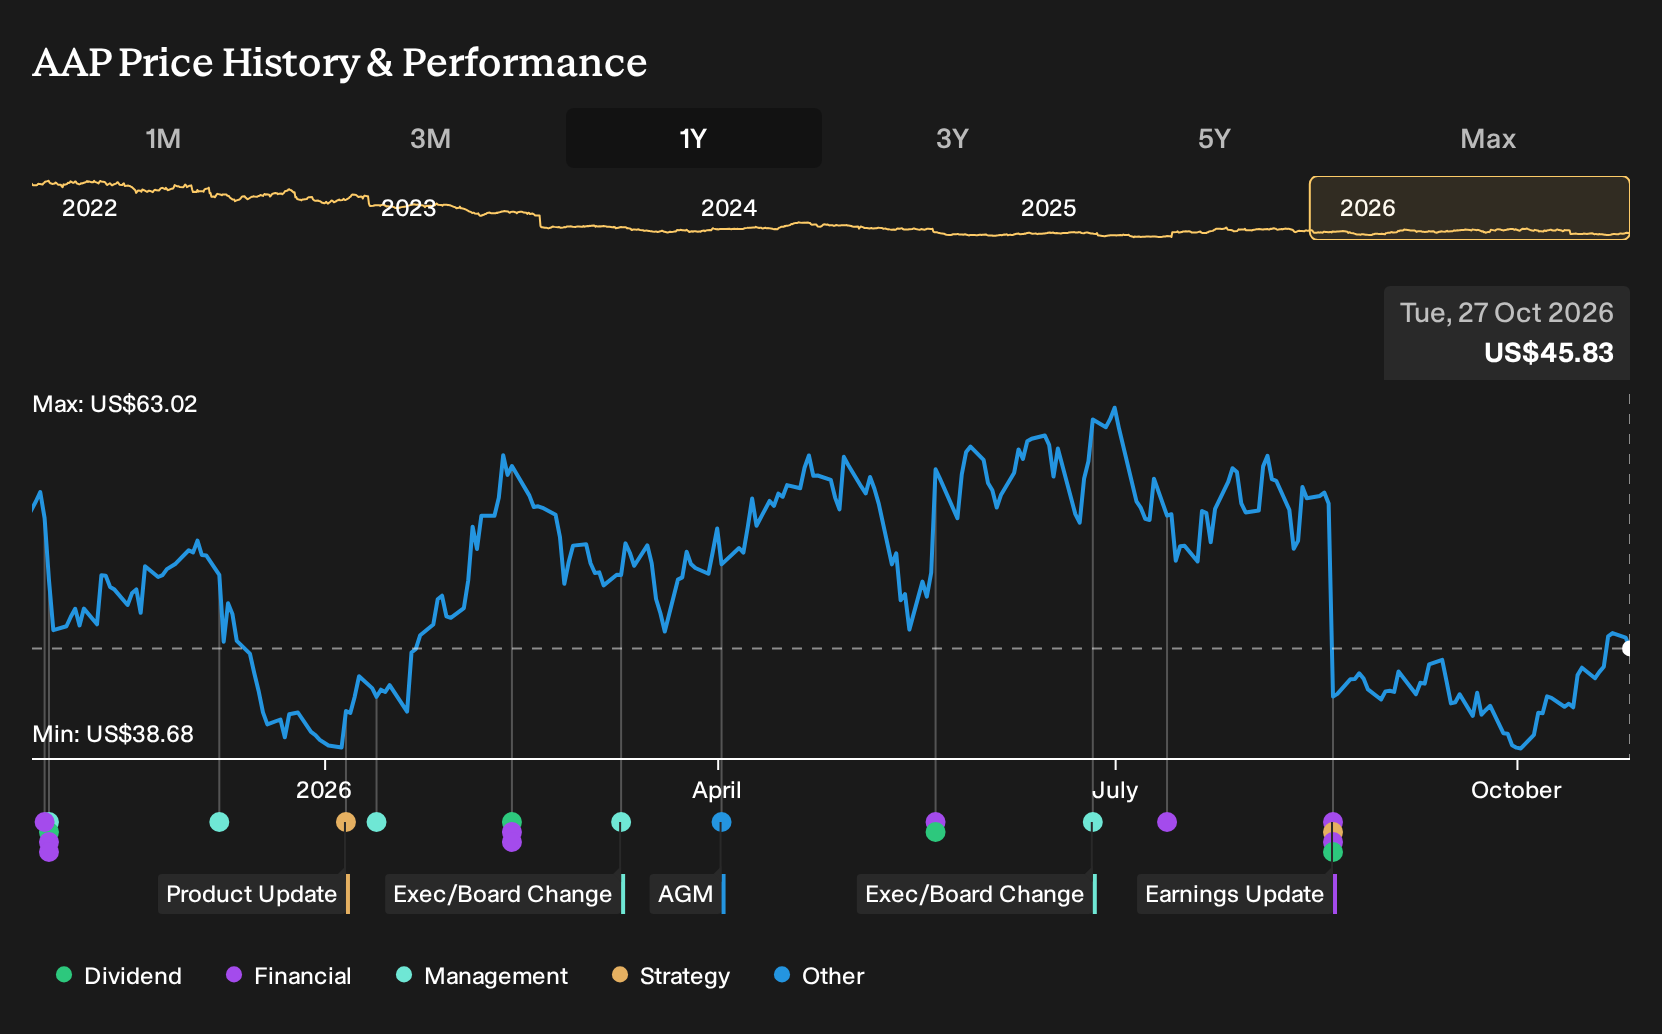
How Investors May Respond To Advance Auto Parts Stock After Raised Outlook
- Advance Auto Parts recently lifted its second half revenue outlook to 3% growth from 2%, while also receiving fresh analyst coverage that framed this updated guidance within a more cautious view of the business.
- The higher outlook highlights management’s confidence in current operational moves; however, the underperform rating underlines lingering questions about how quickly those efforts translate into durable profit improvement.
- We will now explore how Advance Auto Parts' raised second half outlook could reshape the investment narrative that analysts had built previously.
Balance that fresh guidance on Advance Auto Parts with a broader view of the sector and scan a hand-picked 29 high quality undervalued stocks that may offer stronger combinations of pricing power and balance sheet support.
Advance Auto Parts Investment Narrative Recap
To own Advance Auto Parts, you need to believe the turnaround on margins and operations will stick. The raised second half outlook to 3% revenue growth supports the idea that merchandising, supply chain consolidation, and the Pro mix shift are starting to show through. The near term catalyst is clear: better execution on comparable sales and margins that flows into cleaner earnings.
The biggest near term risk is that recent improvement proves patchy. DIY trends remain softer than Pro, and transitory costs from restructuring are still affecting results. With the stock on a premium P/E multiple and recent quarters viewed as underwhelming versus expectations, any further misses on comps or profitability could quickly reset sentiment.
The most relevant update here is that Advance Auto Parts lifted its second half revenue outlook from 2% to 3% growth. That tweak is small on paper, yet it matters because the whole margin story hinges on getting enough sales volume through a leaner distribution network and refreshed merchandising to support operating leverage.
Seen alongside the sector, where peers like AutoZone and O’Reilly are also expected to benefit from low to mid single digit inflation, the higher outlook invites a closer look at execution risk. Analysts covering the group have been more cautious on Advance Auto Parts, so the upgraded guidance now puts more pressure on management to translate that top line into cleaner margins and steadier free cash generation.
Advance Auto Parts' analyst narrative points to revenues of US$9.0b and earnings of US$275.3m by 2029, built on an assumed 1.5% yearly revenue growth rate and an earnings increase of about US$166.3m from current earnings of US$109.0m.
Uncover how Advance Auto Parts' fair value indicates a 7% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One alternate angle on Advance Auto Parts focuses less on the margin turnaround and more on execution risk. Before this H2 outlook upgrade, the most optimistic analysts were already pencilling in about US$9.2b of 2029 revenue and US$358.5m of earnings. That is far rosier than the baseline. It shows how widely expectations can differ and why it makes sense for you to compare multiple narratives as this new guidance filters into fresh forecasts.
Explore 2 other Advance Auto Parts fair value estimates, including one that suggests as much as 46% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Advance Auto Parts research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Advance Auto Parts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advance Auto Parts' overall financial health at a glance.
Looking For More Ideas Beyond Advance Auto Parts?
If the shifting story at Advance Auto Parts has you thinking about portfolio balance, it can help to line it up against a broader watchlist of potential opportunities with different risk and income profiles.
- For investors who care most about balance sheet strength and fundamental resilience, scan a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on sturdier financial profiles.
- If you want potential mispricing on your side, review a targeted 21 high quality undiscovered gems that filters for quality businesses that may not be widely followed yet.
- Income focused investors can put yield and durability front and center by checking a refined 5 dividend fortresses that screens for higher distributions backed by more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com