


EN
Why Is Eversource Energy (ES) Getting Fresh Attention Now?
A proposed class action targeting Eversource Energy (ES) over an alleged October cyberattack has pushed the utility’s cybersecurity controls into focus for investors, legal observers and customers watching data protection risks.
Eversource Energy’s recent headlines come on top of a mixed trading pattern, with the share price up 4.8% over the past week and 6.1% over the past month, yet down about 10.4% over 90 days and the 1 year total shareholder return lower by 5.4%. This points to momentum that has only recently begun to stabilise near the latest US$67.55 level as investors reassess both regulatory pressure on future rate hikes and cyber risk.
Scan a curated group of utilities facing similar regulatory and operational pressures as Eversource Energy with the 42 power grid technology and infrastructure stocks that could be setting up for the next leg of momentum.
After a sharp short term rebound but a weaker 1 year return, Eversource Energy now forces a practical choice: lean into the current US$67.55 level or wait and see what the valuation work suggests about a better entry point.
Most Popular Narrative: 6% Undervalued
Against the last close at $67.55, the most followed valuation story for Eversource Energy points to a fair value of $72.00 and leans on a specific set of long term assumptions about regulated investment and earnings power.
Accelerated investment in grid modernization continues, supported by a 5 year US$26.5b capital plan through 2030 and potential upside from nearly US$1b of advanced metering infrastructure in Connecticut and new substations. These investments could improve reliability and operating efficiency and support net margins.
See why 18 investors see Eversource Energy as 6% undervalued.
Result: Fair Value of $72.00 (UNDERVALUED)
Still, the Eversource Energy story can change quickly if regulators keep trimming allowed returns, or if additional storm and project costs land back on the balance sheet.
Find out about the key risks to this Eversource Energy narrative.
Another View: Multiples Paint A Richer Picture For Eversource Energy
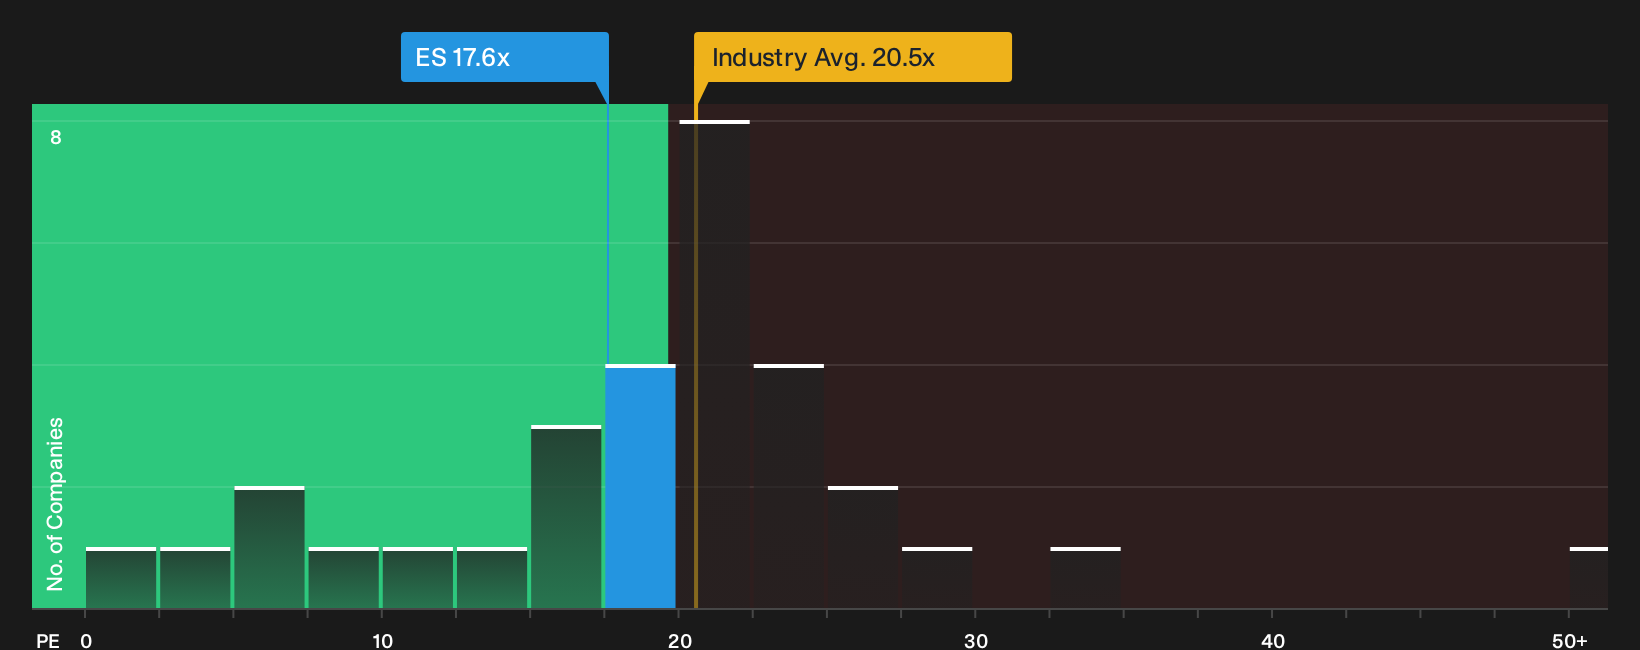
That 6% undervalued fair value story runs into a different message once you look at simple pricing ratios. On a P/E of 17.6x, Eversource Energy trades above the peer average of 15.2x and below the wider US Electric Utilities group at 20.6x, while the fair ratio sits even higher at 21.1x. For you as an investor, that mix can feel like paying up versus close peers, yet still leaving room if the market leans toward the fair ratio over time. The question is which side of that trade off matters more to you right now.
For a closer look at what the current P/E gap might mean in practice, and how it compares with other utilities, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Signals on Eversource Energy are mixed so far. If you want to move quickly and build your own stance, consider both perspectives using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eversource Energy?
If Eversource Energy has sharpened your focus on risk, reward and valuation, do not stop here when other opportunities could be lining up for your watchlist.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations through the 29 high quality undervalued stocks.
- Strengthen income potential by reviewing resilient payouts from the 5 dividend fortresses.
- Dial down volatility by focusing on companies with steadier profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com