


EN
Is VAT Group (SWX:VACN) A Bargain After Raising Its 2027 Sales Outlook?
VAT Group (SWX:VACN) has put fresh numbers on the table, lifting its 2027 sales outlook to significantly above the prior CHF 1.5b to 1.7b range and tightening expectations around near term performance.
The guidance update comes after a choppy few weeks for VAT Group, with the 30-day share price return down 9.35%. However, the year-to-date share price return is 37.22%, and the 1-year total shareholder return of 77.56% indicates that longer-term momentum has been strong despite recent volatility around expectations and risk appetite.
Capitalize on the renewed interest around VAT Group by scanning a curated set of quality industrial and capital-goods peers through the list of solid balance sheet and fundamentals (207 results).VAT Group now trades at a double discount, roughly 20% below analyst targets and only around 1% below one intrinsic value estimate after a sharp reset in recent weeks. Is that caution mispriced, or earned by the guidance risk?
Most Popular Narrative: 20% Undervalued
VAT Group’s most followed valuation narrative points to a fair value of CHF 744, which sits above the last close at CHF 593.60 and frames the current pullback as a test of how much growth investors are willing to underwrite.
The industry's transition to next-generation chip nodes (e.g., Gate-All-Around, 2nm), together with more than 100 new fabs under construction and increasing technological complexity in manufacturing, is expanding the addressable market for high-precision vacuum equipment. This is positioning VAT to outpace wafer fab equipment market growth and drive above-market revenue gains over the next several years.
See why 23 investors see VAT Group as 20% undervalued.
Result: Fair Value of CHF744 (UNDERVALUED)
Still, the narrative can crack if semiconductor capex turns weaker than analysts assume, or if VAT Group’s growing China exposure runs into harsher export controls.
Find out about the key risks to this VAT Group narrative.
Another View on VAT Group’s Rich Valuation
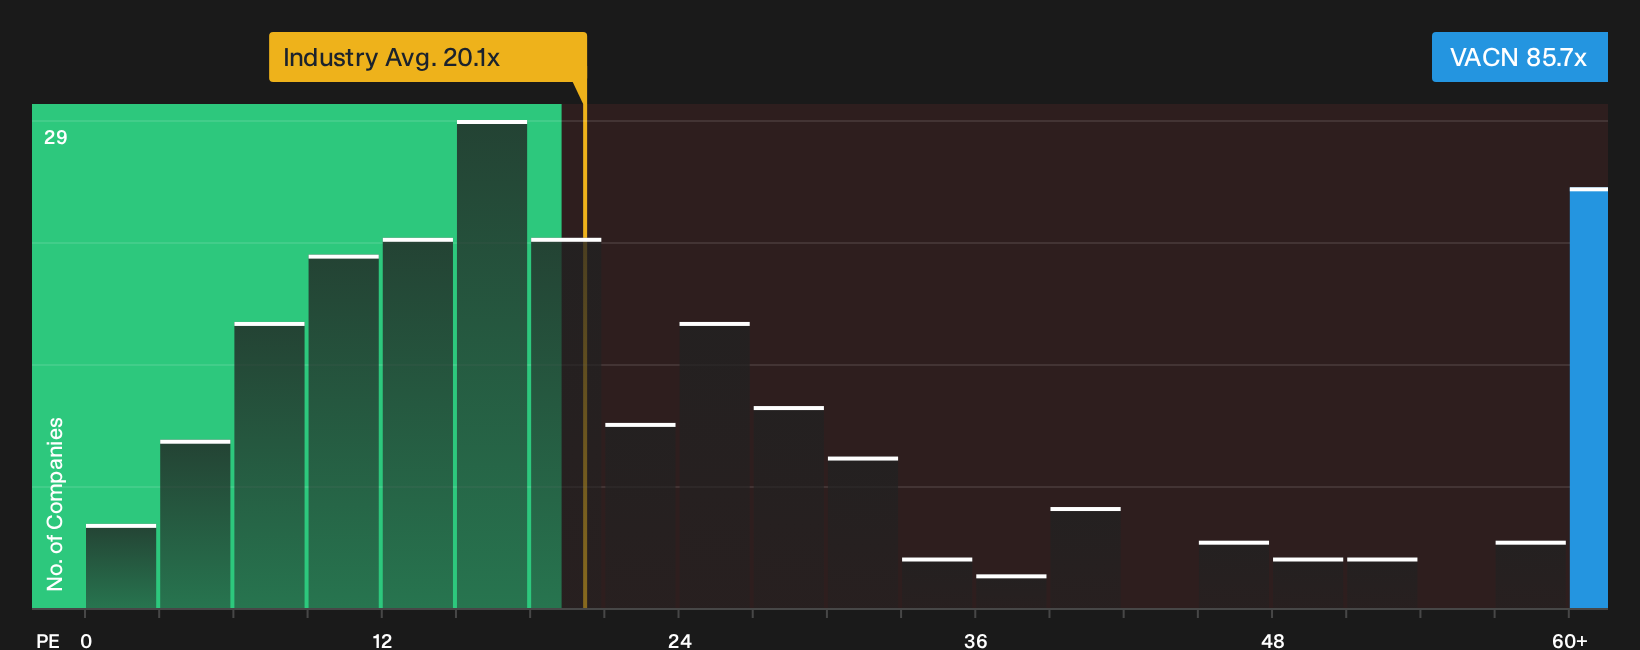
The first story paints VAT Group as roughly 20% undervalued versus analyst targets, yet the market is already paying a steep price. The current P/E of 85.7x compares with 20.1x for the European Machinery group and a fair ratio estimate of 45.2x. This leaves a lot of room for sentiment to cool before the numbers line up.
That gap can be read as optimism about future earnings quality or as valuation risk if growth assumptions fade. Which side of that trade do you want to be on when expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big valuation swings can make VAT Group look either exciting or stretched, depending on which data you focus on. Use the full set of metrics, stress test your own thesis, and then weigh up the 2 key rewards.
Looking for more investment ideas beyond VAT Group?
If VAT Group has your attention, do not stop here. The strongest portfolios come from comparing several quality opportunities before committing fresh capital.
- Target steadier potential by reviewing companies that appear conservatively valued and financially robust through the 195 high quality undervalued stocks.
- Boost your income focus by scanning reliable payers with strong balance sheets via the 224 dividend fortresses.
- Get ahead of the crowd by reviewing a 610 high quality undiscovered gems before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com