


EN
How Investors May Respond To Talos Energy (TALO) Earnings Upgrade
- Talos Energy recently received an analyst upgrade tied to a stronger earnings outlook, supported by a trend of rising earnings estimates over recent months.
- The shift in expectations places fresh attention on Talos Energy's ability to turn its offshore exploration and production portfolio into more durable, cash-generative operations.
- This development raises questions about how Talos Energy's investment narrative could be affected by the upgraded earnings outlook highlighted in this research.
Talos Energy Investment Narrative Recap
To own Talos Energy, you need to be comfortable with a focused offshore producer that is working to turn a Gulf of Mexico heavy portfolio into steadier, higher margin cash generation. The current story hinges on execution of efficiency programs, disciplined development of high margin fields, and tight control of capital spending in a capital intensive business.
The Zacks earnings upgrade and rising estimates spotlight that operating thesis, but they do not change the core near term swing factors. The key catalyst still sits in hitting production and cost targets tied to the US$100 million a year efficiency plan. The biggest risk remains operational and regulatory pressure in the Gulf, along with future abandonment and decommissioning costs.
The Argus report that raised Talos Energy’s target price to US$19.00 ties into this backdrop because it reflects outside scrutiny of the same drivers investors are watching. That external work still comes back to execution on offshore projects, capital discipline, and the firm’s ability to move from reported net losses of US$404.983 million toward more stable profitability.
For you, the useful link between the analyst upgrade and this earlier Argus call is the emphasis on operating delivery. Higher earnings expectations only become durable if cost savings, high margin Gulf projects, and balance sheet flexibility play out in the actual numbers, while known risks around hurricanes, regulation, and long lived asset liabilities stay manageable.
Talos Energy Forecasts vs Today’s Earnings Reality
Talos Energy's analyst narrative points to revenues of US$2.3b and earnings of US$63.4 million by 2029. That profile assumes 5.2% yearly revenue growth and a shift in earnings from a loss of about US$405.0 million today to positive territory, which is an earnings swing of roughly US$468.4 million.
Uncover why Talos Energy's fair value indicates an 11% potential upside to its current price, a discount that could close quicker than many investors expect.
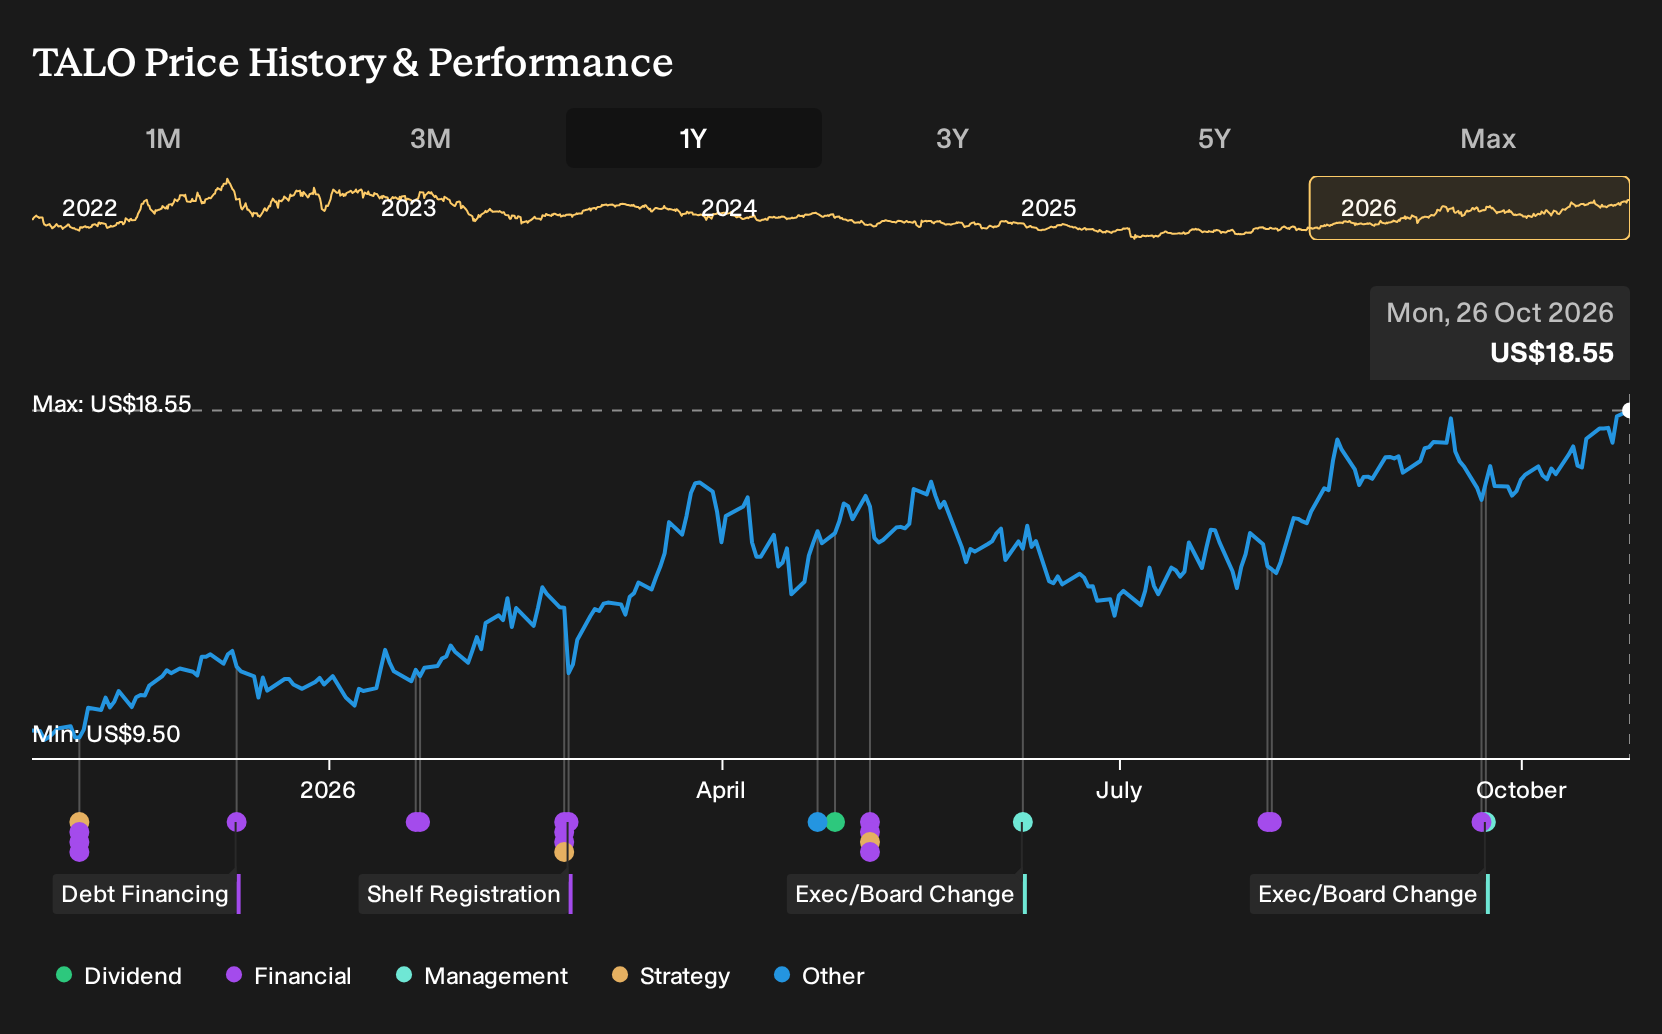
Exploring Other Perspectives
One alternate view leans hard into Talos Energy’s offshore expansion as a potential upside swing factor. Bullish analysts were penciling in about US$2.5b of revenue and US$376.8 million in earnings by 2029 before this latest upgrade, which is far more optimistic than consensus. Use that gap as a prompt to compare several narratives for yourself.
Explore 3 other Talos Energy fair value estimates, including one that suggests potential upside of as much as 421% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Talos Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Talos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Talos Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Talos Energy?
If the Talos Energy story has you thinking about where similar earnings or balance sheet profiles might show up next, cast the net wider using the Simply Wall St Screener. You can filter for cash flow quality, balance sheet strength, or income potential and quickly see which businesses line up with the kind of risk and reward mix you prefer.
- For investors who care most about financial resilience and debt levels, start with companies that pass our balance sheet filters using this list of solid balance sheet and fundamentals (24 results).
- If you want ideas that aim to pair quality fundamentals with attractive pricing, sort through companies that fit that profile using the 29 high quality undervalued stocks.
- Income focused investors can zero in on higher yielding opportunities by filtering for stocks with strong payout profiles through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com