


EN
Why CVR Energy (CVI) Shares Jumped And What Investors Are Weighing Now
CVR Energy (CVI) has drawn fresh attention after its stock closed at $62.02 on 26 October 2026, continuing its performance over the past month and past three months.
For context, CVR Energy’s share price has logged a 1-day move of 6.64% and a 30-day share price return of 20.38%, contributing to a year-to-date share price return of 146.21%, while the 1-year total shareholder return sits at 55.98%. This suggests that momentum has been strong, with earlier periods playing a bigger role in overall gains.
Compare CVR Energy’s surge with other hand picked US stocks showing strong recent price momentum by scanning the 29 high quality undervalued stocks, which also pair quality fundamentals with support from cash flows.
After a move like CVR Energy’s, the real tension is whether late buyers are taking on far more downside than upside. Do the current fundamentals still justify this price, or has the risk now shifted against new money?
Most Popular Narrative: 29% Overvalued
On the most followed valuation view, CVR Energy screens as expensive, with a fair value of $48 against the recent close at $62.02, so the story behind that gap matters a lot.
The main factor that has to go right is that CVR Energy contains rising RFS compliance and hedge losses that already consume more than twice all other refinery operating costs and have produced large realized and unrealized crack spread losses.
The current numbers, including sizable RIN expense, hedge losses and a modest recurring dividend, imply a share price that already reflects strong refining and fertilizer conditions while leaving limited room for setbacks, which supports a view that CVR Energy may be overvalued.
See why 6 investors see CVR Energy as 29% overvalued.
Result: Fair Value of $48 (OVERVALUED)
Still, two things could unsettle that overvaluation case: stronger than modeled free cash flow from CVR Energy and less severe RFS headwinds than recent quarters imply.
Find out about the key risks to this CVR Energy narrative.
Another View: Cash Flows Point the Other Way
While analyst targets suggest CVR Energy looks expensive at around $62, the SWS DCF model tells a very different story. In that framework, the estimated future cash flow value lands near $282 per share, which indicates very large potential upside. Which lens do you trust more when the signals clash this sharply?
For a closer look at how that cash flow estimate is built and what needs to go right for CVR Energy to justify it, Look into how the SWS DCF model arrives at its fair value.
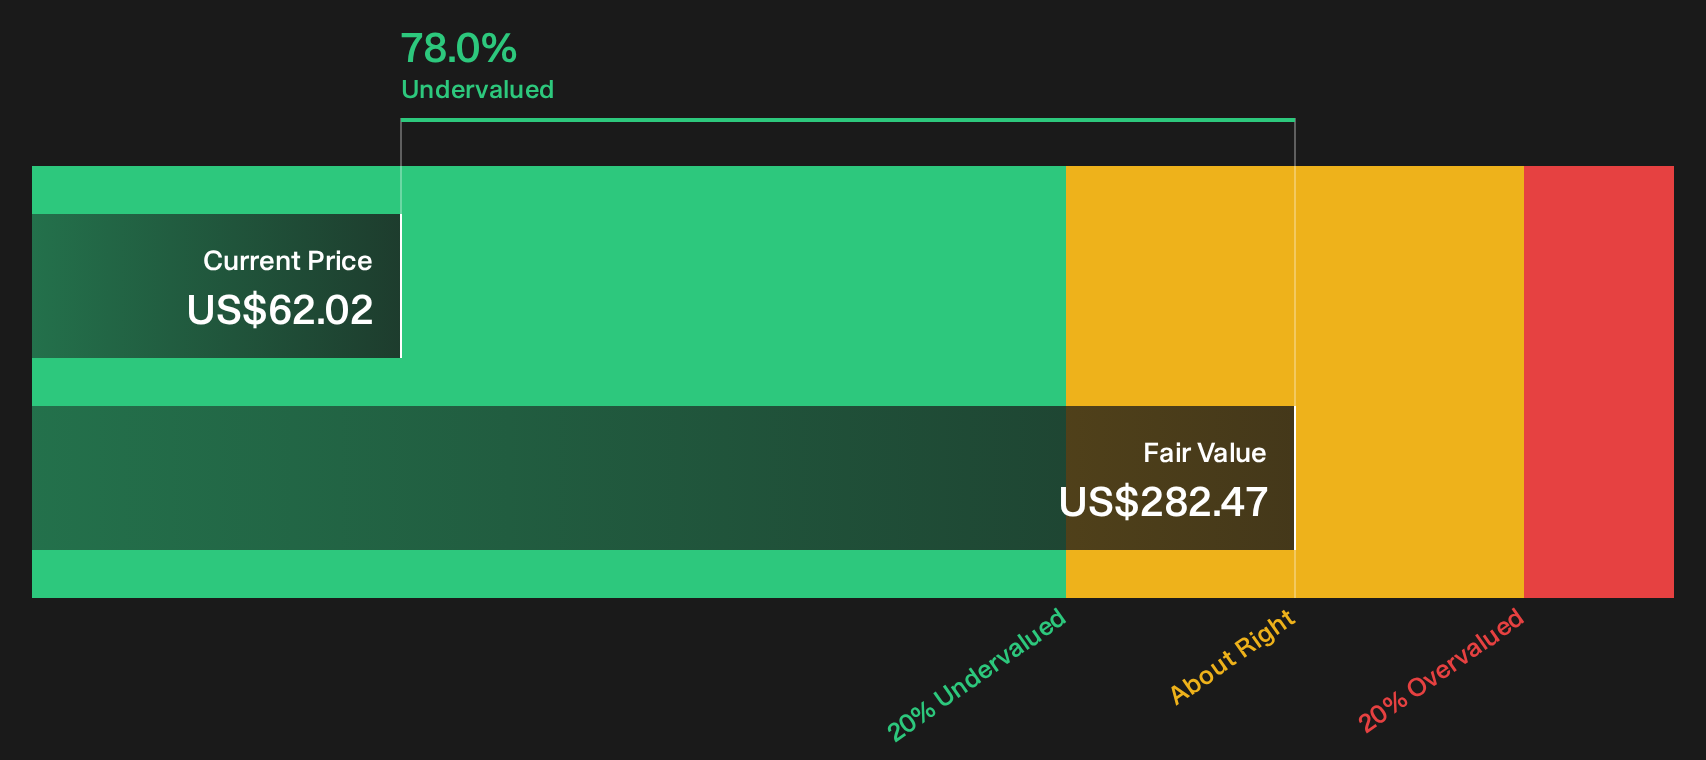
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CVR Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of concern and optimism around CVR Energy leaves you undecided, consider acting promptly and reviewing the numbers for yourself by weighing up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CVR Energy?
If CVR Energy has your attention, do not stop there. Broader context from other opportunities can help you build a stronger, more resilient portfolio.
- Target dependable income streams by reviewing 5 dividend fortresses and see which businesses currently offer higher yields with support from their underlying operations.
- Pursue quality at a sensible entry point through the 21 high quality undiscovered gems and spot companies with fundamentals that the market may not be fully pricing yet.
- Limit unnecessary shocks in your holdings by scanning the 30 resilient stocks with low risk scores so you can focus attention on businesses with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com