


EN
Blue Owl Capital (OWL) Faces Earnings And Dividend Pressure, Is The Stock Below Fair Value?
Blue Owl Capital (OWL) is back in focus after fresh research highlighted muted near-term earnings expectations, a negative Earnings ESP of 1.50%, and recent pressure from a reduced base dividend alongside rising non-accrual loans.
Recent price action reflects that tension between income concerns and earnings uncertainty. Blue Owl Capital’s share price has fallen sharply year to date with a share price return of 38.99% in the red, and the 1 year total shareholder return has declined 40.30%, while a 4.24% 7 day share price gain hints at short bursts of buying interest rather than a clear recovery trend.
Spot fresh ideas by comparing Blue Owl Capital's recent setback with a curated group of income alternatives in the 5 dividend fortresses that prioritize yield strength and payment resilience.Blue Owl Capital runs a sizeable alternative asset platform, yet the share price has been hit hard this year. After that kind of reset, is the quality of the franchise actually reflected in today’s valuation, or not?
Most Popular Narrative: 25% Undervalued
Blue Owl Capital last closed at $9.34, while the most followed narrative pegs fair value around $12.53, so the gap between price and that thesis is wide and hard to ignore.
Exceptional long term opportunities in digital infrastructure, including a more than 140 data center footprint with about 15 to 15.3 gigawatts of capacity, a pipeline of over US$100b and the planned seeding of a US$6.5b data center REIT, are creating avenues for additional fundraising and deployment that can lift management fee revenue.
See why 60 investors see Blue Owl Capital as 25% undervalued.
Result: Fair Value of $12.53 (UNDERVALUED)
Still, the bullish narrative around Blue Owl Capital can quickly be challenged if capped withdrawals in private credit persist, or if the investor lawsuit meaningfully curbs fundraising appetite.
Find out about the key risks to this Blue Owl Capital narrative.
Another View: Blue Owl Capital Looks Expensive On Earnings
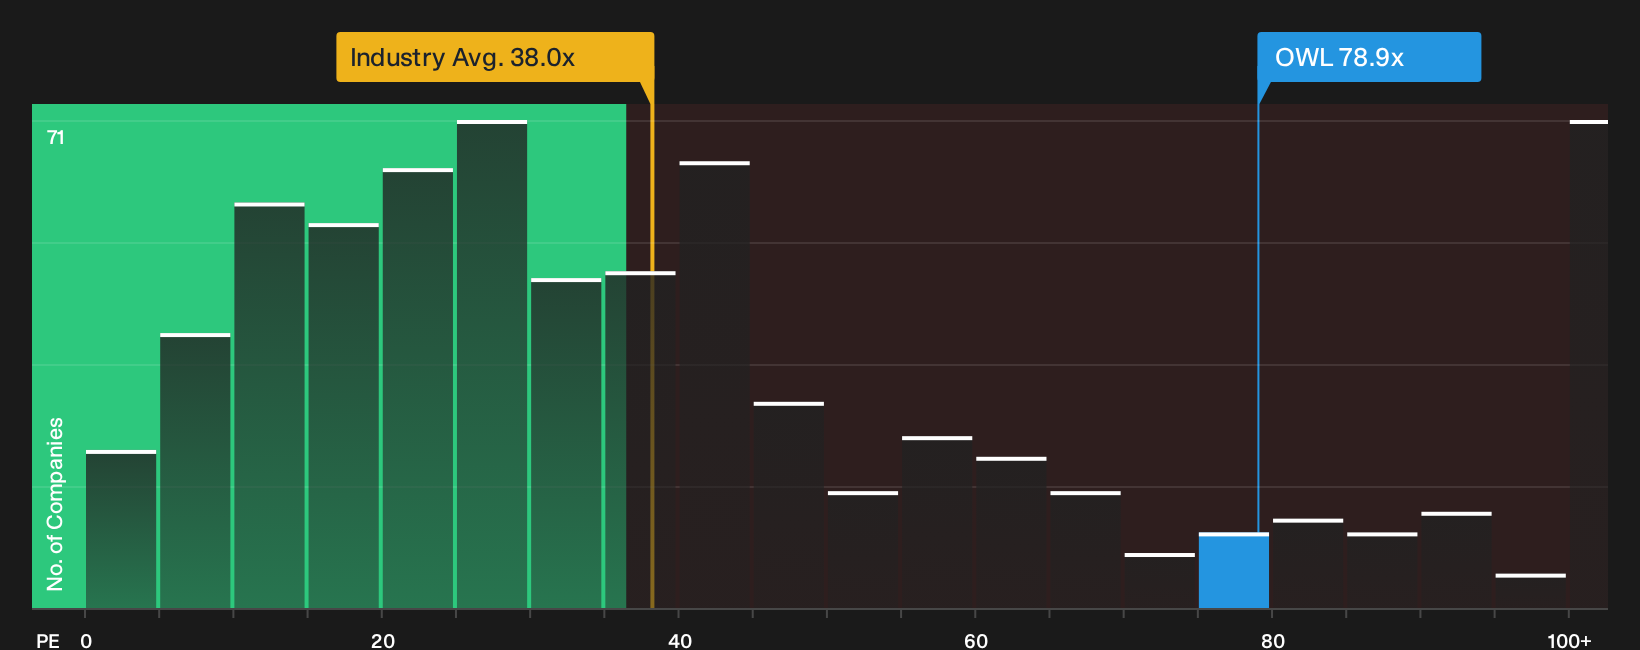
The popular Blue Owl Capital narrative leans on a fair value of $12.53, yet the current P/E of 78.9x tells a very different story. That ratio is more than double the US Capital Markets industry at 38x and far above the 18.3x fair ratio that our model suggests the market could move toward.
Compared with peers on 29.8x and a fair ratio of 18.3x, paying 78.9x earnings concentrates a lot of valuation risk in one number. The real question is whether investors are comfortable owning Blue Owl Capital if sentiment shifts back toward those lower multiples.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Blue Owl Capital's valuation and risk profile can feel confusing. Move fast, test the numbers yourself, and weigh both sides of the story with the 2 key rewards and 3 important warning signs.
Ready for more investment ideas beyond Blue Owl Capital?
Do not stop at one opportunity. Broaden your watchlist now so you are not looking back later wishing you had cast the net wider.
- Target resilient income by reviewing a carefully filtered group of yield focused candidates in the 5 dividend fortresses.
- Hunt for pricing gaps by scanning companies the market may be overlooking with the 29 high quality undervalued stocks.
- Prioritise strength and durability by focusing on financially sturdy businesses through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com