


EN
ASML (ASML) Stock Looks About Right On Its 176% Run
ASML Holding has rewarded long-term holders with strong gains, and that kind of track record naturally raises a blunt question for you as an investor. Is the current share price, at around US$1,590.90 at the last close, still in step with what the company is earning today and expected to earn in the years ahead.
- Over the past 3 years the stock has returned 176.2%, which puts a lot of weight on the idea that ASML's earnings power can support a much higher valuation than in the past.
- The company has flagged potential equipment shortages through 2028 and plans to raise prices from 2027, which can support expectations for stronger earnings but also concentrates more of the valuation case on how much profit that extra demand actually brings in.
- There is a second opinion on ASML Holding worth weighing. See what analysts think ASML Holding's shares could be worth.
The issue now is whether ASML Holding's current market value is justified by its earnings when you line it up against the Fair Ratio benchmark.
If you are weighing whether ASML Holding’s recent 176.2% three year return still lines up with its earnings power, it can help to compare that story with 55 AI infrastructure stocks.
Does ASML Holding Look Fairly Valued on Earnings?
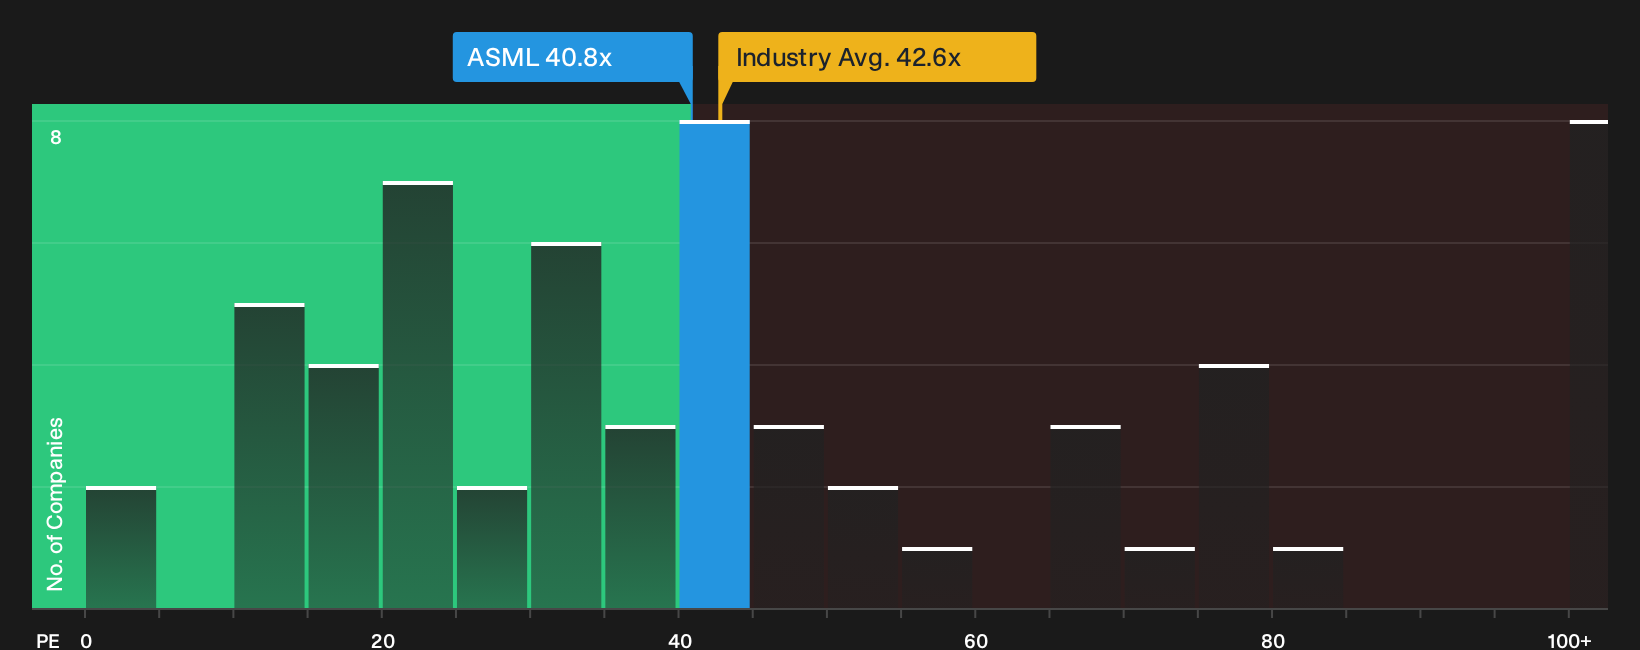
The P/E ratio works well for ASML Holding because earnings are the core driver people are paying up for today. On this lens, the stock trades on about 40.8x earnings, which is slightly above the 37.7x peer average and a little below the wider semiconductor sector on 42.6x. That keeps ASML in the same broad valuation zone as other large chip equipment makers rather than at a steep premium or bargain.
A Fair Ratio model that ties the P/E you might expect to factors like ASML Holding’s margins, growth profile, size and risk puts the current multiple very close to that implied level. Because the firm is warning of potential equipment shortages through 2028 and talking about price increases from 2027, the market already prices in strong expectations and leaves less room for disappointment than a low-teens P/E would. The key question for you is whether that roughly in line earnings multiple still feels acceptable once you weigh how much future demand is already embedded in the price. Explore the numbers behind ASML Holding's P/E valuation.
The ASML Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ASML Holding pick up where the valuation puzzle leaves off and explain which views on future growth, margins and earnings would need to occur for the stock to appear meaningfully more expensive or cheaper than today’s price. Each narrative links its number to a clear view on how ASML Holding's growth profile, profitability and risk picture could change, giving you something specific to revisit as new information appears on the Community page.
One of the top community narratives on ASML Holding: 12% undervalued
"ASML builds the lithography machines that print circuit patterns onto silicon wafers, the most critical and most expensive step in chipmaking..."
Discover why this Narrative puts ASML Holding at 12% undervalued.
One more ASML Holding check that belongs next to the valuation work
Price tags get the spotlight, but the people setting ASML Holding’s priorities, incentives and pay structures can shape how that valuation story actually plays out over time. See who runs ASML Holding and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com