


EN
EMCOR Group (EME) Stock Still Looks Reasonable As Earnings Stay In Focus
EMCOR Group has delivered very strong long term returns, and the recent pullback puts a fresh spotlight on whether the current share price lines up with what its earnings can support. With that kind of history in the rear-view mirror, the question now is how much of the business performance is already baked into today’s valuation.
- Over the past 5 years, EMCOR Group has returned about 449.3%, which puts a lot of pressure on its earnings profile to justify where the stock trades now.
- The business relies heavily on converting project work into consistent profit, so the stability of its margins and cash generation can be critical for how investors think about its earnings power over time.
- There is a second opinion on EMCOR Group worth weighing. See what analysts think EMCOR Group's shares could be worth.
The issue now is whether EMCOR Group's current price is appropriately supported by the earnings it is generating today and is expected to produce in the future.
If you are questioning whether EMCOR Group's strong 5 year return still lines up with its earnings, it can help to compare it with other companies in the 29 high quality undervalued stocks.
Does EMCOR Group Look Undervalued on Earnings?
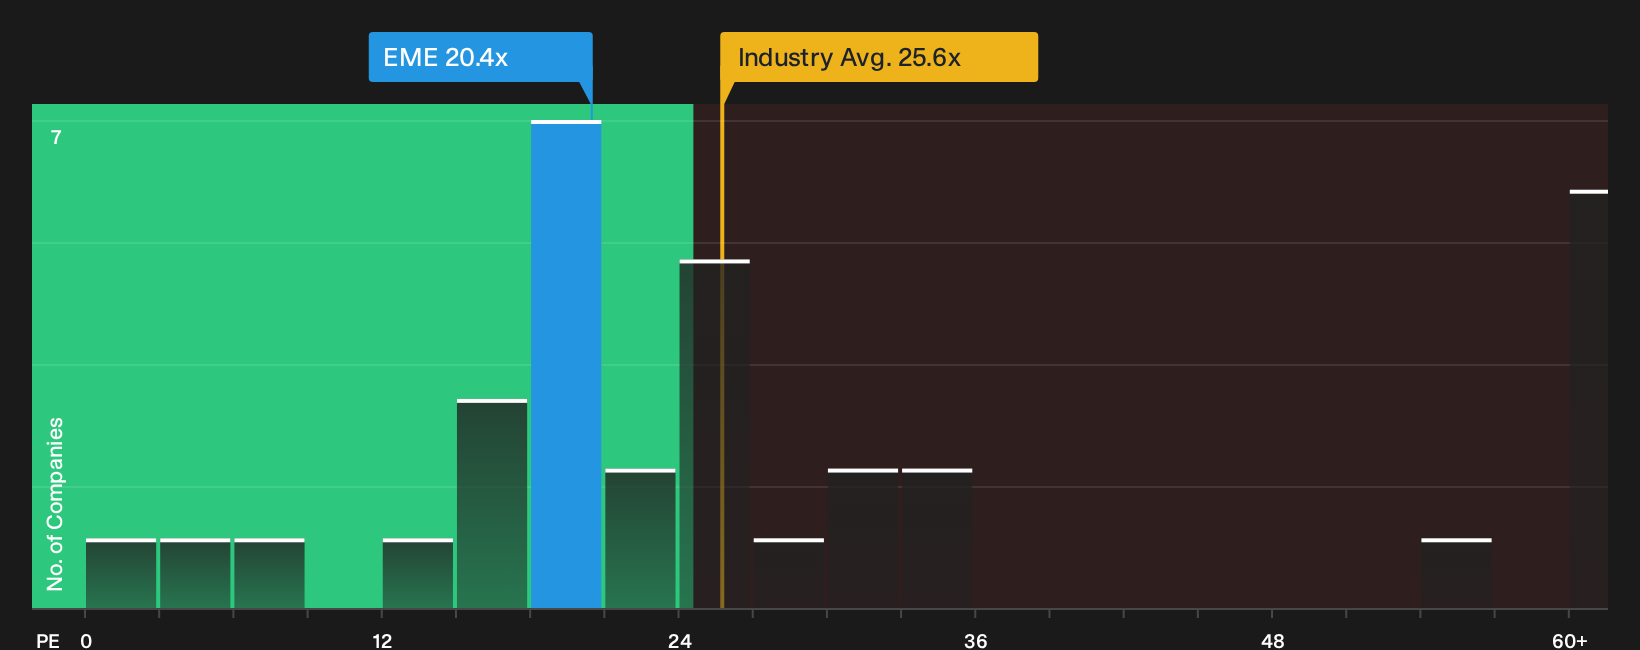
The P/E ratio suits EMCOR Group because earnings quality matters a lot for a project driven contractor. On this measure, the shares trade at about 20.4x earnings, which sits below the Construction industry average of roughly 25.6x and also under the broader peer group on around 35.9x. For a business that converts contracts into profit, that kind of gap suggests investors are not paying the same headline premium that many similar stocks command.
The Fair Ratio, which blends the firm’s growth profile, profitability, sector and risk into a more tailored benchmark, points to EMCOR Group trading below the level you might expect on this framework. That discount hints that the current valuation leaves room for investors to weigh whether the earnings base and cash generation justify a higher multiple over time, or whether the lower P/E simply reflects perceived execution or cycle risk that the market wants to price in. Explore the numbers behind EMCOR Group's P/E valuation.
The EMCOR Group Narrative: What Would Justify Today's Price?
Narratives on EMCOR Group pick up where the valuation questions leave off by explaining which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today, and they sit on Simply Wall St's Community page. Rather than a single P/E or model output, each narrative sets out the assumptions behind its view of fair value so you can compare those expectations with future results as they are reported.
One of the top community narratives on EMCOR Group: 32% undervalued
"The numbers imply that EMCOR Group’s share price reflects scepticism about how durable the current AI data center and high-tech manufacturing cycle will be..."
Discover why this Narrative puts EMCOR Group at 32% undervalued.
One more piece of EMCOR Group's puzzle is still off the page
Numbers only tell part of EMCOR Group's story, because the people choosing projects, setting priorities and rewarding themselves can shape how those earnings are built and shared over time. See who runs EMCOR Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com