


EN
Is Lower Earnings Forecast Altering The Investment Case For Weyerhaeuser Stock (WY)?
- Weyerhaeuser is projected to report quarterly earnings of US$0.05 per share for the September 2026 period, with revenue forecast to grow 6.3% compared with the same quarter a year earlier.
- The unusual combination of lower expected earnings per share and higher anticipated sales highlights pressure on Weyerhaeuser’s profitability, even as demand supports the top line.
- We will assess how Weyerhaeuser's investment narrative holds up as earnings expectations reset lower, despite forecasts for modest revenue growth.
Compare Weyerhaeuser’s reset earnings outlook with a curated group of companies where analysts expect stronger profit traction and solid fundamentals using the 29 high quality undervalued stocks.
Weyerhaeuser Investment Narrative Recap
To own Weyerhaeuser, you need to believe its timber base and newer climate and energy ventures can support resilient cash generation through cycles. The latest expectation reset, with quarterly EPS projected at US$0.05 alongside 6.3% revenue growth, points to pressure on near term profitability but not a broken business model.
The key near term catalyst remains execution on higher margin wood products and fee based climate projects while keeping leverage in check. OSB weakness, softer housing activity and net debt around 5x EBITDA already sit on the risk list, and the lower earnings outlook mostly reinforces rather than changes that focus.
In this earnings context, the Monticello TimberStrand mill in Arkansas looks central. Management still plans roughly US$300 million of capex there, within a broader US$500 million project that is expected to reach more than US$100 million of annual EBITDA at full run rate after a planned first half 2027 start up.
For you, that project sits at the intersection of opportunity and strain. It points to a potential future mix shift toward higher margin engineered products while OSB and traditional lumber face pressure. At the same time, any further earnings softness, like the current EPS reset, can make funding that build while servicing interest and maintaining the dividend more demanding.
Analysts frame Weyerhaeuser's set up around revenues forecast at US$8.4b and earnings projected at US$631.3m by 2029, based on a 6.9% yearly revenue growth rate and an earnings increase of about US$159.3m from current earnings of US$472.0m.
Uncover why Weyerhaeuser's fair value indicates a 40% potential upside to its current price before that valuation gap starts to close.
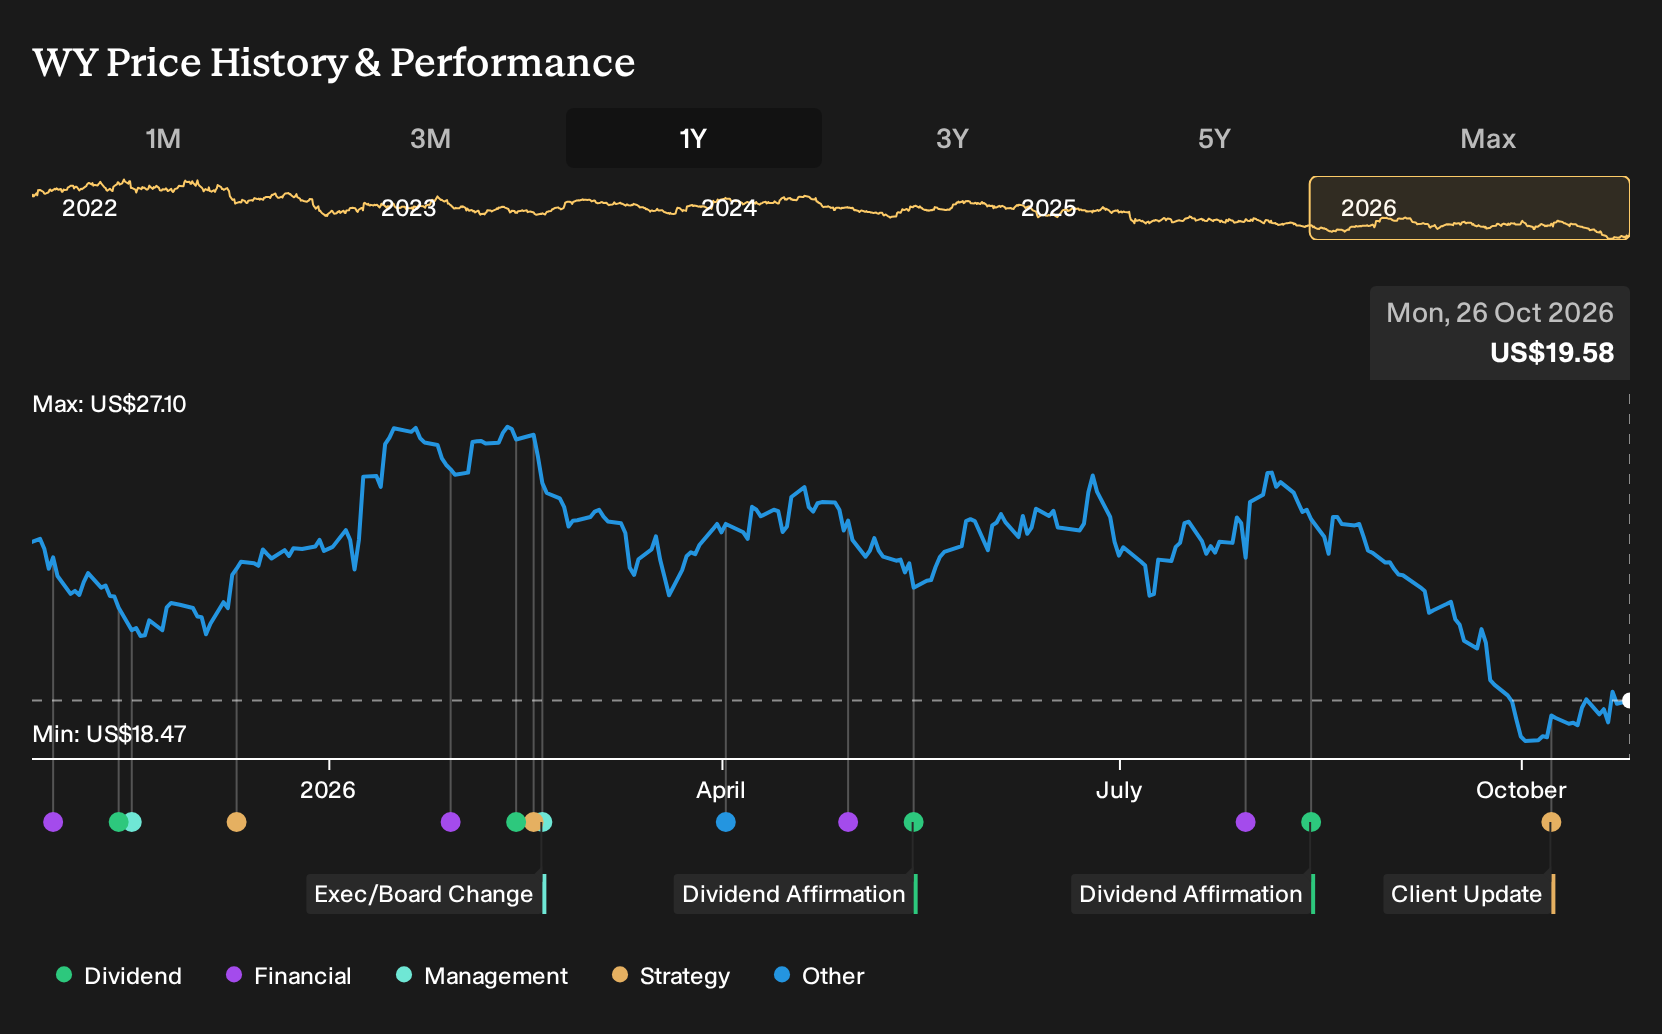
Exploring Other Perspectives
The lowest analysts focus on housing volume as the swing factor for Weyerhaeuser. Before this earnings reset, they were pencilling in roughly US$8.0b of 2029 revenue and US$707.3m of earnings. That is actually more optimistic on profits than consensus, which shows how far views can stretch. Use this surprise to test which story you trust more.
Explore 3 other Weyerhaeuser fair value estimates, including one that suggests it could be worth just $27.36!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Weyerhaeuser research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Weyerhaeuser. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weyerhaeuser's overall financial health at a glance.
Looking For More Investment Ideas Beyond Weyerhaeuser?
If Weyerhaeuser’s setup has you reassessing where you want exposure, it can help to line it up against other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals on their side, compare Weyerhaeuser with a curated pool of companies flagged as 29 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, weigh this timber REIT against a list of solid balance sheet and fundamentals (24 results) that prioritises staying power over excitement.
- When you are hunting for ideas that the market may not be paying full attention to yet, broaden your watchlist with a set of 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com