


EN
Could Earnings Optimism Alter The Investment Case For Clorox Stock?
- Clorox is set to report its September 2026 quarter on November 2, with Wall Street projecting higher earnings and revenue than the same period a year earlier.
- Behind those expectations is a business under pressure to rebuild margins, manage cost inflation and convert its health and hygiene focus into consistent profitability.
- This article examines how Clorox's investment narrative could be influenced by rising earnings expectations ahead of its upcoming quarterly report.
See how Clorox's earnings reset compares with other consumer staples under pressure by reviewing our curated list of 30 resilient stocks with low risk scores.
Clorox Investment Narrative Recap
To own Clorox, you need to believe the health and hygiene focus, including GOJO and Clorox Healthcare, can translate into steadier earnings despite sluggish category growth and value seeking shoppers. The key near term swing factor is whether upcoming quarters show tangible progress on rebuilding margins while protecting volumes across club, mass, and e commerce channels.
The biggest risk is that input and logistics costs, guided at a little over US$200 million of inflation in fiscal 2027, outpace savings from the ERP rollout and productivity programs. The November earnings report may be a check in on that margin rebuilding story but, on its own, is unlikely to resolve the longer term cost and dividend coverage questions.
With no fresh corporate announcements tied directly to this November earnings date, the most relevant backdrop is still Clorox's ongoing ERP transition. Management previously framed the shift from stabilization to optimization as a route to better order fulfillment, leaner inventories, and more automated back office processes that could support margins over time.
For you as a shareholder, the link to the current earnings setup is straightforward. Any evidence that the ERP platform is now improving service levels and cutting waste would speak to the same catalysts analysts have highlighted, such as SG&A productivity and the integration of GOJO into the broader professional portfolio, while also testing whether those benefits can offset higher costs and a stretched dividend payout.
What Current Earnings Expectations Assume For Clorox
Clorox's narrative projects US$8.1b revenue and US$789.0 million earnings by 2029. Analysts link this to a 6.3% yearly revenue growth rate and an earnings increase of about US$202.0 million from US$587.0 million today.
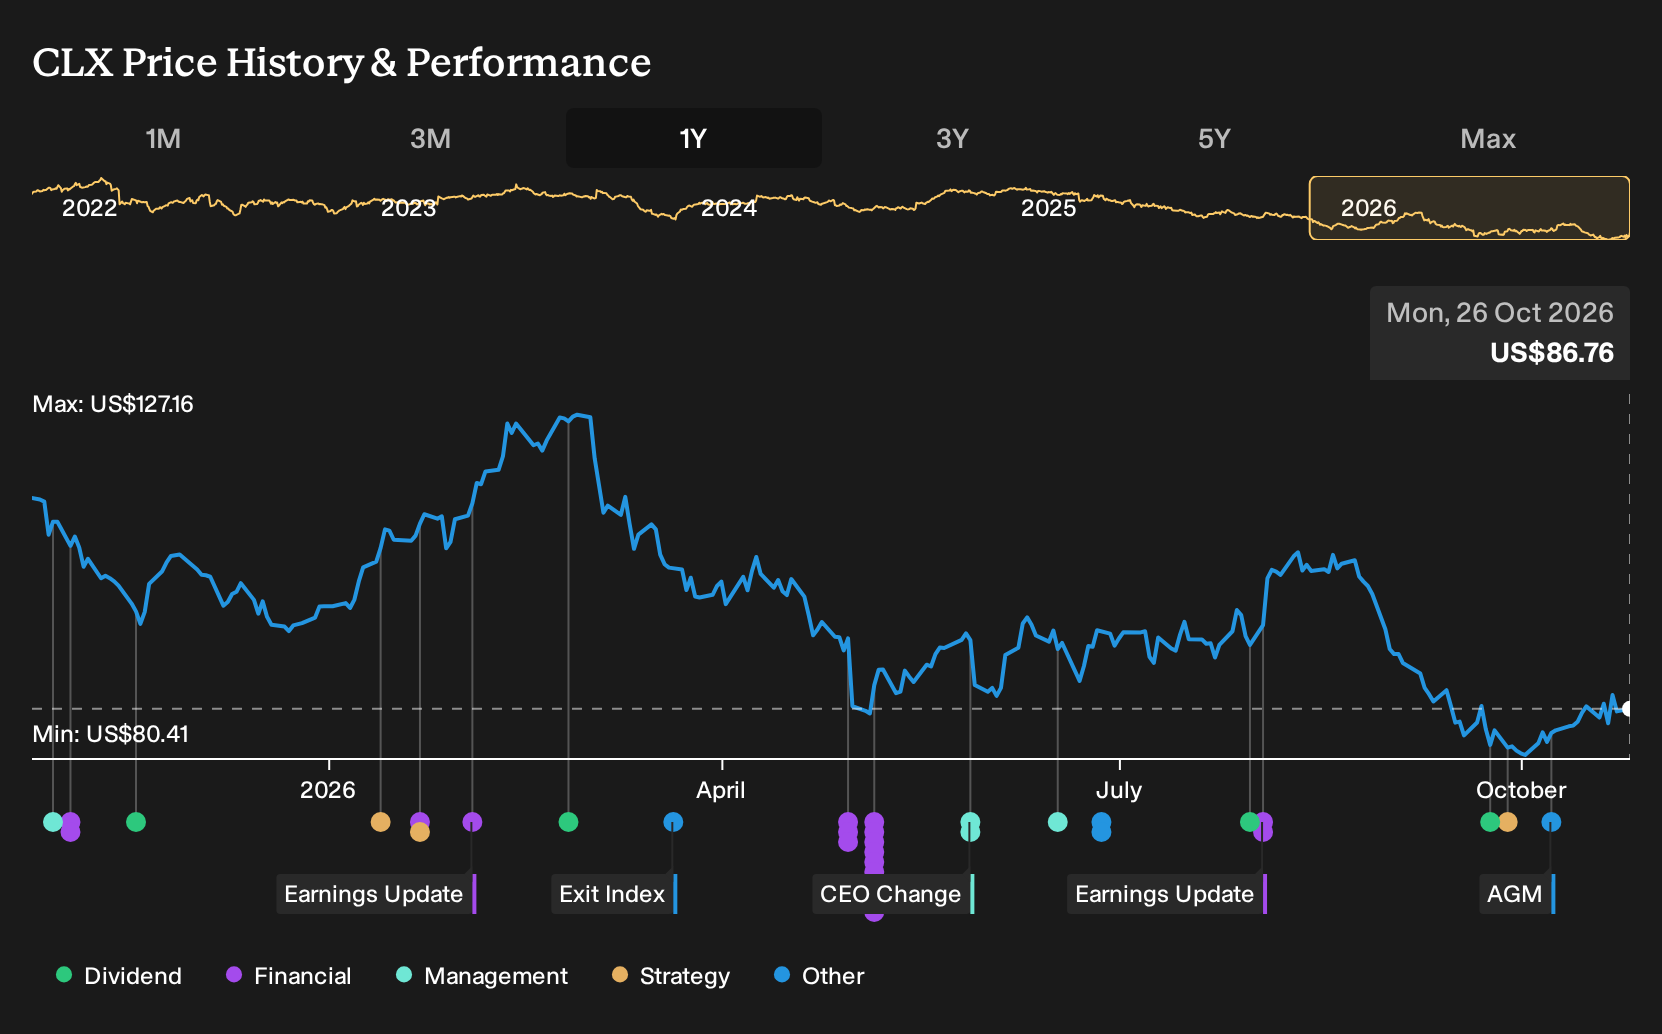
Discover how Clorox's fair value reflects a 12% potential upside to its current price before other investors narrow that gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into the recurring dispenser story at Clorox. Before this earnings news, that group was modeling about US$8.3b of revenue and roughly US$905.6 million of earnings by 2029, well above consensus. You can treat this report as a live test of those bullish assumptions and explore which narrative you find more convincing.
Explore 6 other Clorox fair value estimates, including one that suggests potential upside of as much as 174% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Clorox research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Clorox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Clorox's overall financial health at a glance.
Looking For More Investment Ideas Beyond Clorox?
Once you have formed a view on Clorox, it can help to put that thesis in context by comparing it with other companies that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener is built for exactly that kind of cross check.
- If you want income to play a bigger role in your portfolio, scan for higher yielding opportunities through 5 dividend fortresses and see how they stack up against Clorox's payout.
- For investors who care most about balance sheet strength, broaden your watchlist with a list of solid balance sheet and fundamentals (24 results) that may hold up better when conditions get tougher.
- If you are hunting for mispriced opportunities based on quality and value, use a 29 high quality undervalued stocks to see where the current market view might differ from fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com