


EN
Galp (ENXTLS:GALP) Stock Price Meets Q3 Earnings And Margin Pressure
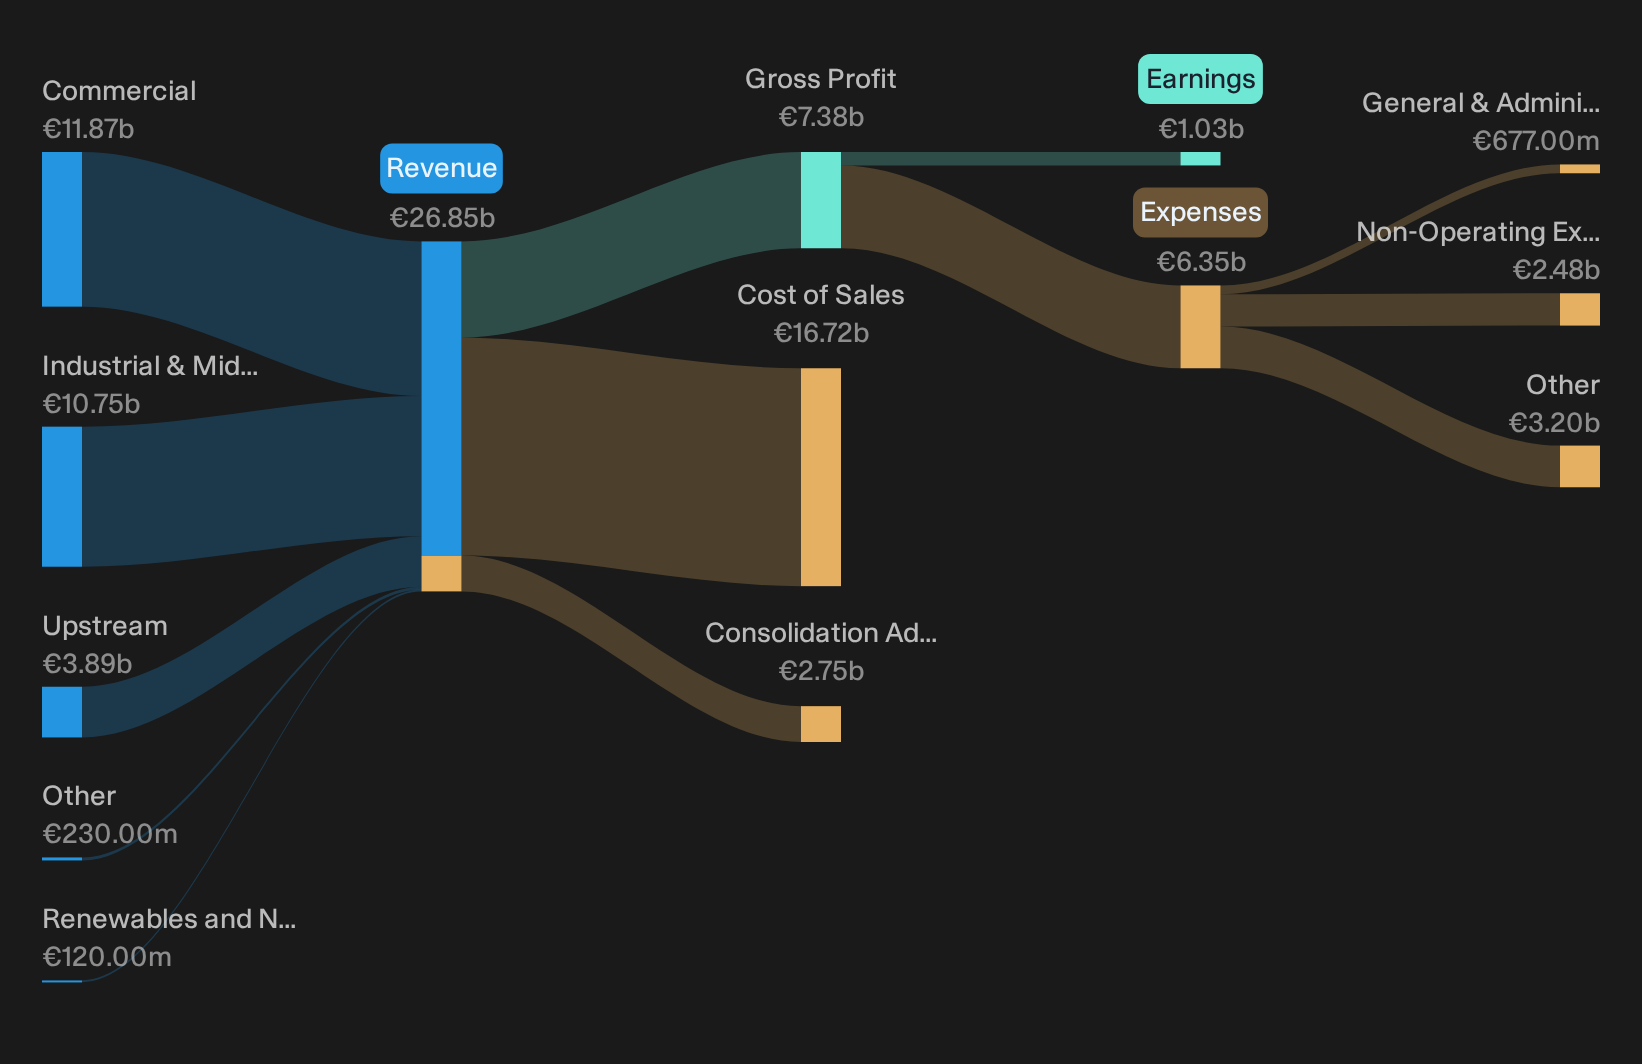
Galp Energia SGPS just reported Q3 2026 with revenue of €7,693m and net income of €201m. Despite that, the stock has been moving lower, down about 9% over the past month and 8.6% over the past week into this release. That disconnect highlights a clear sentiment clash, with traders leaning cautious while the latest quarter points to a different picture.
The central issue for this earnings season is profitability. Trailing net margin stands at 4.3%, compared with 4.9% a year earlier, and that pressure is where sentiment and fundamentals intersect for Galp today.
Investors may appreciate Galp Energia SGPS’s latest quarter but feel uneasy about the pressure on profitability. Explore a curated set of resilient balance sheet plays in the list of solid balance sheet and fundamentals stocks (207 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €7,693m vs. €5,098m (change reflects a higher reported top line)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): €201m vs. €264m (decline in reported earnings)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.28 vs. €0.36 (lower earnings per share)
- Trailing Twelve Month Net Margin (Latest vs. Prior Year): 4.3% vs. 4.9% (margin compression on a trailing basis)
Earnings are one thing, but investors who care about what they are paying for Galp Energia SGPS often focus more on the cash coming in and out of the business. Looking at Galp Energia SGPS' cash flows alone, the stock could be a dramatic 33% undervalued.
Galp Bull Case Hinges On Execution Milestones
The optimistic view on Galp Energia SGPS leans heavily on upstream delivery and low carbon build out actually turning into steadier earnings.
"Ramp up of the Bacalhau FPSO, described as one of the largest and most efficient oil production units in operation, has the potential to lift upstream volumes and operating efficiency, which can feed directly into higher EBITDA and operating cash flow."
Q3 points to this milestone being hit in operational terms. Management reports Bacalhau already touching peak production on several days and has lifted full year guidance to about €5.0b EBITDA and €3.9b operating cash flow. That is presented as evidence that this part of the bullish script is translating into reported numbers, even as net margin pressure keeps the headline profit picture mixed.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Galp Bear Case: Execution Risk Still On The Table
Bearish investors worry that Galp Energia SGPS is leaning too hard on complex offshore growth, where delays or setbacks could quietly erode the current story.
"The focus on large offshore oil projects such as Bacalhau and Mopane concentrates future growth on capital intensive assets. These assets may face higher regulatory, cost, and execution risks, which could pressure future earnings if ramp up or partnership plans slip versus expectations."
Bacalhau hitting peak days and Mopane progressing under a carry reduce near term project strain, yet key milestones remain open. Mopane still awaits appraisal results and future farm down clarity. The Mozambique tax dispute also keeps legal and cash timing risk unresolved, so execution concerns are not fully disproved by this quarter.
Hunt For Mispriced Earnings Power
Galp Energia SGPS just showed how sentiment can diverge significantly from reported profitability. The real opportunity could sit in companies where fundamentals and market pricing still look out of sync.
- Company 1 - 30% below our estimate - leans on compact supermarkets and online ordering to stretch each new store’s return despite softer consumer demand and currency pressures.
- Company 2 - 23% below our estimate - turns a thick defense order book for unmanned naval systems into scale as it integrates more tightly with a larger industry partner.
- Company 3 - 31% below our estimate - shifts production toward higher margin nutrition and defense compounds as new plants come online to replace weaker agricultural and commodity volumes.
That is three of the list. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com