


EN
Missed Chubb's Gain? Here's What Holders Had To Believe
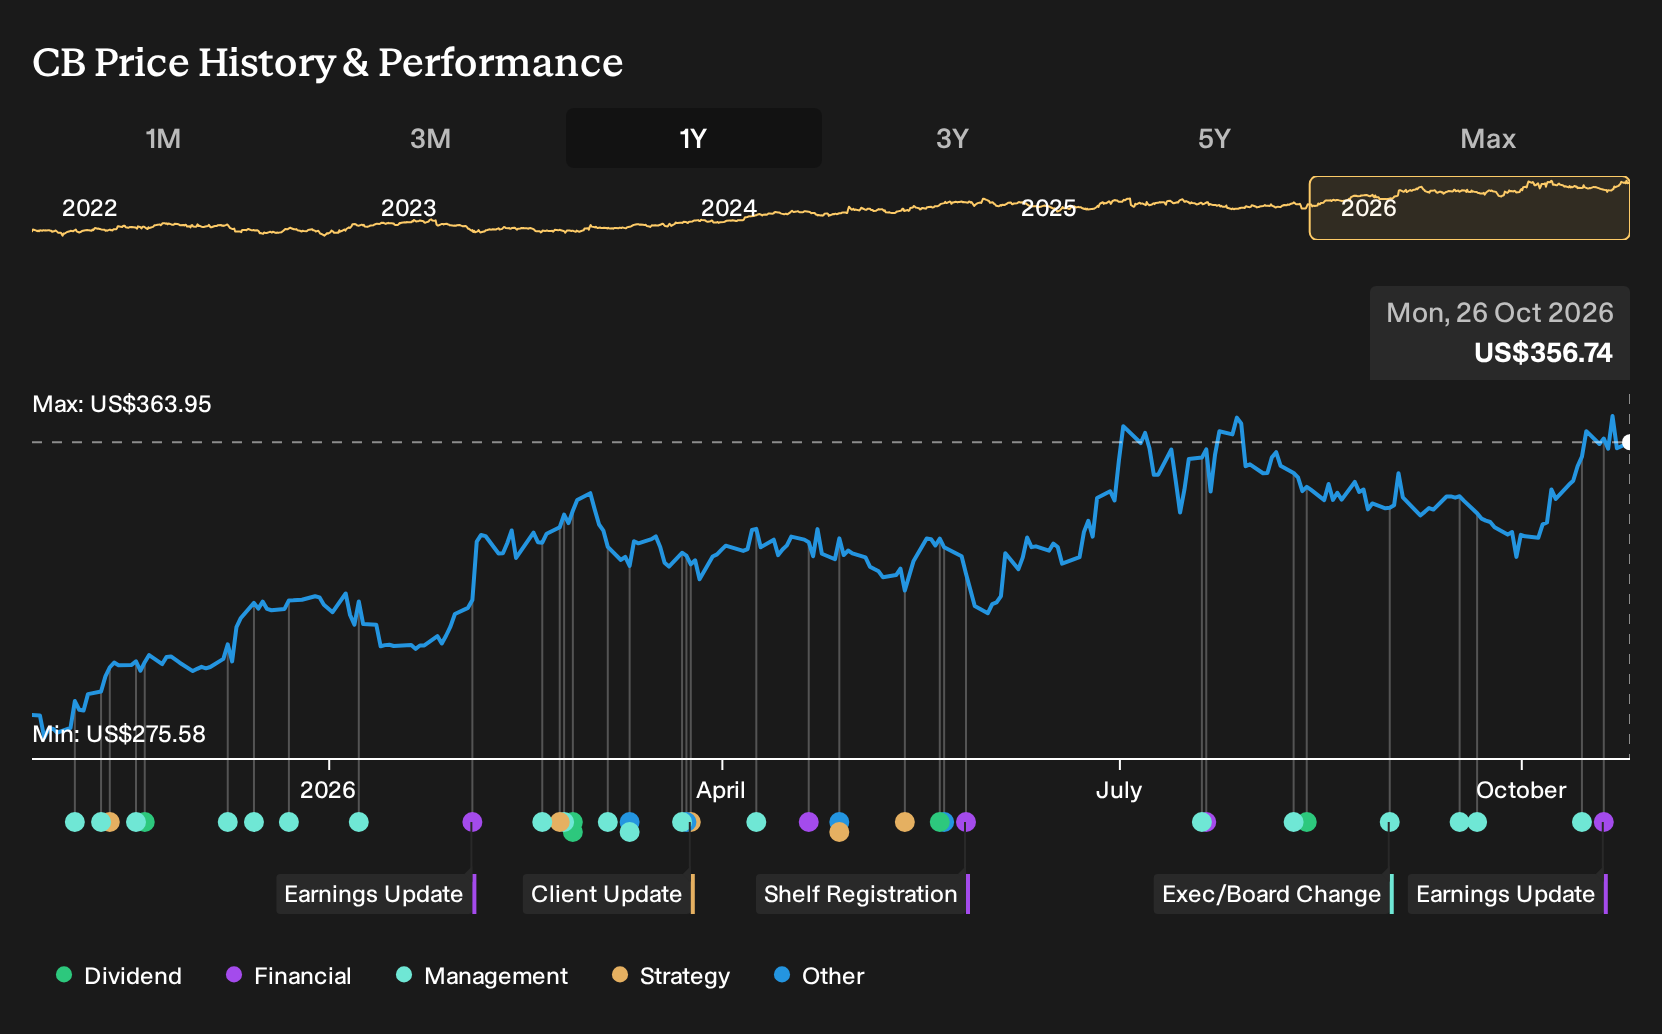
If you only glanced at the headlines about catastrophe exposure, war risk cover in the Strait of Hormuz, and mixed analyst views on Chubb, you might have expected a bumpier ride. For Chubb shareholders, the return over the past year was 28.2%, including dividends. If you had been weighing the bullish digital expansion and buyback story against the more cautious 5 year bear case in October 2025, what exactly tipped the odds in your decision framework?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Chubb harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Chubb Narratives Investors Were Arguing About
The shares cost US$282 at the start of the period, so any thesis on Chubb had to answer whether that was above or below a sensible anchor.
The bullish narrative put fair value at US$300, arguing that international expansion and digital distribution could support earnings, helped by active share repurchases and a new US$5b authorization.
The bearish view set fair value at US$247, assuming revenue growth of 2.5% and a future P/E of 11.6x. It also emphasized pressure from intense global competition in property and casualty insurance.
What The Results Changed In The Chubb Argument
The clearest development was Chubb’s Q3 2026 report, where revenue reached US$16,472m and net income was US$2,844m, with net margin at 17.3%. That outcome leaned toward the bullish view that underwriting discipline and diversification could support profitability, although it was only marginally above the bear case margin assumption of 17.9% over five years, so the evidence cut both ways.
The episode turned on one assumption: Could Chubb convert its digital and international expansion story into sustained profitability without giving up margin? When you test another insurer, line that claim up against the reported net margin trend and the combined ratio through several quarters, not just headline revenue growth.
What Chubb's Price Seems To Be Asking Now
Chubb now trades at US$357, with the share price well ahead of where last year’s argument started. The business itself has moved more slowly, with total revenue shifting from US$16,263m in Q3 2025 to US$16,472m in Q3 2026 and net income edging from US$2,801m to US$2,844m.
Profitability barely changed, as net margin moved from 17.2% to 17.3%. The key question is whether that modest lift can justify today’s richer tag. The valuation tool can help you test this against your own assumptions on future earnings resilience.
We value every stock in the world, every day. See what our valuation says Chubb is worth now.
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 32% below our estimate - sells high margin AI chips and software for data centre infrastructure.
- Company 2 - 37% below our estimate - wins specialised consulting mandates requiring integrated technical, regulatory and legal expertise.
- Company 3 - 48% below our estimate - converts complex technology focused construction projects into ongoing mechanical and monitoring contracts.
Those are three of them. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com