


EN
NVR (NVR) Stock Dropped, So What Is Driving Attention Now?
Earnings event puts NVR under closer scrutiny
NVR (NVR) is back in focus after reporting third quarter and nine-month 2026 results that showed lower net income and earnings per share compared with the same periods a year earlier.
The latest earnings miss comes alongside a weak price chart, with NVR’s share price down 4.3% over the last day and about 9.1% over the past month. This has contributed to a year-to-date share price decline of 21.3% and a 1-year total shareholder return fall of 23%. These results contrast with still positive 3- and 5-year total shareholder returns of 6% and 16.2%, suggesting recent momentum has faded even though longer-term holders remain in positive territory.
Scan how other housing and construction plays are reacting to similar earnings pressure by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
The question now is timing. After NVR’s sharp pullback and weaker earnings, does it make more sense to step in at this level or wait for an even cheaper entry as the valuation picture comes into focus next?
Most Popular Narrative: 52% Overvalued
NVR last closed at $5,727.77, while the leading narrative on Simply Wall St, according to Esteban, places fair value closer to $3,758 per share. That gap has become a focal point after the latest earnings wobble and recent share price weakness.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model: NVR pays non-refundable deposits of approximately 10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land, NVR redeploys into share buybacks. The risk that peers absorb in housing downturns, NVR walks away from by forfeiting deposits.
See why 6 investors see NVR as 52% overvalued.
Result: Fair Value of $3,758 (OVERVALUED)
Still, the NVR story could be knocked off course if housing demand weakens further or if the lot option model encounters tougher financing or regulatory conditions.
Find out about the key risks to this NVR narrative.
Another view on NVR’s valuation
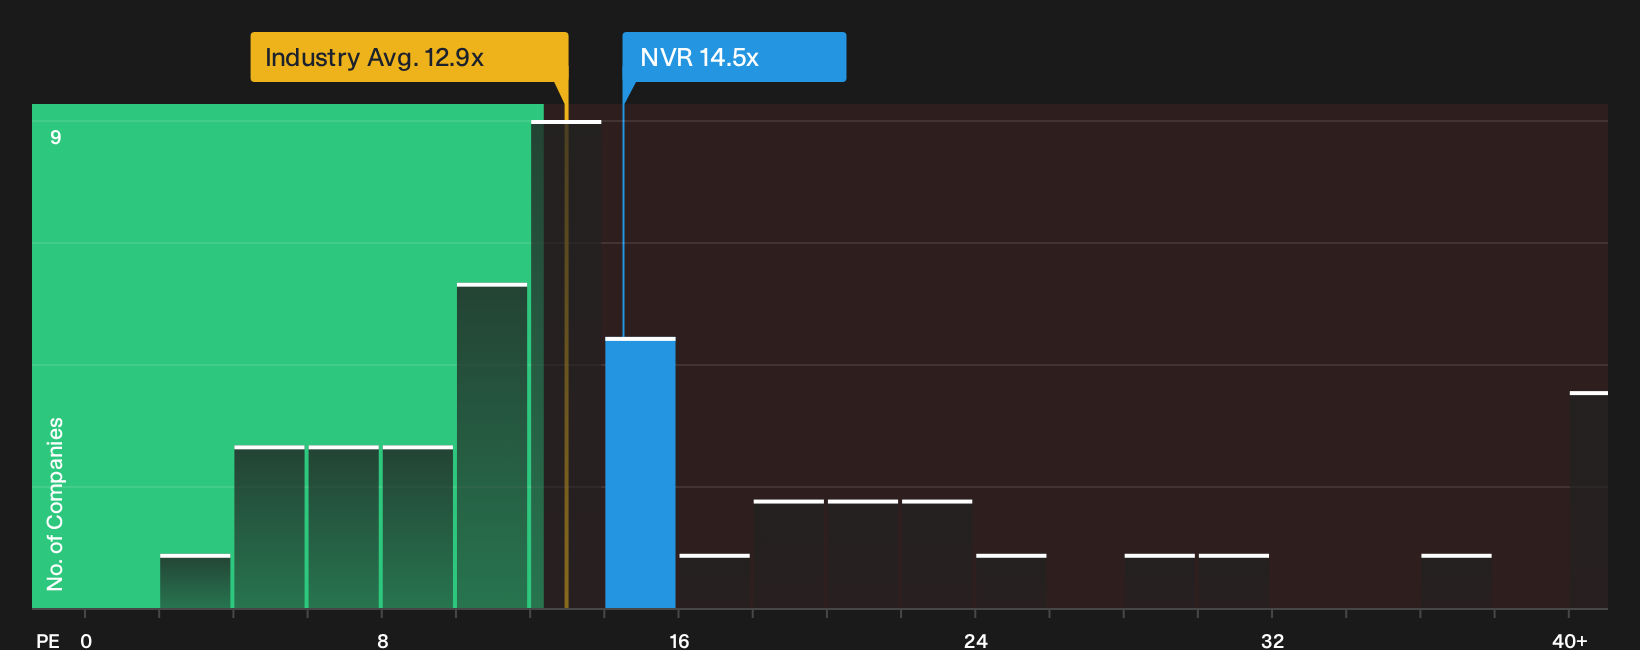
Esteban’s fair value of $3,758 frames NVR as 52% overvalued, yet the simple multiples tell a softer story. The P/E of 14.5x sits slightly above both peers and the Consumer Durables group at 13x, while the fair ratio of 15.2x implies only a modest valuation gap. Which signal do you trust more when the numbers disagree?
For a closer read on what this pricing gap might mean in practice, including how the market could move toward that fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around NVR leaves you on the fence, use the data to form your own stance while sentiment is still shifting. To see what optimism is already priced in, review the 1 key reward.
Looking for more investment ideas beyond NVR?
Do not stop with NVR. Broaden your watchlist now while valuations, quality and income potential across the market still look very different from one company to the next.
- Target stronger quality at a discount by scanning companies that appear mispriced on fundamentals through the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on higher yielding opportunities using the 5 dividend fortresses.
- Prioritize resilience and capital protection by zeroing in on companies highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com