


EN
Halozyme Therapeutics (HALO) Could Be 16% Below Fair Value After Royalty Fueled Growth
Halozyme Therapeutics (HALO) moved into focus after strong royalty streams and the scaling of new subcutaneous therapies helped drive what investors viewed as robust recent operating performance and ongoing revenue momentum.
That operating backdrop has shown up in the chart. Halozyme Therapeutics’ share price has climbed 12.39% over the past month and 53.41% across 90 days, contributing to an 82.07% year to date share price return and a 276.50% three year total shareholder return, which reflects a period of strong positive momentum.
Scan beyond Halozyme Therapeutics and review royalty-rich healthcare players showing similar momentum with a curated set of 34 healthcare AI stocks
Halozyme Therapeutics now has a sharply higher share price and a royalty engine that many investors view as strong. The key tension is whether that quality is already fully reflected in today’s valuation.
Most Popular Narrative: 16% Undervalued
Halozyme Therapeutics last closed at $128.01, while the most followed narrative pegs fair value at $151.83. As a result, sentiment on the stock leans toward a material discount that hinges on the long runway for its royalty platforms.
Most investors view Halozyme Therapeutics through a single lens: ENHANZE®. That perception made sense several years ago, when ENHANZE® was the company's primary growth engine and the overwhelming source of value. Today, however, management's vision appears far broader. Halozyme is no longer building around one platform. It is attempting to create a portfolio of drug-delivery technologies that could eventually support multiple royalty streams across different therapeutic modalities.
See why 3 investors see Halozyme Therapeutics as 16% undervalued.
Result: Fair Value of $151.83 (UNDERVALUED)
Still, Halozyme Therapeutics carries clear pressure points, including execution risk around newer platforms like Hypercon and Aerocon, as well as any reset to management’s long-term royalty ambitions.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View: Halozyme Therapeutics Through Earnings Ratios
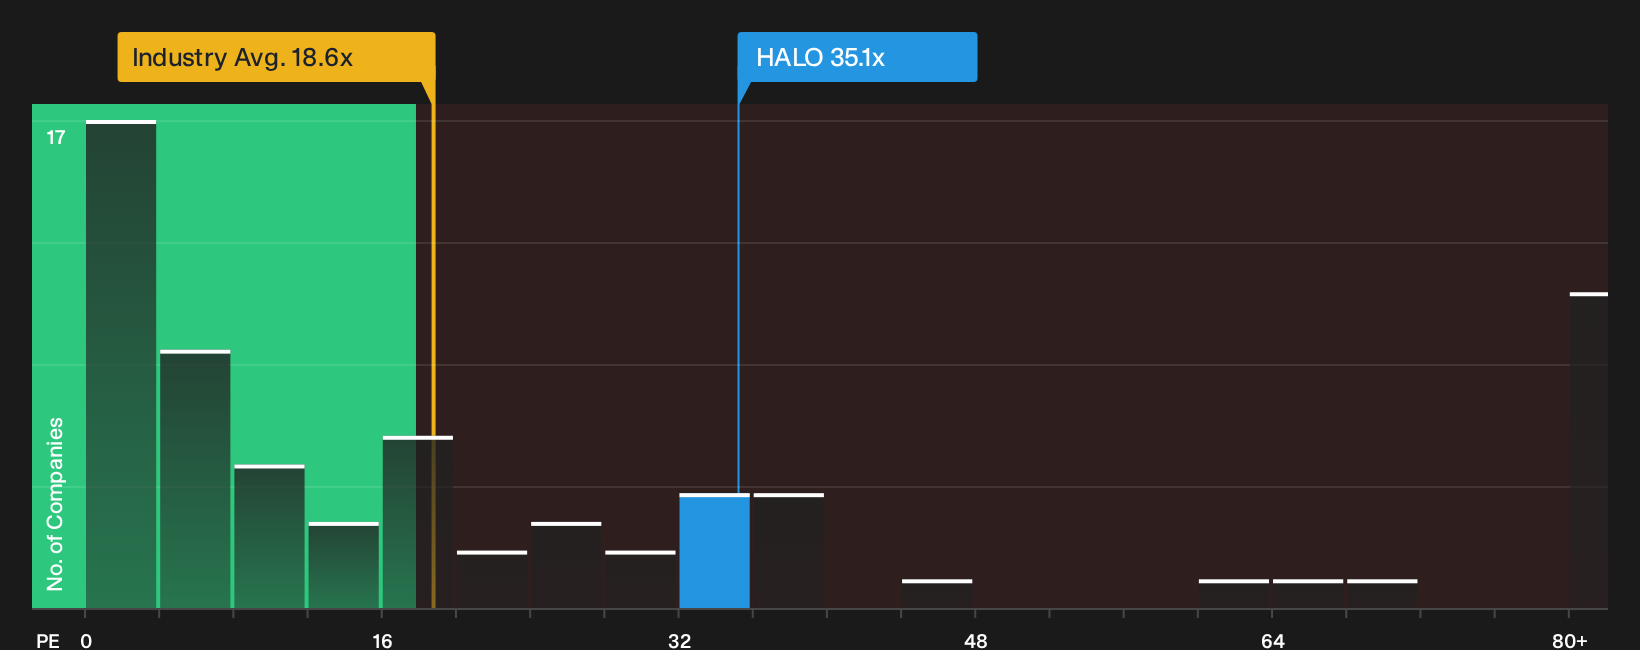
Halozyme Therapeutics looks cheap against a $151.83 narrative fair value and a $433.68 figure from the SWS DCF model. The P/E ratio tells a less generous story. At 35.1x, it sits above the US Biotechs average of 18.6x and the 22.8x fair ratio, which points to valuation risk if sentiment cools.
For a closer look at how this earnings-based comparison stacks up against the broader peer group, and where the fair ratio suggests the market might eventually drift, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Halozyme Therapeutics is clearly mixed, with royalty strength on one side and valuation questions on the other. Move quickly, review the data points that matter to you, and weigh both the upside and downside using our breakdown of 2 key rewards and 3 important warning signs
Looking for more Halozyme Therapeutics style investment ideas?
If Halozyme Therapeutics has you thinking more carefully about pricing power, royalty streams, and quality, broaden your watchlist before the next move passes you by.
- Target resilience first by reviewing a 30 resilient stocks with low risk scores that can help you filter for businesses where volatility and risk scores stay under tighter control.
- Hunt for quality at a discount with a focused 29 high quality undervalued stocks that highlights companies combining solid fundamentals with potentially attractive pricing.
- Spot strong balance sheet support early through a curated list of solid balance sheet and fundamentals (24 results) so you are not scrambling for safer ideas after conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com