


EN
PLS Group (ASX:PLS), What Is Behind The Latest Attention?
What PLS Group’s new US$700 million bond means for shareholders
PLS Group (ASX:PLS) has priced a US$700 million senior unsecured notes issue to help fund its P2000 Project, planned capacity expansion and infrastructure spending at the Pilgangoora lithium operation.
The new bond comes after a tougher period for PLS Group’s equity investors, with the share price at A$2.88 and a 30 day share price return down 25%. The year-to-date share price return has declined 33.2%, although the five-year total shareholder return is still up 39.1%.
Scan beyond PLS Group and size up other lithium and materials producers that our analysts have filtered into a 34 best rare earth metal stocks for investors watching capital-heavy expansion stories like this one.
PLS Group is putting serious money behind Pilgangoora, yet the share price has retreated and the new bond adds fresh obligations. Does that combination leave the stock attractively valued or still demanding?
Most Popular Narrative: 36% Undervalued
On the numbers driving the most followed view, PLS Group’s fair value sits at A$4.54 against a last close of A$2.88. This points to a wide gap that the narrative attempts to explain through Pilgangoora’s scale up and capital spend.
The combination of a cash balance of about A$2.3b, total liquidity approaching A$2.8b and a recently issued US$600 million senior unsecured bond due 2031 gives PLS Group scope to fund higher FY27 capex of A$620 to A$685 million and future projects like P2000, which can influence long term production capacity, revenue and earnings power.
See why 142 investors see PLS Group as 37% undervalued.
Result: Fair Value of A$4.54 (UNDERVALUED)
Still, the thesis around PLS Group could be pressured if lithium prices soften again, or if the enlarged Pilgangoora capex program overruns planned budgets.
Find out about the key risks to this PLS Group narrative.
Another way to look at PLS Group’s value
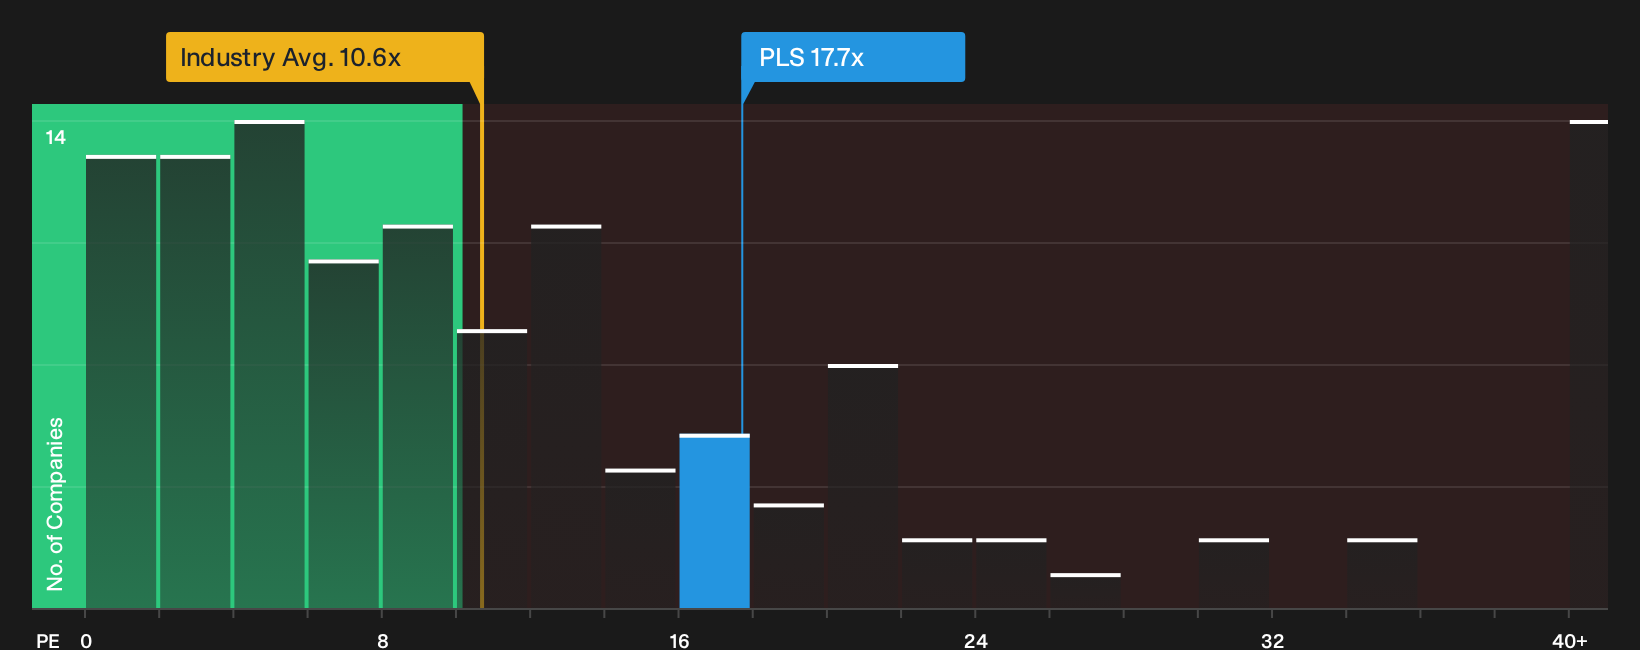
The first narrative leans on analyst fair value and price targets. A different lens is the plain P/E ratio. PLS Group trades at 17.7x earnings, compared with an industry average of 10.6x and a fair ratio of 16x. This tilts the picture toward valuation risk rather than clear upside, so which story do you trust more?
To unpack what those ratios imply in more detail, including where the market could shift toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling torn between PLS Group’s fair value case and the richer P/E story is normal. The quickest way to cut through is to check the underlying data yourself and pressure test the key assumptions that matter most to you. To see what is driving investor optimism around the potential upside, take a closer look at the 3 key rewards.
Looking for more PLS Group investment ideas?
If PLS Group has sharpened your focus on value, capital allocation and risk, it may be worth widening the lens to other opportunities before the market moves.
- Target potential mispricings by scanning a 2 high quality undervalued stocks that filters for quality businesses whose current tags differ from their fundamentals.
- Build a sturdier income stream by reviewing 4 dividend fortresses that balance higher yields with robust underlying financials.
- Reduce portfolio stress by focusing on 6 resilient stocks with low risk scores that pair resilient balance sheets with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com