


EN
Digital Turbine (APPS) Stock Could Trade At A Discount Despite A 106% Run
Digital Turbine has seen sharp swings in recent years, and the share price moves raise a straightforward question for you as an investor. Is the current US$9.62 price tag adequately supported by the revenue that the business is bringing in today.
- Over the past 3 years the stock has returned 106.0%, which puts a lot of weight on whether the current valuation lines up with what its sales can justify.
- The business model is tightly linked to app distribution and advertising on mobile devices, so expectations for future revenue growth and the quality of those sales streams can heavily influence how much investors are prepared to pay for each dollar of turnover.
- There is a second opinion on Digital Turbine worth weighing. See what analysts think Digital Turbine's shares could be worth.
For investors, the debate is whether Digital Turbine's present share price is well supported by its sales performance and prospects.
If you are weighing whether Digital Turbine's US$9.62 share price lines up with its sales, it can help to compare it with a wider basket of 29 high quality undervalued stocks.
Is Digital Turbine a Bargain on Sales?
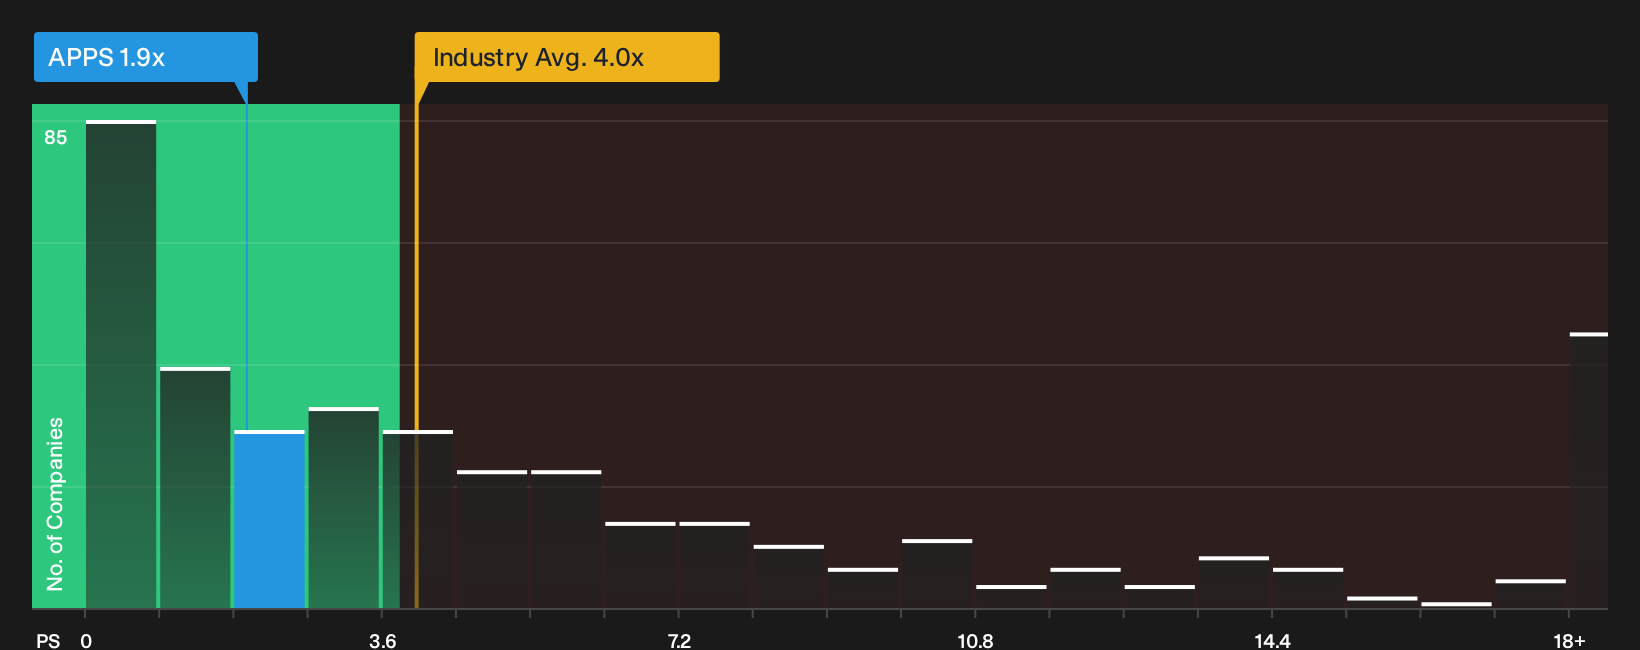
The P/S ratio suits Digital Turbine because revenue is still a key reference point while earnings are negative. On this lens, the stock trades on a P/S of about 1.9x, which sits below the software industry average of roughly 4.0x and also below the peer group near 2.4x. That gap indicates the market is paying less for each dollar of Digital Turbine's sales than it is for many software rivals.
The Fair Ratio model, which adjusts for factors like growth prospects, margins, size and risk, suggests the P/S that might typically apply to Digital Turbine would be higher than where it trades today. That leaves the current 1.9x multiple screening as undervalued against this more tailored benchmark, so you would be weighing whether the business quality and future execution can support a closing of that gap. Explore the numbers behind Digital Turbine's P/S valuation.
The Digital Turbine Narrative: What Would Justify Today's Price?
Narratives on Digital Turbine act as the link between today's P/S puzzle and the assumptions that would need to hold on growth, margins and earnings for the stock to be worth significantly more or less than its current price, and they sit on Simply Wall St's Community page. Each narrative ties a specific fair value estimate to a clear storyline about Digital Turbine's potential catalysts and key risks so you can track over time which version of events is actually unfolding.
One of the top community narratives on Digital Turbine: 36% undervalued
"The main thing that has to go right is for Digital Turbine to keep turning its AI driven ad platforms, international carrier partnerships, and alternative app distribution tools into sustained double digit growth and expanding EBITDA margins…"
Discover why this Narrative puts Digital Turbine at 36% undervalued.
One more check for Digital Turbine sits with who is steering it
Price tags and sales multiples only tell part of the story, because the people setting priorities at Digital Turbine and the way their pay is structured can heavily shape what happens next. See who runs Digital Turbine and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com