


EN
Does CoStar Group (CSGP) Trade At A Premium For Good Reason?
CoStar Group has seen its share price fall sharply over recent years, even with a short burst of strength in the past month. This puts a spotlight on whether the current valuation can be explained by the revenue it generates. With investors watching both the stock and the real estate data it supplies, the central issue is how much sales power justifies today's market price.
- Over the past 5 years, CoStar Group's share price return declined 60.4%, which puts pressure on the case that the present valuation reflects what its sales performance can support.
- Recent commentary around CoStar Group's ability to manage spending while supporting revenue growth expectations suggests that profitability and cash generation from those sales can become a bigger swing factor for how the stock is priced.
- The analysts covering CoStar Group have run their own numbers. See what analysts think CoStar Group's shares could be worth.
The stock's next move may depend on whether CoStar Group's sales are strong and durable enough to justify the price investors are paying today.
If you want to stress test this same sales based valuation question beyond CoStar Group, line it up against a wider set of 29 high quality undervalued stocks.
Does CoStar Group Look Fairly Valued on Sales?
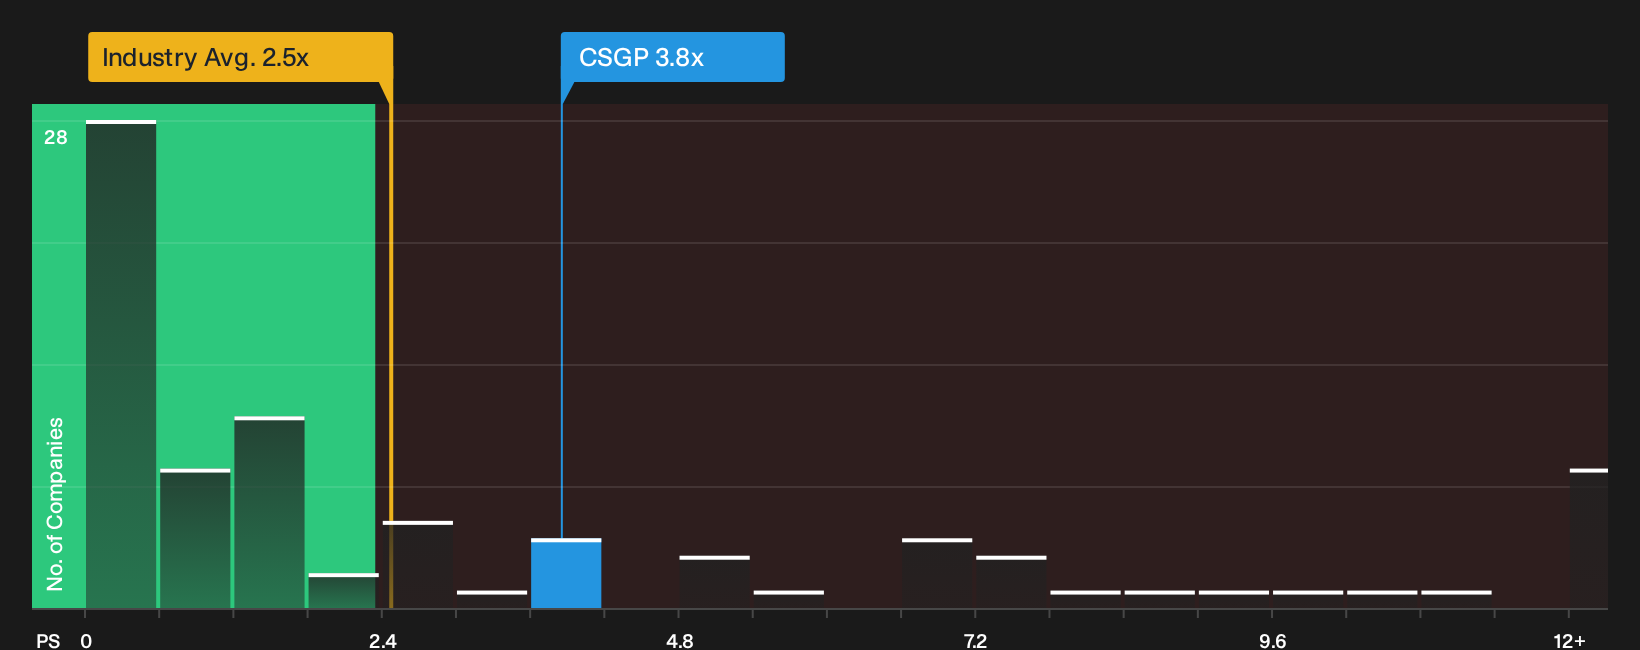
P/S is a useful lens for CoStar Group because investors often anchor the valuation to how much the business can monetise its large data sets and platforms. On this measure, the stock trades on a P/S ratio of 3.8x, compared with about 2.5x for the broader real estate sector and a peer group average of roughly 1.4x. That puts CoStar on a clear premium to both its industry and closer listed comparables.
The fair-value model that blends factors such as growth expectations, profitability profile, size and risk points to a P/S level that is very close to where CoStar Group trades today. This suggests the current multiple is about right rather than obviously cheap or expensive. Because RBC recently highlighted expectations for stronger EBITDA and tighter spending, the market is already recognising that potential in the current sales multiple. Investors weighing CoStar's price tag now need to decide whether the quality and durability of those revenues justify paying this kind of P/S premium over other real estate stocks. Explore the numbers behind CoStar Group's P/S valuation.
The CoStar Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CoStar Group pick up where the P/S discussion leaves off. They spell out which combinations of future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and each ties its numbers to a concrete view on how CoStar Group's expansion, profitability and risk profile could evolve. This gives you something you can revisit as fresh information comes through.
One of the top community narratives on CoStar Group: 35% undervalued
"The current valuation implies the share price does not fully reflect Homes.com depth advertising potential, the scaling of CoStar Debt Solutions and the earnings impact of substantial share repurchases..."
Discover why this Narrative puts CoStar Group at 35% undervalued.
Before you act on CoStar Group's valuation, there is one more angle to check
Price and sales only tell part of CoStar Group's story, because our broader review has also highlighted specific risk checks that could change how you view the opportunity once you see them. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com