


EN
Houlihan Lokey (HLI) Could Be 14% Below Fair Value After Derek Herbert Hire
Houlihan Lokey (HLI) has just added Derek Herbert as a Managing Director in its Capital Solutions Group, with a focus on direct equity transactions. This development gives investors fresh context for the stock.
Recent trading indicates that sentiment around Houlihan Lokey is still reset lower, with the share price at US$131.21 and a year-to-date share price return down 25.6%, even though the 1-week share price return gained 3.3%. That shorter-term uptick comes against a 1-year total shareholder return that declined 34.0%, while long-term holders still sit on total shareholder returns of 38.1% over 3 years and 23.6% over 5 years. This frames the Derek Herbert hire and the recent US$3.14b shelf registration as part of a story where long-run gains remain intact but momentum has cooled for now.
Compare how Houlihan Lokey stacks up against other financial firms that have seen sentiment cool yet still show solid fundamentals using our hand-picked 29 high quality undervalued stocks.
Houlihan Lokey keeps investing in its franchise while the share price has cooled. The real tension now is simple: does a solid advisory platform at US$131.21 still count as good value today?
Most Popular Narrative: 14.5% Undervalued
Houlihan Lokey last closed at $131.21, while the most widely followed narrative pegs fair value at $153.50. The story centers on whether that gap reflects mispricing or justified caution.
The main thing that has to go right is that Houlihan Lokey converts its record Corporate Finance pipelines and growing Capital Solutions and secondaries activity into completed higher fee transactions at a pace that outstrips rising non compensation costs and ongoing investment in technology and data.
The current numbers and valuation imply the market is not fully pricing in Houlihan Lokey’s record FY26 revenue of US$2.6b, 20% adjusted EPS growth to US$7.56, sustained 61.5% compensation ratio, leading M&A and restructuring deal counts, and expanding private capital and secondaries advisory franchise, so the stock appears undervalued.
See why 8 investors see Houlihan Lokey as 15% undervalued.
Result: Fair Value of $153.50 (UNDERVALUED)
Still, the narrative can break if muted sponsor activity keeps Corporate Finance fees under pressure, or if rising non compensation costs outrun Houlihan Lokey’s advisory revenue.
Find out about the key risks to this Houlihan Lokey narrative.
Another View: What Houlihan Lokey’s P/E Is Telling You
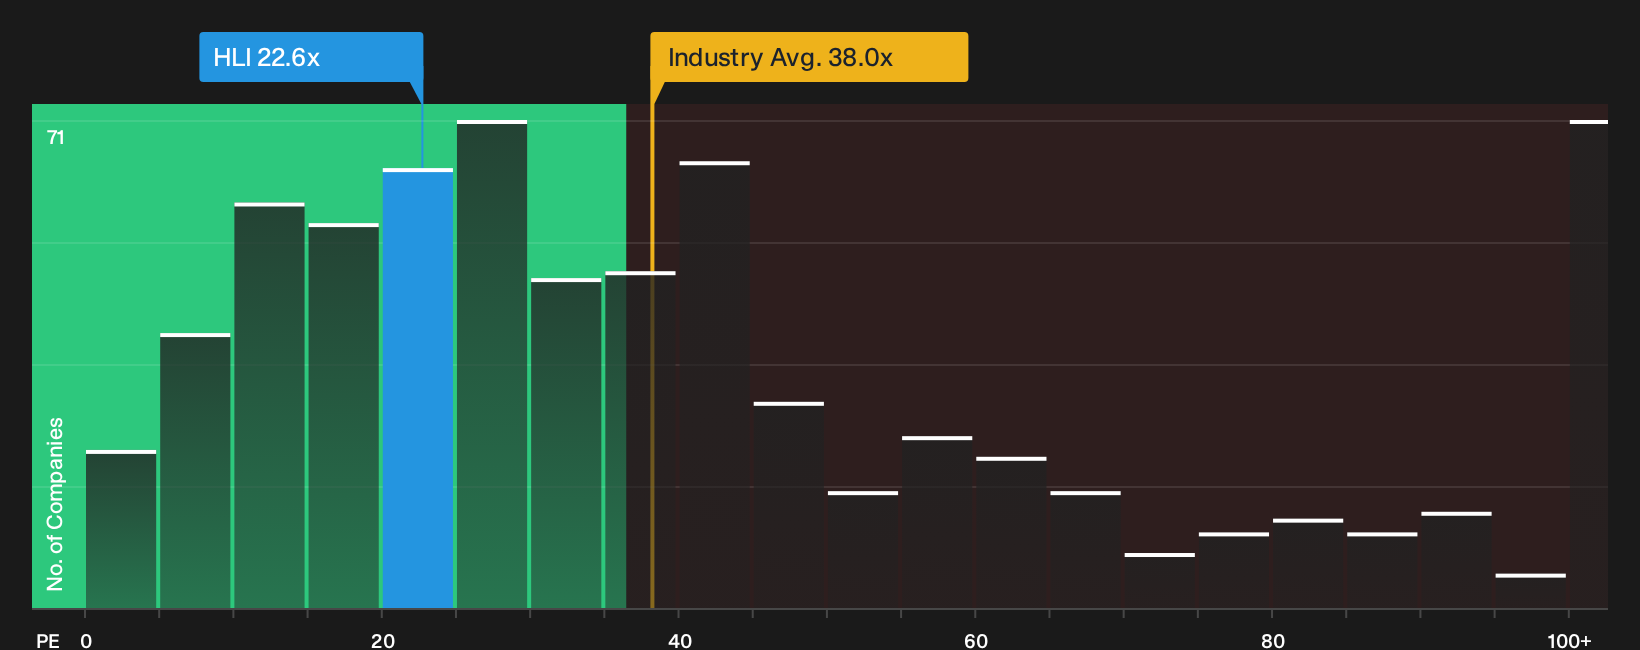
The first narrative leans on cash flows and long term earnings power. A simpler lens tells a different story. Houlihan Lokey trades on a P/E of 22.6x, while peers sit near 11.4x and the fair ratio is 12.8x. That premium points to valuation risk if sentiment keeps cooling.
For investors comparing multiples across the sector, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Houlihan Lokey leaves you unsure, act quickly, carefully review the data, and focus on what increases your confidence. To understand why some investors still see upside in this setup, review the 3 key rewards
Looking for more investment ideas beyond Houlihan Lokey?
If Houlihan Lokey has sharpened your thinking, widen your search now with focused stock ideas so you do not miss opportunities that better match your style.
- Target resilient cash generators and review a 5 dividend fortresses backed by income and balance sheet support.
- Scan for potential mispriced opportunities using the 21 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Prioritize capital protection first and run a 30 resilient stocks with low risk scores to see which businesses score well on financial strength and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com