


EN
MSA Safety (MSA) Lands Its Biggest Detector Deal Yet, Is The Stock Fully Priced?
MSA Safety (MSA) is back in focus after securing its largest ALTAIR io 6 Multigas Detector contract. The company signed a five-year agreement with a major northeastern US utility worth up to US$10.6 million.
At a share price of US$182.57, MSA Safety has built steady momentum, with a 7-day share price return of 2.14% and a year-to-date share price return of 12.53%. The 1-year total shareholder return of 10.78% and 5-year total shareholder return of 30.82% point to gains that long term holders have already experienced as contract wins like this feed into sentiment around future revenue and risk.
Scan other safety-focused stocks showing similar contract momentum with our curated 30 resilient stocks with low risk scores, built for investors who care about resilient balance sheets as much as headline deals.
MSA Safety now trades near record territory after this contract win, so the real puzzle is whether recent optimism has already priced in the story or whether patient holders still have meaningful upside left.
Most Popular Narrative: 13% Undervalued
Against a last close of $182.57, the most followed narrative pegs MSA Safety’s fair value at $209.14. This frames this new contract against a higher long term expectation built on its detection and connected safety mix.
The current valuation implies the market is not fully crediting MSA Safety for its mix shift toward higher margin detection and connected solutions, the upcoming SCBA replacement cycle, and its record of disciplined capital deployment.
See why 4 investors see MSA Safety as 13% undervalued.
Result: Fair Value of $209.14 (UNDERVALUED)
Still, the MSA Safety story can break if weakness in Middle East related detection drags on or if cost pressures keep gross margins below management’s guided range.
Find out about the key risks to this MSA Safety narrative.
Another View: MSA Safety Through Earnings Ratios
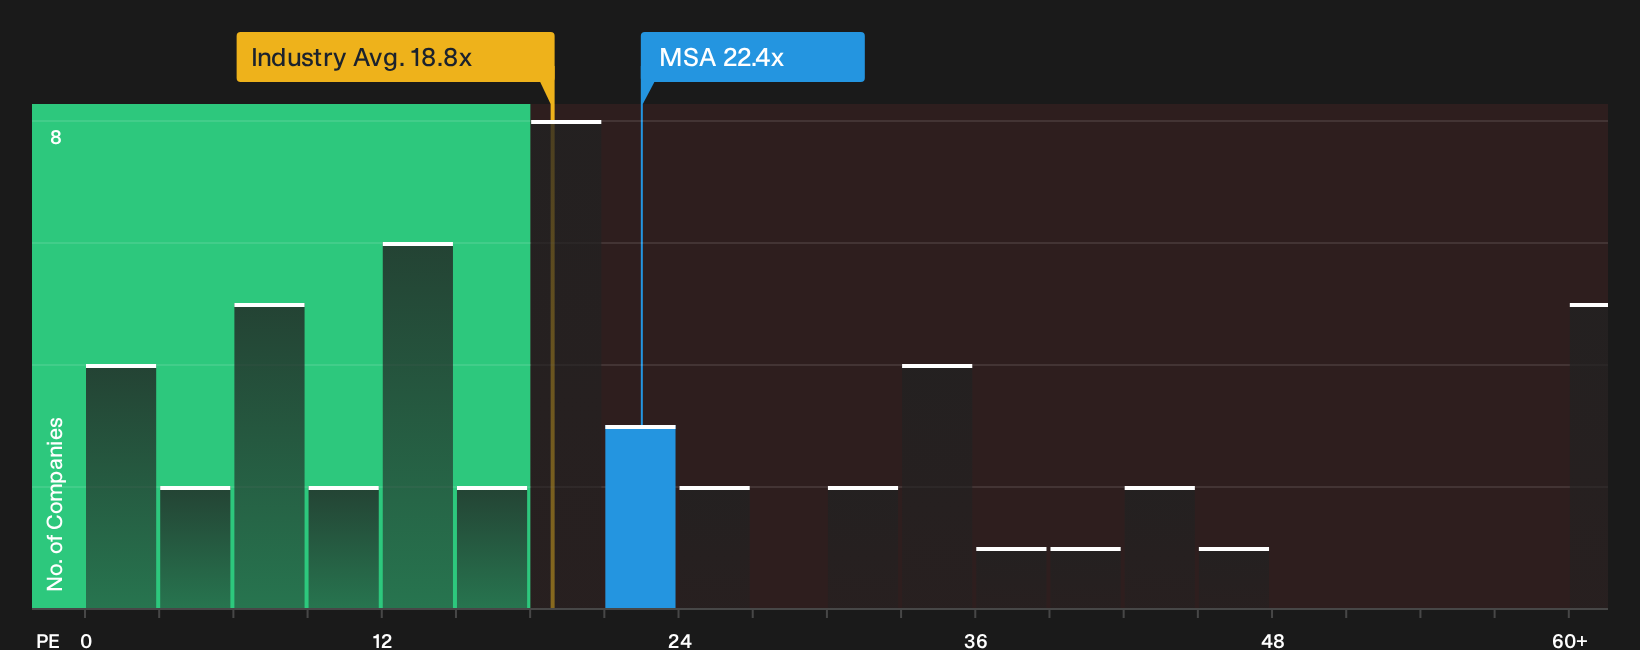
The story looks different when you step away from fair value models and focus on what investors are paying for each dollar of MSA Safety earnings. The current P/E sits at 22.4x, which is higher than both the US Commercial Services industry at 18.8x and peer average at 15.6x.
A fair ratio of 18.1x suggests the multiple could drift closer to that level if sentiment cools, which would limit upside even if the business keeps growing. For anyone weighing that risk, the key question is simple: Is this premium justifiable, or has the enthusiasm run ahead of itself?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and concern around MSA Safety only matters if you test it against the numbers yourself and move before sentiment shifts. To pressure test both sides of the story in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond MSA Safety?
If you only stop at MSA Safety, you risk missing other opportunities that match your style and risk tolerance across different parts of the market.
- Target steady cash returns by scanning for income-focused opportunities through the 5 dividend fortresses.
- Hunt for mispriced quality by working through the 29 high quality undervalued stocks before the crowd catches on.
- Zero in on balance sheet strength by filtering for financially resilient businesses using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com