


EN
Should Rimini Base Expansion Require Action From Ryanair (ISE:RYA) Investors?
- Ryanair Holdings has invested €200 million in a new two aircraft base at Rimini, doubling Summer 2027 capacity to 600,000 seats across 17 routes after Emilia Romagna removed its Municipal Tax.
- The link between regional tax cuts, route expansion and CEO guidance for higher European fares puts Ryanair’s cost advantage and pricing power in sharp focus.
- The focus now shifts to how Ryanair’s Rimini build out and tax driven capacity reshuffle could reshape the airline’s longer term investment narrative.
Ryanair Holdings Investment Narrative Recap
To hold Ryanair Holdings, you need to believe its low cost model can still turn constrained European capacity and higher fare expectations into acceptable returns, even as fuel and tax regimes stay volatile. The Rimini base fits that logic by pushing more aircraft into airports where local policy is supportive and demand can be concentrated.
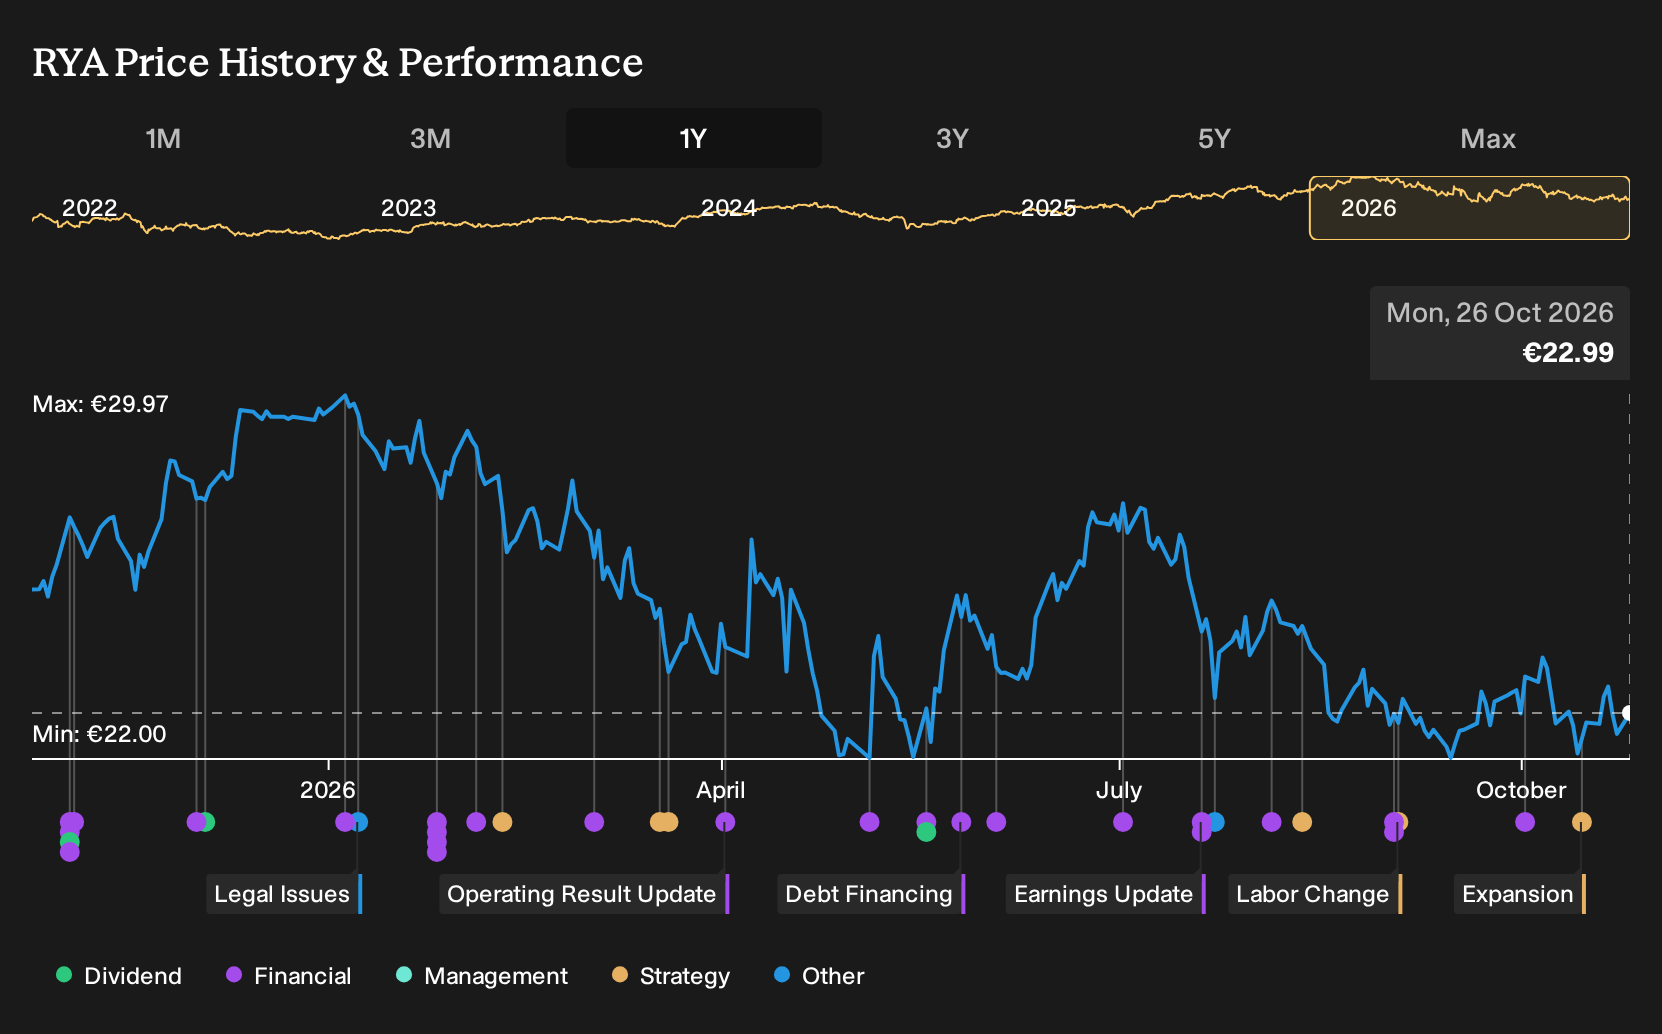
The key short term swing factor remains how higher jet fuel and potential fare increases interact with already softer share performance and recent earnings pressure. The biggest risk is that fuel costs and any demand pushback on pricing move faster than Ryanair can reallocate aircraft or flex capacity, in which case Rimini is helpful but not decisive.
The most relevant recent message for this Rimini move is CEO Michael O'Leary flagging a possible 10% to 20% rise in European airfares in 2027 driven by jet fuel and industry capacity. That comment frames Rimini less as a one off expansion and more as part of a broader attempt to lean into higher yielding routes where taxes are lighter.
For investors, the link between unhedged fuel exposure, fare guidance and targeted airport deals is where the near term catalysts are likely to be found. Execution risk is clear. Ryanair needs to keep planes full in places like Emilia Romagna while absorbing fuel volatility without giving up its cost gap, or the current valuation debate around ISE:RYA will likely remain unresolved.
Ryanair Holdings is currently modelled on analyst assumptions that point to revenues of €18.5b and earnings of €2.6b by 2029. This implies annual top line growth of 5.9% and an earnings increase of about €0.7b from earnings today of €1.9b.
Uncover how Ryanair Holdings' fair value indicates a 23% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly €28 to €54 per share, with one estimate almost double another. That spread underlines how differently private investors currently judge Ryanair Holdings as fuel volatility, tax changes and fare expectations collide. Use these contrasting opinions to test your own Rimini and wider capacity assumptions.
Explore 2 other Ryanair Holdings fair value estimates, including one that suggests it could be worth just €28.20!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ryanair Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ryanair Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryanair Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryanair Holdings?
Once you have a view on Ryanair Holdings, widen the lens and test that thesis against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for mispriced quality, scan a curated set of 195 high quality undervalued stocks that combine solid fundamentals with support from detailed valuation work.
- If capital preservation and steadier profiles rank higher for you, filter for 223 resilient stocks with low risk scores that score well on resilience and financial strength.
- Those willing to do extra homework on underfollowed opportunities can review 610 high quality undiscovered gems that pair robust balance sheets with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com