


EN
3 Auto And Steel Stocks Tied To North American Onshoring
Trade headlines around possible tariff hikes on Canadian steel and autos are not just political theatre; they are reshaping where cars get built and where profits might pool. Supply chains that once felt permanent now look up for grabs, which can reward some stocks and leave others exposed. This article walks through three companies tied to North American auto and steel onshoring and explains how this news could matter for your portfolio.
The stocks highlighted below are a small sample of what onshoring could mean for auto and steel related profits, and the full screen surfaced 26 more companies with equally compelling narratives that are not covered here. To identify and analyze which of these might fit your own conviction, head straight into the North American Auto & Steel Onshoring Beneficiaries screener.
Quaker Chemical (KWR)
Overview: Quaker Chemical supplies specialized process fluids and chemical services that keep metal cutting, forming and finishing lines running efficiently worldwide.
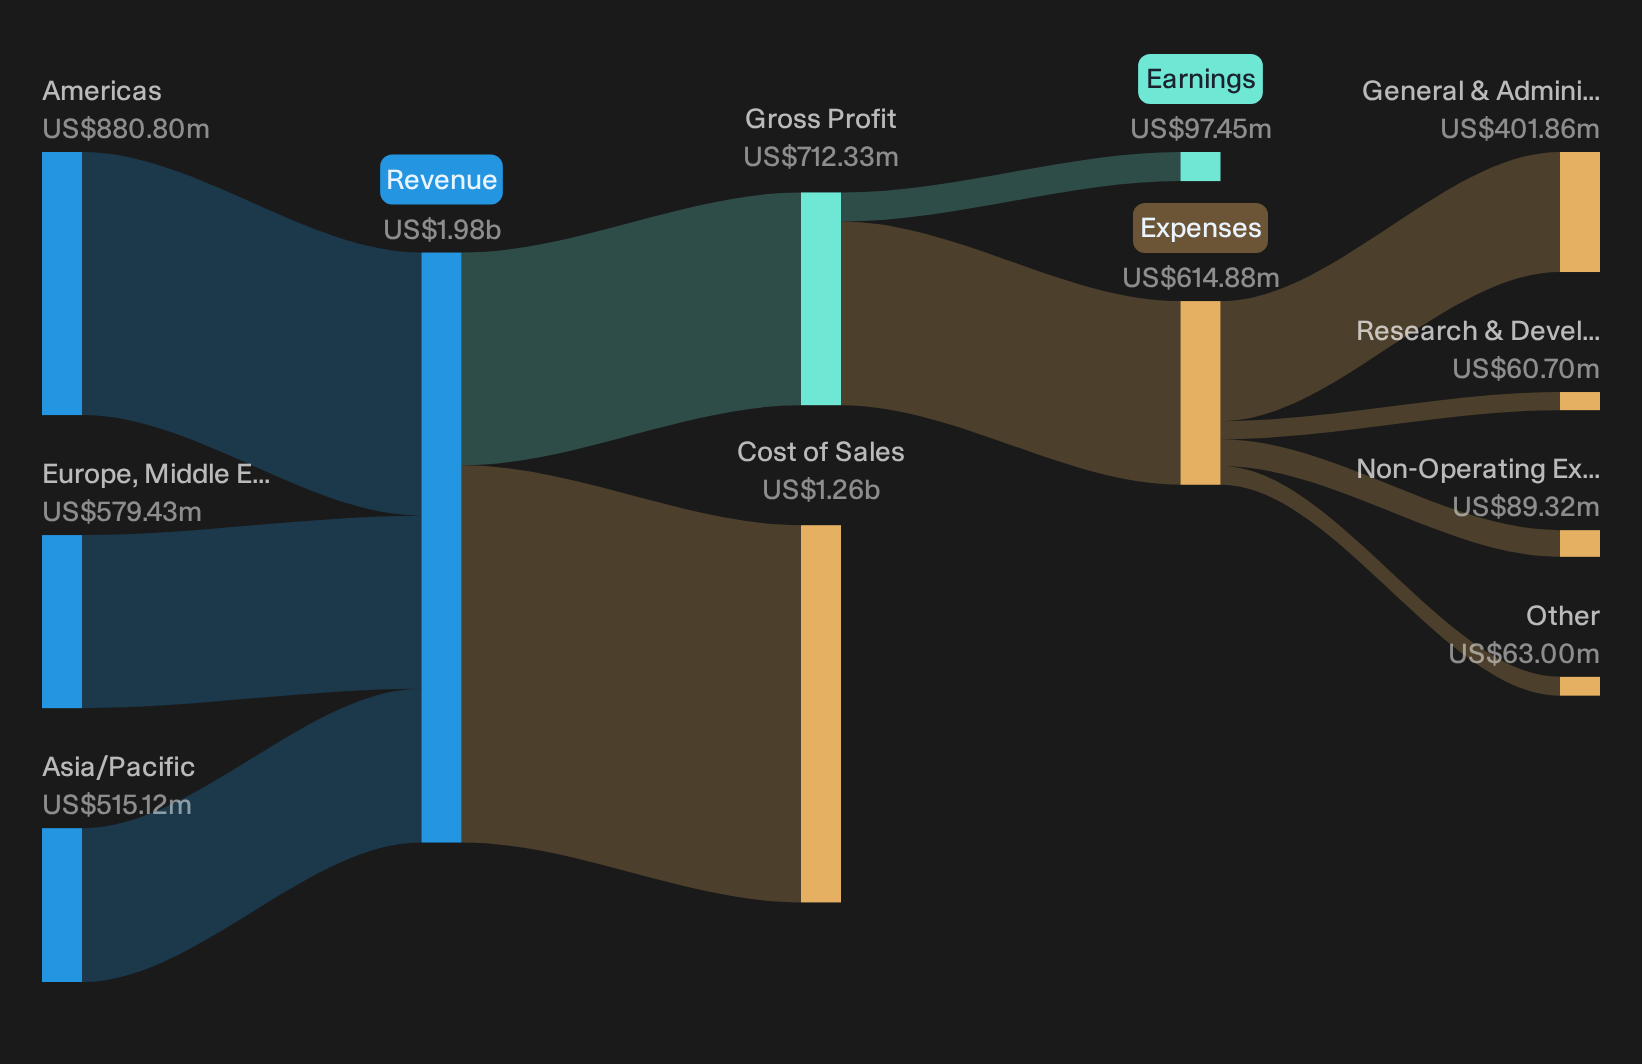
Operations: The business generates roughly US$880 million of revenue in the Americas, with Asia/Pacific at about US$515 million and EMEA near US$579 million.
Market Cap: US$2.7b
Quaker Chemical matters for this onshoring theme because its fluids touch the steel coils, body panels and components that North American automakers rely on every day.
"Quaker Chemical is continuing to see Asia Pacific volumes grow faster than its flat to slightly down aggregate end markets, supported by ongoing new business wins with EV OEM and component customers in China, India, Thailand and Vietnam."
What happens to margins if a single cost saving push in the Americas finally lines up with that global demand momentum?
If that margin inflection point is what you are watching for, the full narrative for Quaker Chemical outlines how that shift could either accelerate the story or cause it to stall.
Metallus (MTUS)
Overview: Metallus manufactures alloy, carbon and micro-alloy steel bars, tubes and precision components that feed into North American automotive and heavy equipment supply chains.
Operations: Metallus reports about US$1.2b of revenue from its Metal Processors and Fabrication segment, reflecting concentration in specialty long steel products.
Market Cap: US$846 million
Metallus matters for this onshoring theme because it melts and shapes the kind of specialty steel that automakers and capital equipment builders increasingly want sourced inside U.S. borders.
"Although Metallus is working to ramp aerospace and defense programs toward a higher revenue run rate, persistent shop floor execution problems, power interruptions and maintenance reliability issues that held melt utilization to 74% in 2Q26 raise the risk that this capacity is not converted into earnings."
What happens to Metallus margins if that tension between more orders and one stubborn operational constraint finally breaks in either direction?
If that operational bottleneck is what you are watching, the full narrative for Metallus maps out how Metallus could shift from a constrained producer to an accelerating cash engine.

Martinrea International (TSX:MRE)
Overview: Martinrea International designs and manufactures lightweight structures and propulsion systems for automakers, supplying key components into North American vehicle programs.
Operations: The business generates about CA$4.7b from auto parts and accessories, with sizable manufacturing footprints in Mexico, the U.S., Canada and Europe.
Market Cap: CA$656 million
Martinrea International sits close to the action on North American content rules, since its lightweight structures and propulsion systems plug directly into vehicle platforms that automakers want sourced inside the trade bloc.
"Martinrea International is seeing growing opportunities as OEMs are reshoring and localizing production in North America."
What happens to Martinrea International margins if one stubborn cost pressure eases just as that reshoring driven order book fills out?
If that margin reset is what you are waiting on, the full narrative for Martinrea International explains how Martinrea International could turn today’s reshoring push into accelerating long term earnings power.

Seeking Alternatives Before Momentum Flies
Fresh ideas tend to move first, and late money often gets caught chasing someone else’s breakout. Scan curated opportunities that are still under the radar while it matters, and consider getting in earlier in the process.
- Explore potential early-stage rebounds by reviewing curated opportunities inside the list of solid balance sheet and fundamentals (24 results) before the strongest balance sheets attract broad attention.
- Assess structural demand shifts by reviewing the 16 top copper producer stocks that could be positioned to participate if capital continues to focus on critical metals for electrification and infrastructure.
- Evaluate durable income streams by checking out the 5 dividend fortresses that combine higher yields with fundamentals you can review in a few focused minutes.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com