


EN
New CMO Hire Could Be A Big Test For Coursera Stock
- Coursera appointed Amy Weisenbach as Chief Marketing Officer, effective 30 November 2026. She brings senior marketing experience from The New York Times, Wilson Sporting Goods, Beam Suntory, and Unilever.
- Her background in subscription marketing and consumer engagement is closely aligned with Coursera’s focus on paid learner growth and deeper use of its skills platform.
- We will now assess how Coursera’s investment narrative could be influenced by Amy Weisenbach’s subscription-focused marketing experience.
Coursera Investment Narrative Recap
To stay interested in Coursera, you need to believe the online learning model can keep attracting new learners while converting more of them to paying users across consumer and enterprise offerings. In the near term, an important factor is whether paid adoption of degrees, Coursera Plus and enterprise contracts can improve fast enough to narrow losses while competition and free content keep squeezing pricing power.
Amy Weisenbach’s arrival as CMO looks directionally helpful for those conversion and engagement goals but does not change the immediate risk profile. The biggest operational risk still sits with weak monetization from free users and any slowdown in institutional budgets that could weigh on Coursera’s 24.9% forecast annual revenue growth.
The most relevant recent context for this CMO hire is Coursera’s push into AI powered products like Helix and personalized tutoring features. These tools aim to lift engagement and support higher value subscriptions across both the Consumer and Enterprise segments, which together produced US$885.4 million in sales over the last reported period.
Execution risk remains high. The group is still loss making with net income of US$136.3 million in the red and shareholders have faced substantial dilution over the past year. For investors, the key question is whether stronger marketing leadership can help Coursera convert that product pipeline into better ARPU and a clearer path toward the profitability analysts are forecasting.
What The New CMO Means For Coursera’s Targets
On current analyst assumptions, Coursera is modeled to reach US$911.0 million in revenue and US$110.4 million in earnings by 2029, built on 5.6% yearly top line growth and an earnings swing of about US$174.1 million from a loss of US$63.7 million today.
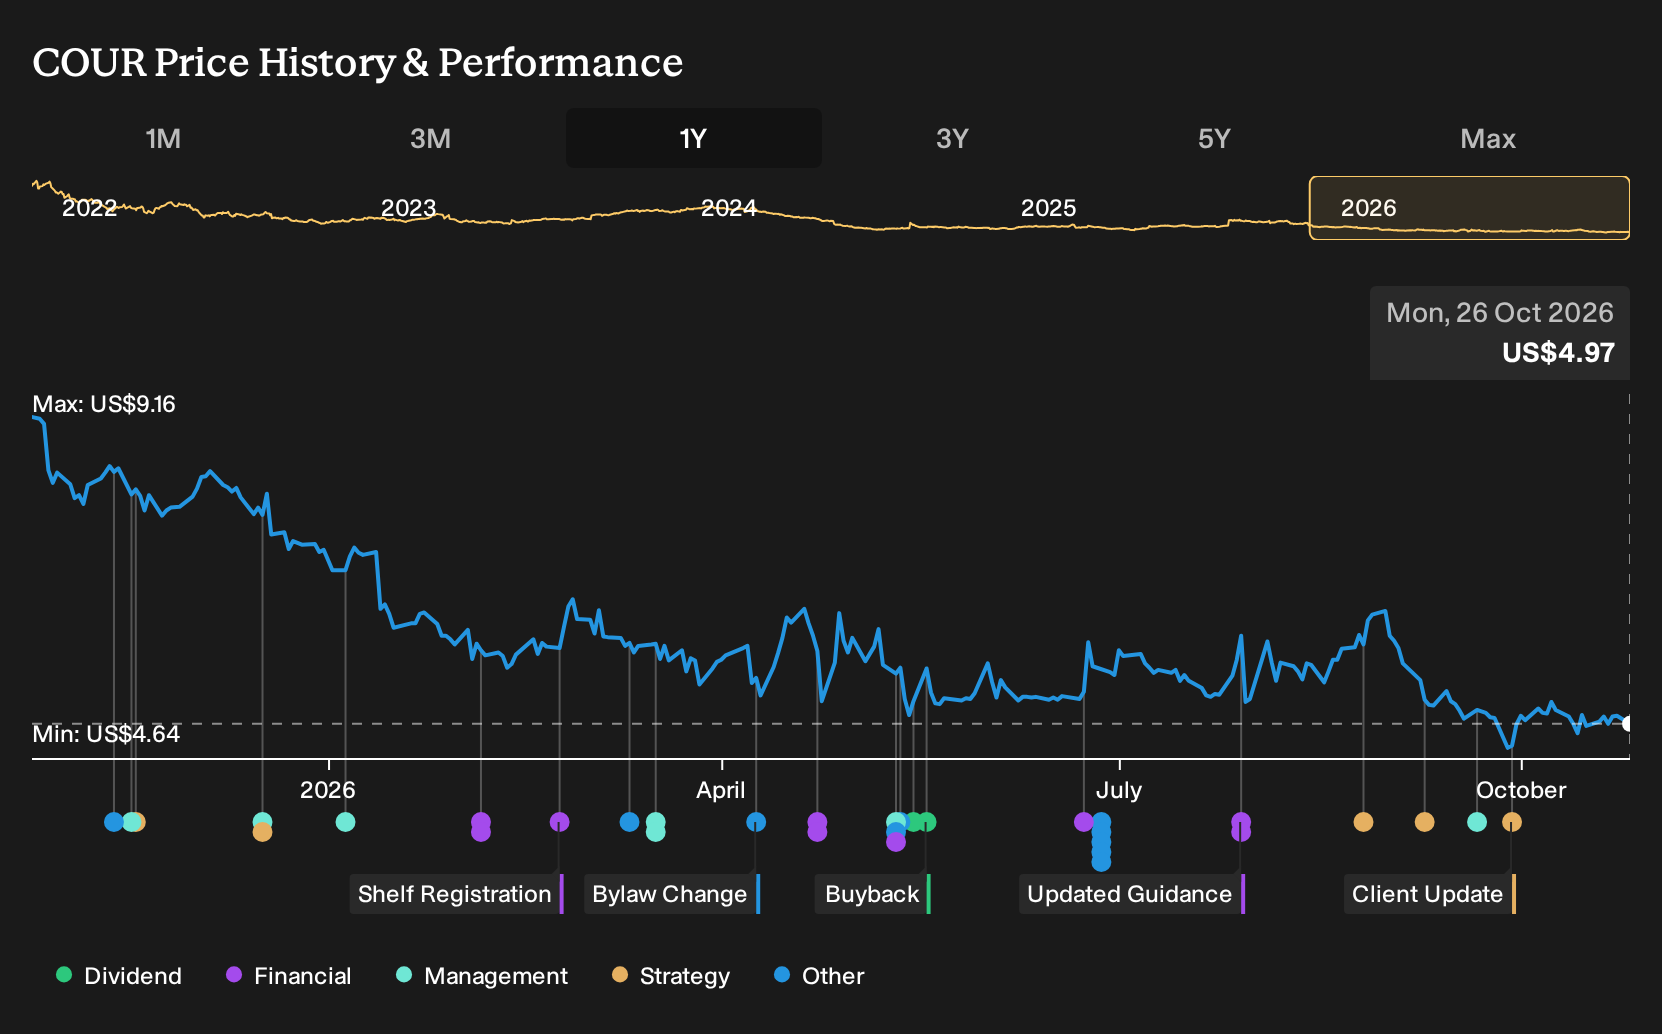
Uncover why Coursera's fair value indicates a 61% potential upside to its current price, which could materialize sooner than many investors expect.
Exploring Other Perspectives
One more optimistic angle on Coursera comes from bulls who focus on the Udemy integration as the real swing factor rather than just competitive pressure. Those analysts were modeling about US$2.0b of revenue and US$149.3 million of earnings by 2029 before this CMO hire, so you can treat today’s news as a fresh reason to compare different forecasts and decide which story you find more convincing.
Explore 4 other Coursera fair value estimates, including one that suggests as much as 859% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Coursera research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coursera. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coursera's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coursera?
Coursera is only one piece of a much wider opportunity set. If you want to cross check your thesis and surface new possibilities with similar or stronger fundamentals, the Simply Wall St Screener can help you quickly filter for the traits that match your own criteria.
- If capital preservation comes first for you, start with companies that score well on resilience and risk by using the 30 resilient stocks with low risk scores as a filter for sturdier candidates.
- Income focused investors can zero in on payout strength and yield stability by scanning through the 5 dividend fortresses to see which businesses currently offer higher cash returns.
- For those hunting for quality that the market may be overlooking, work through the 29 high quality undervalued stocks to spot stocks where fundamentals and price appear out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com