


EN
Caldwell Partners International And 2 Other TSX Penny Stocks To Consider
The Canadian market has been navigating a complex landscape, with investors closely monitoring economic indicators and market indices for signs of stability and growth. In such an environment, penny stocks—companies often characterized by their smaller size or newer presence in the market—can present unique opportunities when they are underpinned by strong financials. This article will explore three TSX penny stocks that exhibit financial robustness, offering potential value to those interested in lesser-known investment avenues.
Let's take a closer look at a couple of our picks from the screened companies.
Caldwell Partners International (TSX:CWL)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: The Caldwell Partners International Inc. and its subsidiaries offer candidate research and sourcing services across Canada, the United States, and Europe, with a market cap of CA$31.40 million.
Operations: The company generates revenue primarily from its Caldwell segment with CA$104.70 million and IQTalent segment with CA$11.51 million.
Market Cap: CA$31.4M
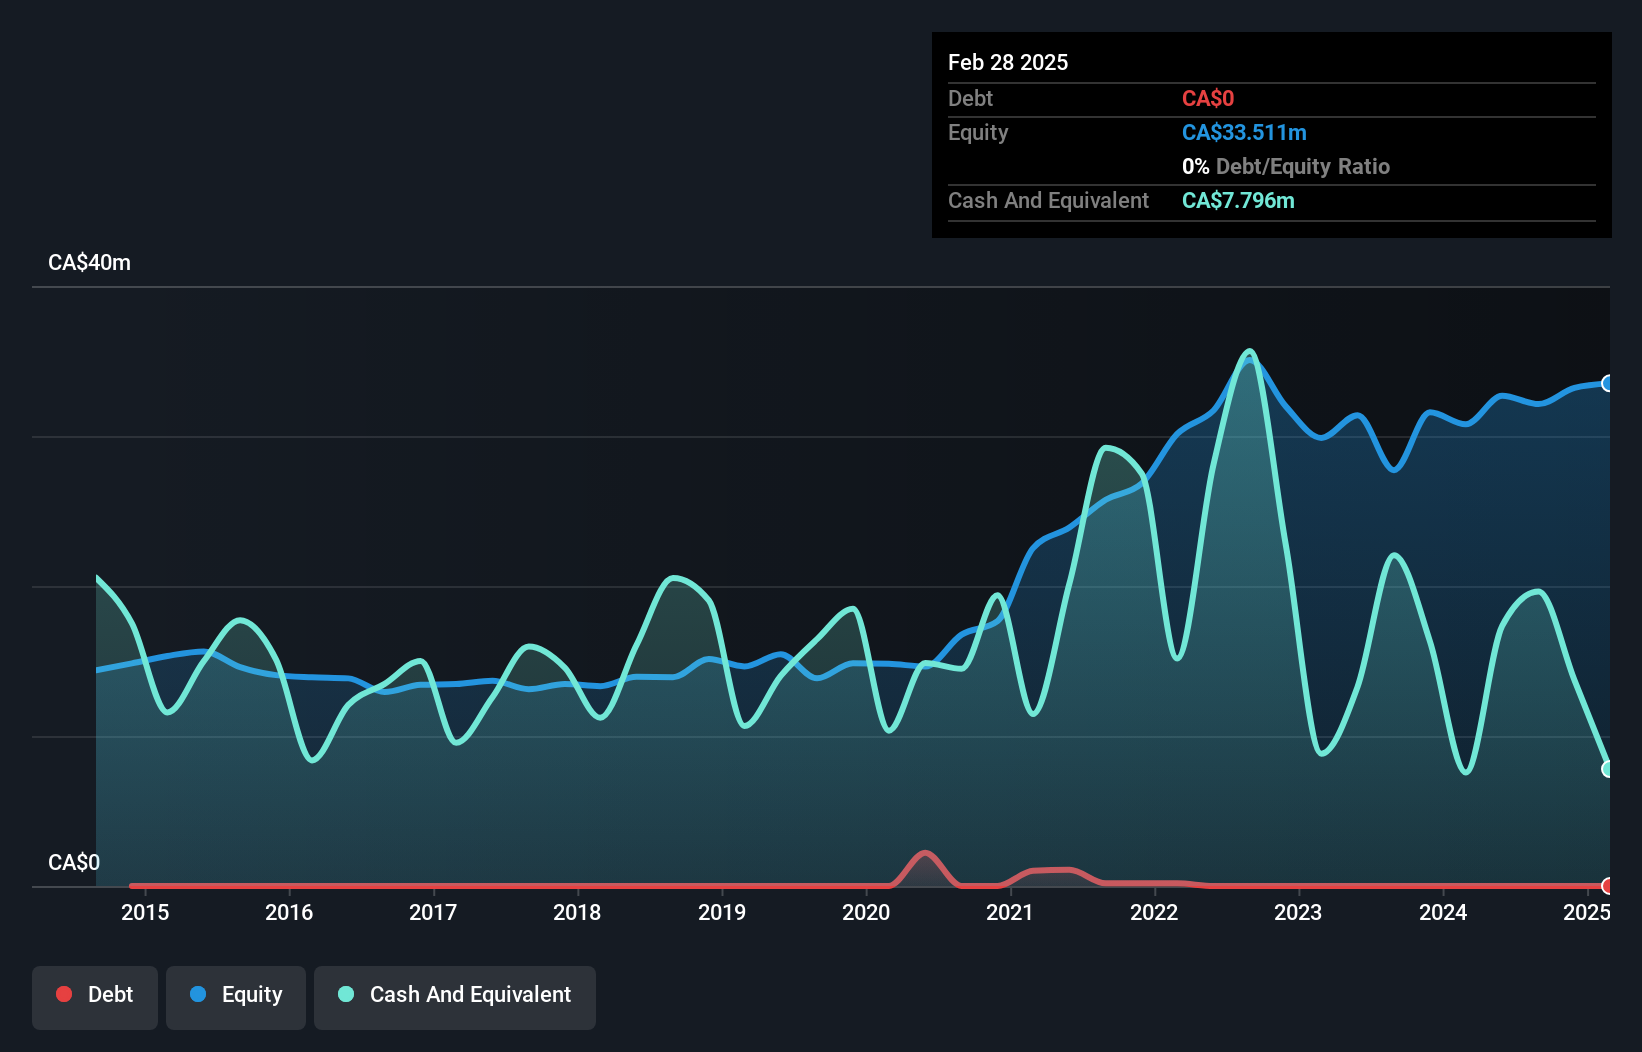
Caldwell Partners International, with a market cap of CA$31.40 million, primarily generates revenue from its Caldwell and IQTalent segments. Despite a low return on equity at 10.1%, the company has shown significant earnings growth of 485.1% over the past year, outpacing industry averages. It is debt-free and has experienced management and board teams with average tenures of 2.8 and 4.7 years respectively. The company's short-term assets exceed both its long-term liabilities (CA$5.3M) and short-term liabilities (CA$36.7M). However, it faces challenges with an unstable dividend history and declining earnings over five years at -17.9% annually.
- Click here and access our complete financial health analysis report to understand the dynamics of Caldwell Partners International.
- Examine Caldwell Partners International's past performance report to understand how it has performed in prior years.
illumin Holdings (TSX:ILLM)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: illumin Holdings Inc. is a technology company offering digital media solutions across Canada, the United States, Europe, Latin America, and other international markets with a market cap of CA$32.58 million.
Operations: The company generates CA$166.61 million in revenue from its Internet Information Providers segment.
Market Cap: CA$32.58M
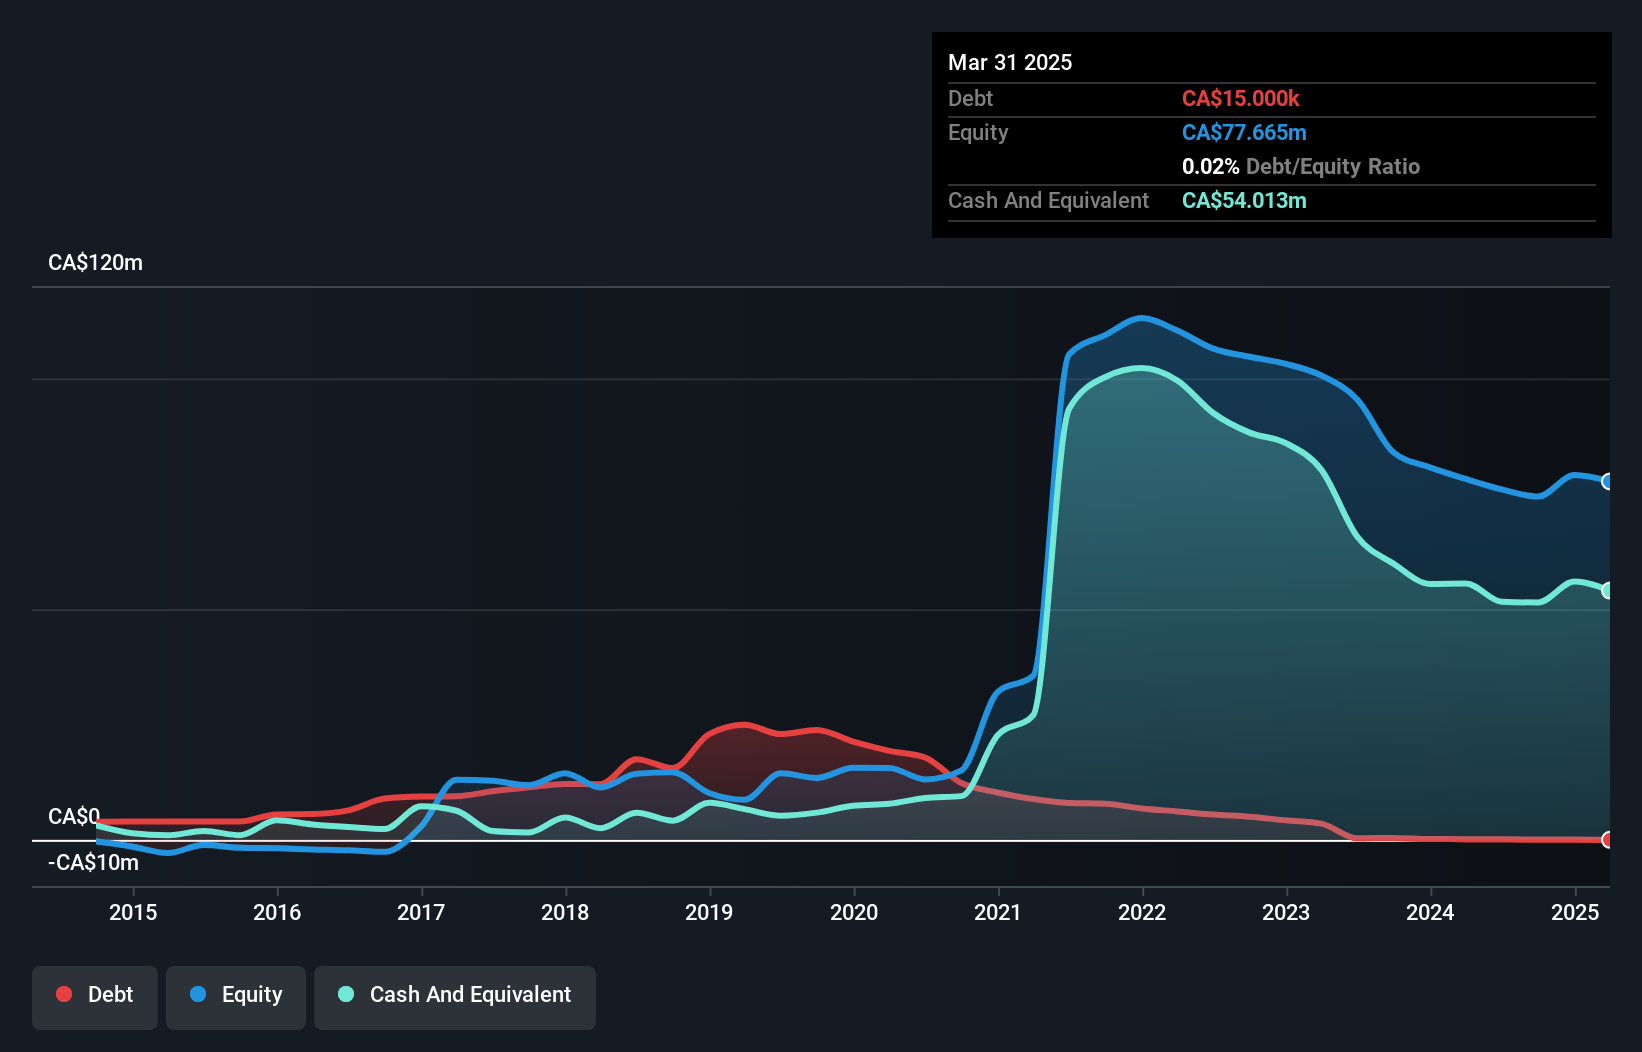
illumin Holdings Inc., with a market cap of CA$32.58 million, is trading at a significant discount to its estimated fair value and has stable short-term assets exceeding both its short- and long-term liabilities. Despite being unprofitable with a negative return on equity, the company reported improved second-quarter sales of CA$50.21 million and reduced net losses compared to the previous year. A strategic partnership with Audience Acuity enhances its digital media solutions by integrating advanced audience intelligence, potentially boosting campaign performance through more precise targeting. illumin's experienced management team supports its operational stability amidst high share price volatility.
- Click to explore a detailed breakdown of our findings in illumin Holdings' financial health report.
- Explore illumin Holdings' analyst forecasts in our growth report.
Western Energy Services (TSX:WRG)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Western Energy Services Corp. is an oilfield service company operating in Canada and the United States with a market cap of CA$133.04 million.
Operations: The company generates revenue from two primary segments: Contract Drilling, which accounts for CA$157.67 million, and Production Services, contributing CA$44.71 million.
Market Cap: CA$133.04M
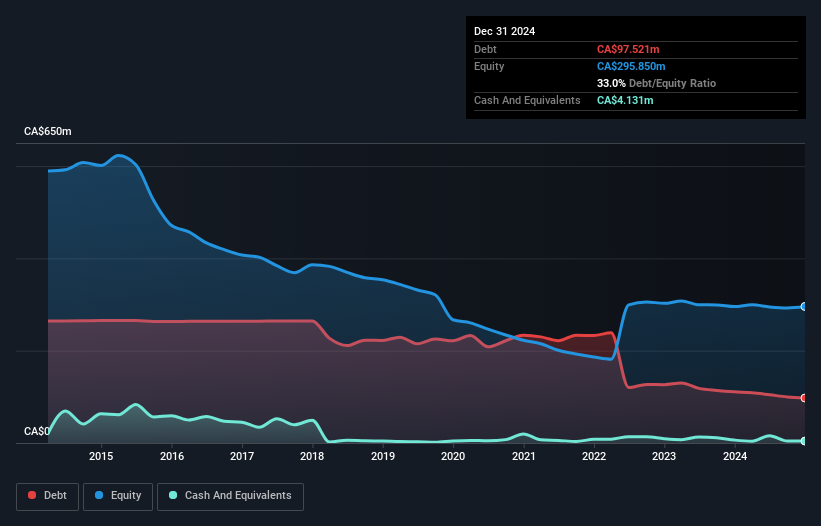
Western Energy Services Corp., with a market cap of CA$133.04 million, trades significantly below its estimated fair value, offering potential value to investors. Despite being unprofitable, it maintains a positive free cash flow and has sufficient cash runway for over three years. The company reported stable short-term assets exceeding its short-term liabilities but not its long-term liabilities. Recent earnings show a slight improvement in net loss compared to the previous year, with sales of CA$38.58 million for the second quarter and CA$93.83 million for the first half of 2026. The debt-to-equity ratio has improved significantly over five years.
- Jump into the full analysis health report here for a deeper understanding of Western Energy Services.
- Examine Western Energy Services' earnings growth report to understand how analysts expect it to perform.
Next Steps
- Get an in-depth perspective on all 356 TSX Penny Stocks by using our screener here.
- Ready To Venture Into Other Investment Styles? Uncover 21 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com