


EN
Does Coherent (COHR) Still Trade Near Fair Value After The Selloff?
Coherent has been on a dramatic ride in recent years, yet the latest pullback has many investors asking whether the current share price lines up with what its earnings can support. With the stock whipsawing alongside chip makers and AI hardware suppliers, the question now is how much of its AI optics story is already embedded in the valuation.
- Over the past 3 years, Coherent has delivered a very large share price gain of about 7x, which puts a lot of focus on whether its current earnings can carry that kind of move.
- Heavy investment in AI focused datacenter optics, including the PhotonLink platform and expanded capacity, can influence how quickly earnings grow relative to the cash the business is tying up today.
- Your read on Coherent is one view; the desks covering it have another. See what analysts think Coherent's shares could be worth.
The stock's next move may depend on whether today's valuation is adequately backed by Coherent's current and expected earnings power.
If you want to explore the same earnings question Coherent faces across a broader set of AI hardware companies, review 55 AI infrastructure stocks.
Where Does Coherent Sit on Earnings?
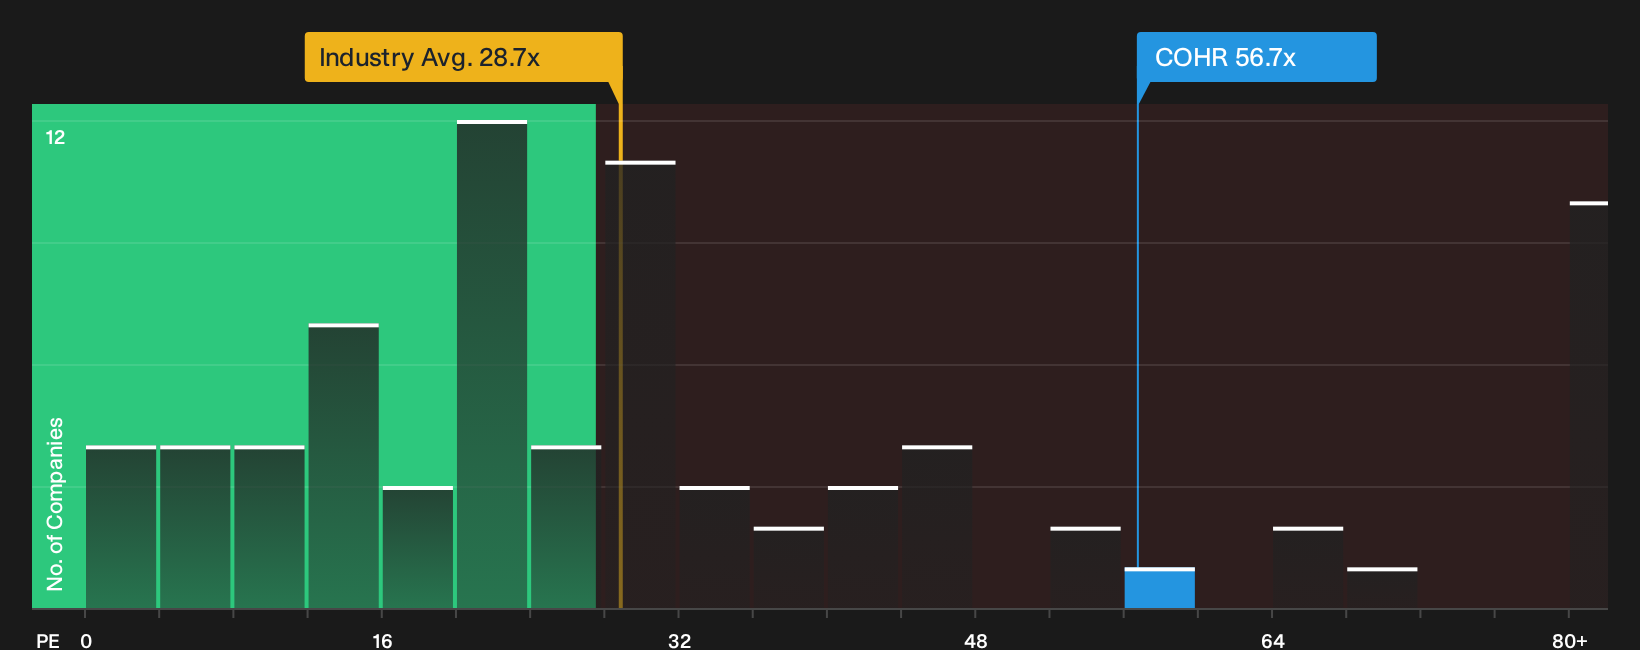
The P/E ratio fits Coherent because investors are focused on how much they are paying for every dollar of current earnings while the AI optics story builds out. On this lens, the stock trades on roughly 56.7x earnings, which is broadly in line with the modelled fair level for Coherent once its growth profile, margins, size and risk are taken into account. That fair yardstick sits between the wider Electronic industry on 28.7x and a peer set around 63.7x, so Coherent screens as neither heavily discounted nor stretched on this single metric.
Because the recent selloff in chip related names has been sharp, the key takeaway is that Coherent still carries a premium to the broader sector even though its P/E multiple is close to what the tailored model suggests is appropriate. For anyone weighing the stock, the question is whether current AI driven optics demand and the capital tied up to serve it justify paying a price that broadly matches that fair benchmark. Explore the numbers behind Coherent's P/E valuation.
The Coherent Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion leaves off and explain which growth, margin and earnings paths would need to unfold for Coherent to be worth materially more or less than the current share price, all housed on the Community page. Each scenario links a specific fair value estimate to a clear view of Coherent's potential catalysts and key risks so you can track over time which version of the story appears to be taking shape.
One of the top community narratives on Coherent: 45% undervalued
"Robust demand from AI and high-performance datacenters, plus key Apple contracts, is associated with growth and strengthening Coherent's core photonics and communications segments."
Discover why this Narrative puts Coherent at 45% undervalued.
Coherent’s valuation is only part of the story
Share price maths can look tidy, but the real leverage often comes from who is setting priorities inside Coherent, how those leaders are rewarded, and whether those incentives line up with shareholders. See who runs Coherent and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com