


EN
Is L E Lundbergföretagen (OM:LUND B) Trading At A Premium After Its Strong Run?
Fresh analysis of L E Lundbergföretagen (OM:LUND B) argues that the current share price embeds a premium to estimated intrinsic value, putting the company’s 31.5% three year total return under closer scrutiny.
Over the past year, L E Lundbergföretagen’s share price return of 13.55% year to date and 12.21% total shareholder return over twelve months point to steady, if unspectacular, momentum. Meanwhile, the modest 1.06% 90 day share price return hints that enthusiasm may be cooling as the market reassesses the premium to estimated intrinsic value.
Compare that premium story at L E Lundbergföretagen with other quality-focused financials by scanning our hand picked list of solid balance sheet and fundamentals (207 results) for potential alternatives in the same vein.
L E Lundbergföretagen now trades at what analysts see as a premium to estimated intrinsic value after a solid three year run. The key question is whether that premium still leaves enough potential upside to justify the risk.
Price-to-Earnings of 7.7x: Is it justified?
L E Lundbergföretagen trades on a P/E of 7.7x, which looks rich compared with its closest Swedish diversified financial peers, even though the share price already embeds a premium to intrinsic value estimates.
The P/E ratio links what you pay today to the earnings the group currently generates. For an investment company like L E Lundbergföretagen, which blends equity holdings, real estate, and forestry assets, that earnings multiple effectively reflects how the market weighs its mix of steady income, asset backing, and balance sheet risk.
Compared with local peers on 5.3x, the stock commands a clear premium, yet it trades below the broader European diversified financials average of 9.8x. That split suggests investors are paying up relative to the immediate Swedish peer set, while still assigning a lower tag than the wider regional basket. This may reflect the firm’s combination of low 10.8% return on equity, very strong historical earnings growth, and the higher risk funding structure flagged by its lack of customer deposits.
On valuation grounds the current P/E of 7.7x looks expensive versus domestic competitors but more restrained when set against the broader European group. The multiple points to a market that is pricing the stock at a premium without pushing it into extreme territory.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 7.7x (OVERVALUED)
Still, the premium argument for L E Lundbergföretagen could be challenged if the higher P/E multiple compresses toward Swedish peers, or if equity holdings face a broad valuation reset.
Find out about the key risks to this L E Lundbergföretagen narrative.
Another View: DCF flags a premium on L E Lundbergföretagen
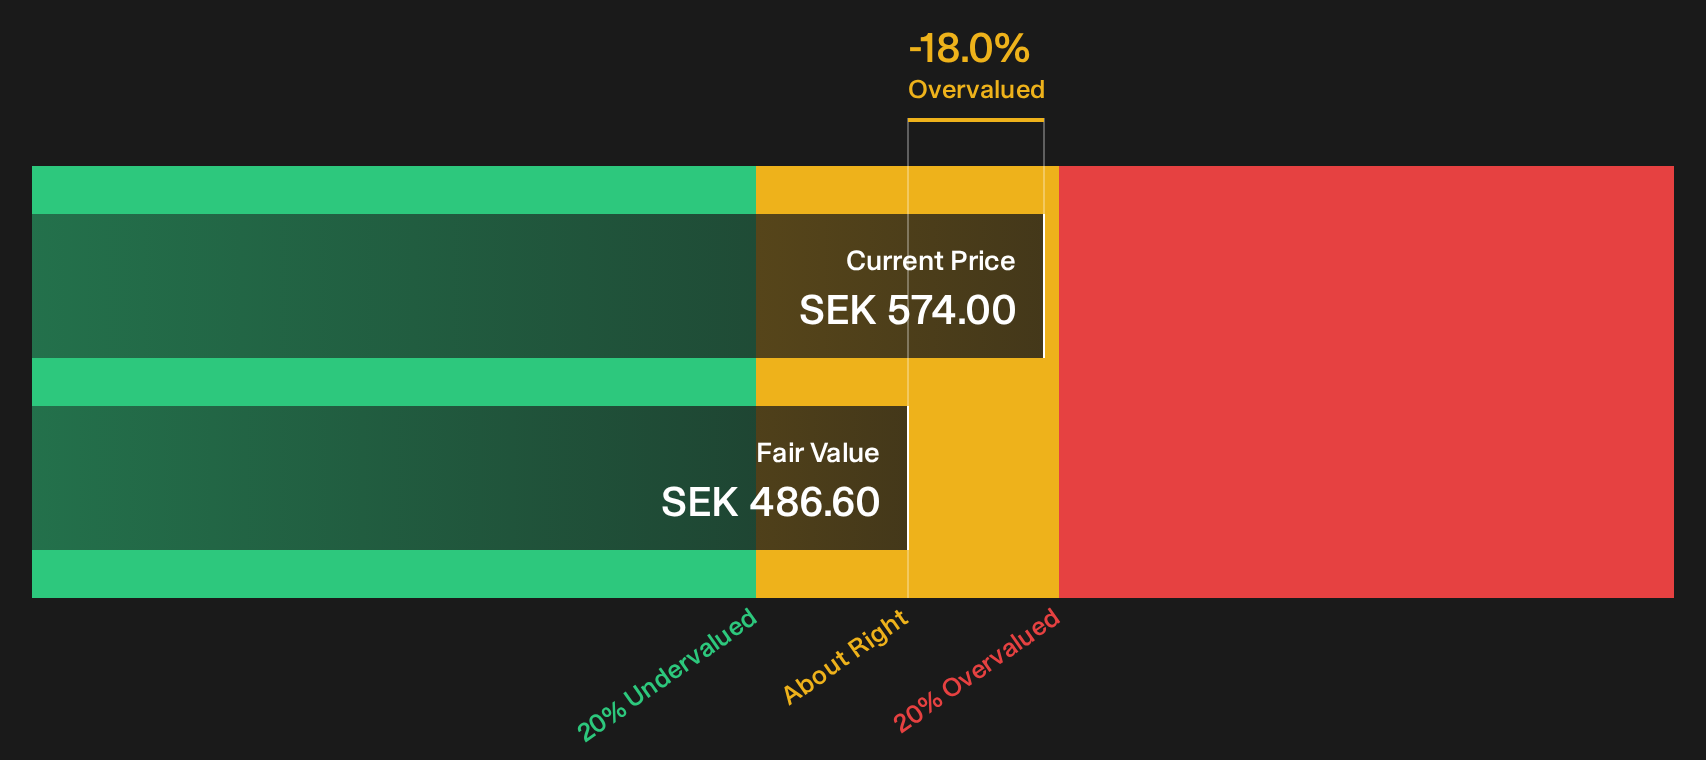
There is a different signal when you switch from earnings multiples to our DCF model. On that scorecard, L E Lundbergföretagen at SEK574 trades above an estimated future cash flow value of SEK486.60, so the shares screen as overvalued rather than fairly priced.
This gap means you are paying roughly SEK87 more than the SWS DCF model suggests the future cash flows support, which tightens the margin for error. The question is simple: if expectations cool, does the share price move toward cash flow value, or does cash flow need to catch up instead?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out L E Lundbergföretagen for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this all feels finely balanced, use it as a prompt to check the full data on L E Lundbergföretagen and decide quickly where you stand. To see what the optimism is built on, review the 2 key rewards
Looking for more investment ideas beyond L E Lundbergföretagen?
If L E Lundbergföretagen feels fully priced, using a focused stock screener can help you quickly surface fresh ideas that better fit your risk and return preferences.
- Target quality at a discount by scanning 195 high quality undervalued stocks that pair solid fundamentals with prices the market has not fully embraced yet.
- Lock in potential income streams by reviewing 224 dividend fortresses that combine higher yields with balance sheet support.
- Dial down portfolio stress by concentrating on 223 resilient stocks with low risk scores designed to emphasise resilient financials and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com