


EN
What Costain Group Holders Bought Into
For Costain Group shareholders, the return over the past year was 73.2%, including dividends. If you had been weighing a purchase back on 26 October 2025, you would have faced two sharply different analyst stories: one arguing government backed infrastructure and AI could justify a fair value 19% above the start price, the other warning of regulatory costs and fixed contracts, with a fair value 25% below. Which set of risks and possibilities would you have trusted more?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Costain Group. Zero in on 10 high quality undervalued stocks for companies trading below our estimates.
The Two Costain Group Stories Investors Had To Weigh
The shares cost £1.53 at the start of the period, and anyone looking at Costain Group then had to decide which of two very different narratives felt more reasonable.
The bullish case put Fair Value at £1.82, based on revenue growth of 8.1%, a profit margin of 3.3%, and a future P/E of 12.6x, with assumptions linked to government backed low carbon projects and AI driven efficiency.
The bearish view saw Fair Value at £1.15, using 3.3% revenue growth and a 3.3% margin with a future P/E of 8.1x, and highlighted rising regulatory costs and fixed price contract risk as key threats.
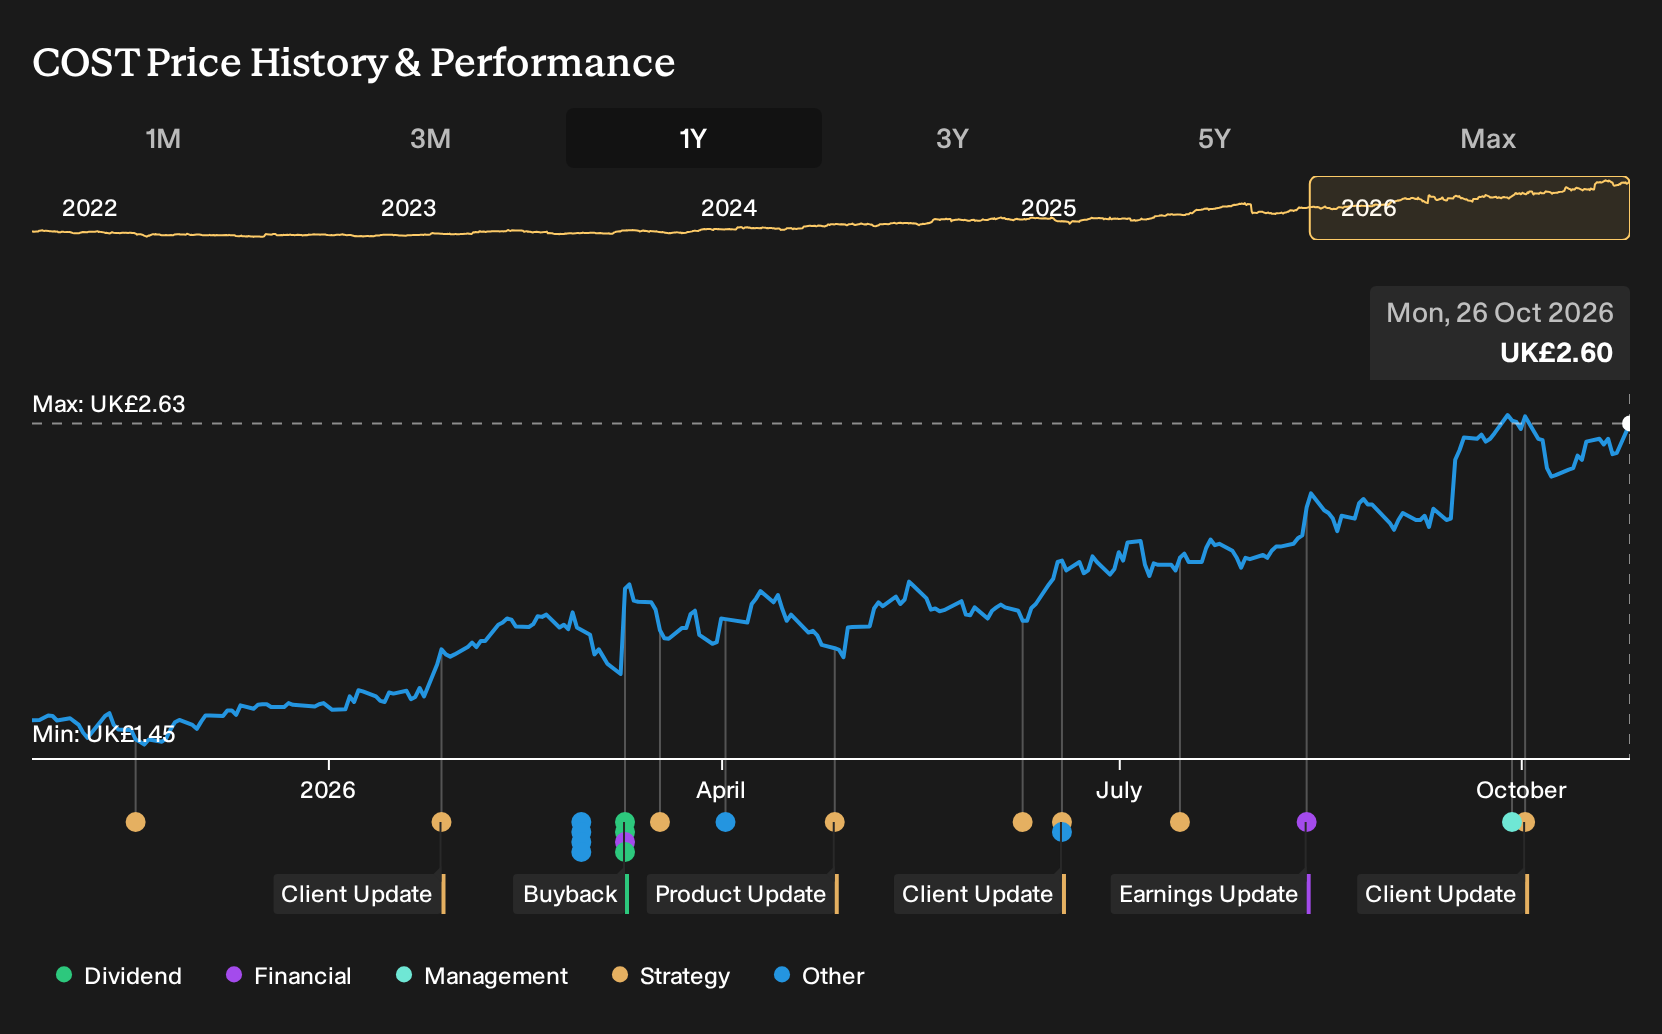
What The Results Changed For The Costain Group Debate
Costain Group reported total revenue of £543.1m and net income of £14.9m in H1 2026, compared with £525.4m and £14.2m in H1 2025, and net margin stayed at 2.7%. That pattern backed the optimistic story on steady profit and sales progress, yet the unchanged margin left the stronger profitability assumptions in both cases unproven. Overall the evidence cut both ways.
The clear hinge here was the margin forecast. When you test another stock, compare the projected profitability with the reported net margin, and watch whether that figure actually shifts in the direction the story assumes.
What Costain Group’s 73% Run Already Prices In
Costain Group now trades at £2.6 after a 73.2% gain over the past year, and the selected Narrative’s Fair Value sits below that quote. The author’s concern is not the order book; it is whether margins can hold up if big contracts become harder to execute cleanly.
A buyer today is effectively assuming that record forward work converts into delivery with operating margins at or above guidance. The selected Narrative asks how that assumption holds up if contract risk, cost pressure or execution hiccups keep margins closer to 4%.
"The main thing that has to go right is that Costain Group turns its record £7b forward work and growing positions in water, energy, nuclear and aviation into delivery at or above the guided 4% operating margin while keeping contract risk tightly controlled. The current valuation implies the share price already reflects multi year revenue visibility, a strong net cash position of about £170m and higher shareholder distributions, leaving limited room for disappointment if growth or margins soften."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking Beyond Costain Group
Costain shows how steady execution in complex projects can work in practice. You can also look one step away, to how those assets are powered.
Infrastructure needs reliable electricity when grids feel stretched and public plans move slowly. Some customers want on site power that avoids long approval queues.
One business focuses on fuel cell systems that convert various fuels directly into electricity. It aims to cut supply chain snags and keep projects running smoothly.
Its pitch leans on fast deployment, lower local impact and satisfied users. The open question is how quickly cautious decision makers embrace this option.
That argument has a Narrative and a number behind it. → See the company one Narrative values 89% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com