


EN
Dear Google Stock Fans, Mark Your Calendars for October 28
Alphabet (GOOGL) is heading into a closely watched earnings event, with investors set to focus on the tech giant’s third-quarter results on Oct. 28. Alphabet will report earnings after the market close, giving investors a fresh look at the performance of its core search and advertising businesses, Google Cloud, and its expanding artificial intelligence (AI) operations.
Wall Street expects Alphabet to deliver another quarter of strong growth. Estimates call for roughly $127.8 billion in revenue in Q3, up about 25% year-over-year (YOY), and EPS of around $2.94, compared with $2.87 a year earlier. Google Cloud will be a major focal point after revenue surged 82% YOY to $24.8 billion in Q2, while investors will also watch Search growth, Gemini adoption, and the returns on Alphabet’s massive AI infrastructure investments.
With expectations building around revenue growth, profitability, Google Cloud momentum, and AI monetization, the Oct. 28 earnings update could be important to understand whether Alphabet can maintain its position as one of the biggest winners of the AI era.
About Alphabet Stock
Headquartered in Mountain View, California, Alphabet is one of the world’s leading technology companies, with businesses spanning Google Services, Google Cloud, and innovative ventures such as Waymo and Verily. The company continues to strengthen its competitive position through significant investments in AI and cloud computing, two of its most important long-term growth drivers. With a market capitalization of approximately $3.87 trillion, Alphabet remains a global technology powerhouse and a prominent member of the “Magnificent Seven.”
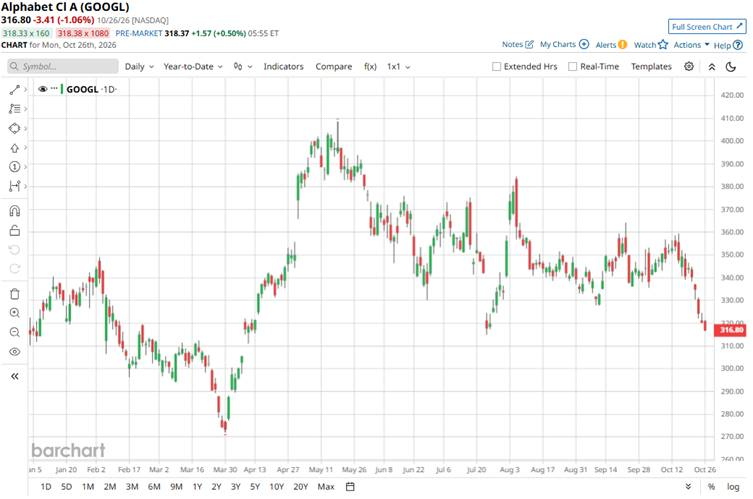
GOOGL stock has delivered a 19% gain over the past year, but its performance in 2026 has been far less impressive, with shares up just 2% year-to-date (YTD). More recently, the stock has come under significant pressure, slumping nearly 6% over the past five trading sessions and sitting about 22% below its 52-week high of $408.61 reached in May 2026. The weakness reflects growing investor concerns about the enormous cost of Alphabet’s AI expansion ahead of its Oct. 28 earnings report.
Alphabet’s Q2 capital expenditures surged to $44.9 billion, prompting the company to raise its 2026 capex outlook to a range of $195 billion to $205 billion. Meanwhile, free cash flow fell sharply in Q2.
Investors are weighing whether Alphabet can generate sufficient returns from those investments. Google Cloud remains a major bright spot, while Gemini adoption and AI-powered improvements to Search provide additional growth opportunities. However, higher energy and data-center costs are expected to pressure margins, while tougher Search comparisons and ongoing antitrust scrutiny add further uncertainty.
With GOOGL stock now trading well below its 52-week peak, the upcoming earnings report could be particularly important in determining whether the recent pullback represents a buying opportunity or a sign that investors want to see clearer returns from spending.
At 15.5 times forward earnings, GOOGL stock currently trades at a premium compared to the sector median but a discount to its own historical average.
Q2 Earnings Showed Strong AI-Driven Growth, But Spending Remains a Concern
Alphabet reported its Q2 fiscal 2026 results on July 22. Revenue increased 24% YOY to $119.8 billion, marking the company’s 12th-straight quarter of double-digit revenue growth. Operating income rose 30% to $40.8 billion, while operating margin expanded to 34% from 32%.
Net income available to common shareholders surged 298% YOY to $112.1 billion, compared with $28.2 billion in Q2 2025. Meanwhile, EPS jumped 294% to $9.11 from $2.31, topping expectations.
Alphabet’s core businesses continued to show strong momentum. Google Services revenue climbed 15% YOY to $94.5 billion, with Google Search and other revenue increasing 17% to $63.3 billion and YouTube ad revenue rising 13% YOY to $11.1 billion. Google subscriptions, platforms, and devices revenue grew 15% YOY to $12.9 billion, while Google Network revenue edged down slightly to $7.3 billion. The biggest growth engine was Google Cloud, which saw revenue surge 82% YOY to $24.8 billion, fueled by demand for AI infrastructure and solutions.
The quarter also highlighted the cost of Alphabet’s aggressive AI expansion. Capital expenditures reached $44.9 billion, with the vast majority directed toward technical infrastructure, while operating expenses increased 27% to $33.1 billion and R&D spending rose 32%. Alphabet generated $39.1 billion in operating cash flow during the quarter, but free cash flow came under pressure as AI infrastructure spending accelerated, turning negative at -$5.9 billion.
Furthermore, Alphabet raised its full-year 2026 capex guidance to $195 billion to $205 billion, up from its previous range of $180 billion to $190 billion. Management said the increase reflects the need to accelerate capacity expansion because demand for AI computing continues to exceed supply. Nevertheless, higher infrastructure investments will increase depreciation and data-center operating costs while likely keeping free cash flow under pressure.
Analysts forecast EPS of around $20.60 for fiscal 2026, reflecting a possible 91% YOY jump. However, they also expect a 27% YOY decline to $15.03 in fiscal 2027. Meanwhile, the consensus EPS estimate of $2.94 for Q3 indicates a rise of roughly 2% YOY.
What Do Analysts Expect for Alphabet Stock?
Most recently, Citizens analyst Andrew Boone maintained a “Market Outperform” rating on GOOGL stock but lowered his price target to $450 from $515. The target cut reflects growing concerns about execution risk and increasing competition for Google Search from AI-powered agents, which Citizens believes will require Alphabet to make another strategic pivot in its search business. On the other hand, BMO Capital analyst Brian Pitz recently maintained an “Outperform” rating on Alphabet stock and raised the price target to $480 from $465, signaling continued confidence in the company’s AI and cloud growth prospects.
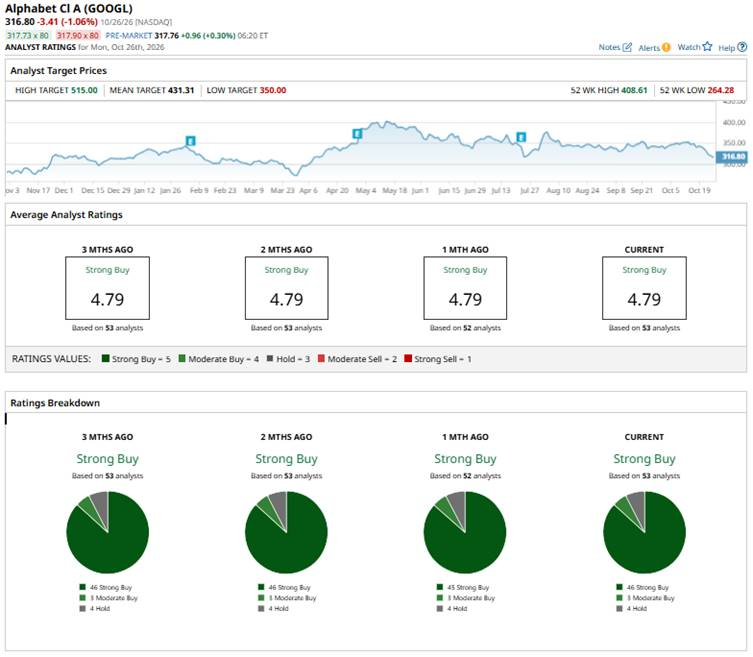
Overall, Alphabet has a consensus “Strong Buy” rating on Wall Street. Of the 53 analysts covering the stock, 46 advise a “Strong Buy,” three suggest a “Moderate Buy,” and four analysts have a “Hold” rating. The average price target of $431.31 indicates potential upside of 34% from current levels, while the Street-high target price of $515 suggests GOOGL stock could rally as much as 60% from here.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.