


EN
Allient (ALNT) After The Pullback Does The Margin Story Still Support Valuation
Allient (ALNT) is drawing attention after reports that end-market weakness has left sales essentially flat over the past two years, with modest free cash flow and returns on capital weighing on sentiment.
The recent pullback is hard to miss. Allient’s share price has declined 22.3% over the past month, following a 62.1% year-to-date share price gain. Meanwhile, the 1-year total shareholder return of 66.6% suggests that longer term momentum is still intact.
Scan beyond Allient’s recent swing and explore other industrial players facing similar end-market pressure with our curated list of list of solid balance sheet and fundamentals (24 results)
Allient has a solid motion control franchise, yet the share price just swung from a sharp year-to-date climb to a steep monthly drop. Does a 28.1x forward P/E still make sense after that move?
Most Popular Narrative: 24% Undervalued
Against Allient’s last close of $90.11, the most followed narrative anchors on a fair value of $118 that leans heavily on bookings, backlog and margin work already in motion.
Market confidence in sustained margin expansion from operational improvement and product mix shift is now underpinned by record Q2 2026 gross margin of 34.9% and a roughly decade high 10.2% operating margin, together with targeted STAN cost savings of US$10 million in 2024, US$6 million in 2025 and a further US$5 million to US$7 million in 2026, which could support future net margins and earnings.
See why 8 investors see Allient as 24% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the Allient story can break if record margins fade as restructuring costs linger, or if recent revenue softness persists, despite record bookings and backlog.
Find out about the key risks to this Allient narrative.
Another Look At Allient’s Valuation
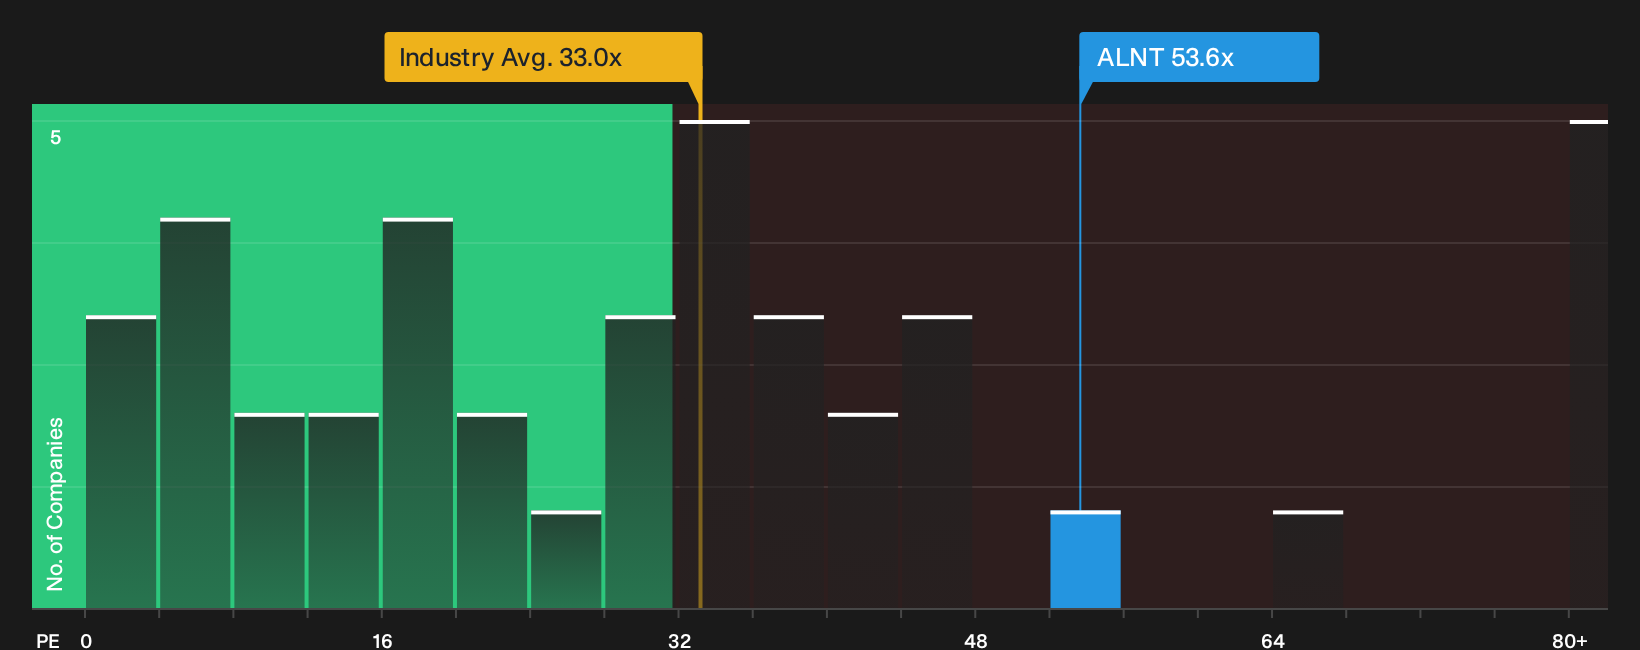
The DCF narrative suggests Allient is 24% undervalued relative to a fair value estimate of $118. Its P/E of 53.6x, however, tells a very different story. Compared with a fair ratio of 24.2x, the US Electrical industry at 33.3x and peers at 28.2x, investors are paying a hefty premium that raises the question of how much optimism is already reflected in the price.
Before relying on any single valuation measure, it can help to test what this higher P/E implies about future earnings strength and how quickly sentiment could shift if expectations cool. This is what our valuation breakdown is designed to show in more detail See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Allient narrative pulls in opposite directions, so treat this as a starting signal and move fast to test the data yourself. To balance the concerns against the upside potential, weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Allient?
You have already done the work on Allient, so do not stop short. Use the same focus to scan wider and spot opportunities others might miss.
- Target potential upside by zeroing in on companies that screen as 29 high quality undervalued stocks before the crowd pays attention.
- Strengthen portfolio stability by hunting for 30 resilient stocks with low risk scores that aim to keep volatility in check when conditions get rough.
- Get ahead of the market by combing through 21 high quality undiscovered gems that combine quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com