


EN
SLB (SLB) On Revenue Beat And Digital Growth Looks Undervalued Under The Leading Narrative
SLB (NYSE:SLB) is back in focus after its latest quarterly update, as revenue topped analyst expectations while management pointed to international growth, digital momentum, a firm subsea backlog, and fresh expansion moves in Canada.
Over the past year, SLB has combined strong headlines with strong numbers, with a 32.04% year to date share price return and a 50.38% one year total shareholder return. This suggests momentum has been building as investors react to revenue beats, new Canadian infrastructure for Meta, expanded seismic work offshore Brazil, and a reaffirmed quarterly dividend.
Scan other energy and infrastructure plays showing similar momentum to SLB by checking the hand picked 42 power grid technology and infrastructure stocks that are shaping the build out behind these kinds of contracts.
SLB looks like a solid operator with global reach, digital projects, and fresh contracts helping fuel a sharp share price run. The harder question now is whether that performance is already fully reflected in the valuation.
Most Popular Narrative: 15% Undervalued
SLB closed at $53.08, while the most followed narrative anchors fair value at $62.41. This implies upside based on its cash flow potential and capital returns plan.
The current valuation and guidance describe SLB’s share price as not fully reflecting the company’s classification of SLB as undervalued and bullish within this narrative. This view is based on the targeted US$4.5 to US$5.0 billion of data center revenue and US$700 to US$800 million of adjusted EBITDA in 2028, alongside plans to return more than US$4 billion a year to shareholders.
See why 167 investors see SLB as 15% undervalued.
Result: Fair Value of $62.41 (UNDERVALUED)
Still, the SLB story can change quickly if Middle East activity remains pressured or if data center and Kelvion integration targets prove hard to deliver.
Find out about the key risks to this SLB narrative.
Another View: What SLB’s P/E Is Telling You
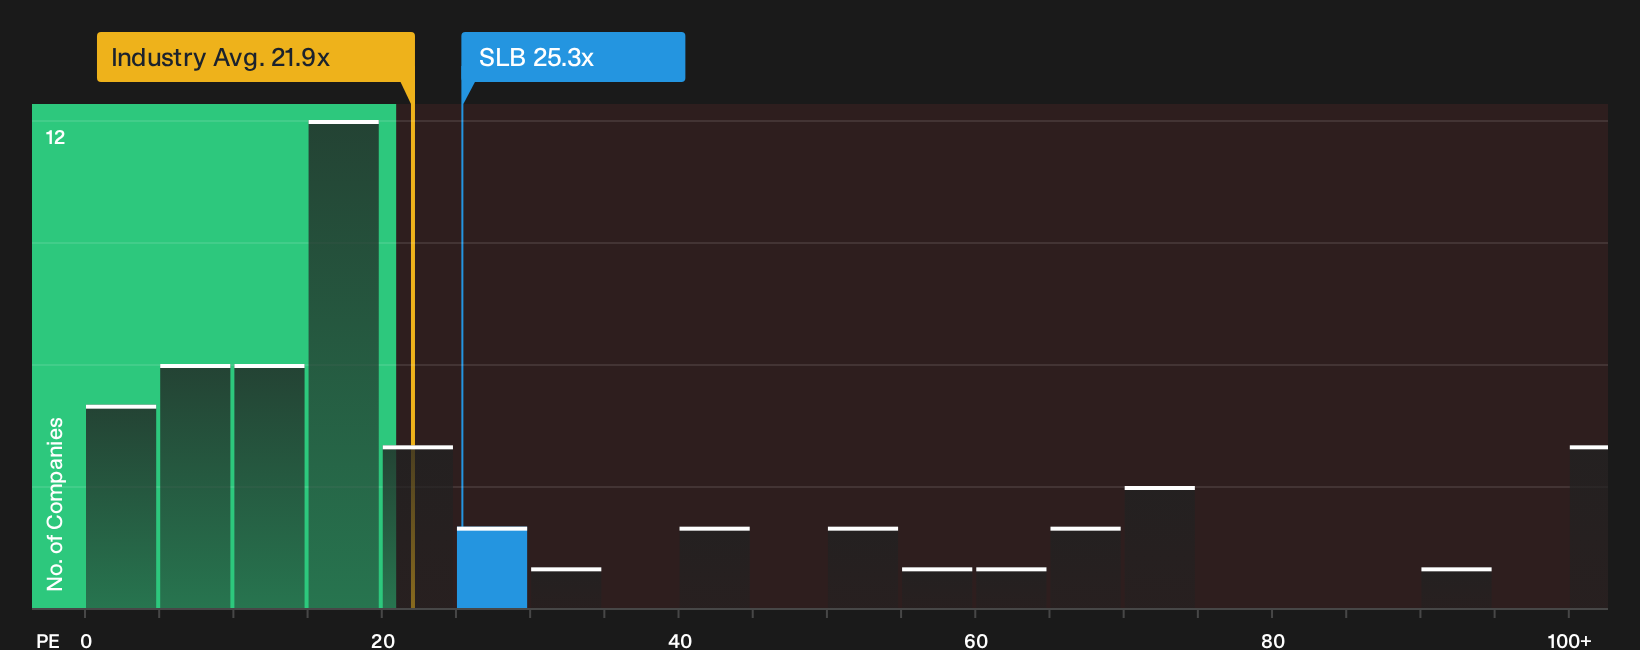
SLB screens as undervalued on fair value estimates, yet its P/E of 25.3x sits above the US Energy Services industry at 21.9x and above its own 23.7x fair ratio. That gap points to some valuation risk. If sentiment cools, does the multiple or the fair value move first?
For a closer look at what the numbers imply, including how this price compares with peers and that 23.7x fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With SLB, you are seeing both enthusiasm and some caution in the numbers and narratives. Consider acting promptly and testing the data yourself against your own thesis, starting with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SLB?
Do not stop your research with SLB. Broaden your watchlist using focused stock lists that filter for quality, resilience, and specific return profiles.
- Target potential mispricing by scanning a curated set of quality companies on the 29 high quality undervalued stocks that match strict cash flow and balance sheet filters.
- Lock in income potential by reviewing the 5 dividend fortresses and hunt for higher yielding businesses that pair payouts with resilient fundamentals.
- Build staying power into your portfolio by using the 30 resilient stocks with low risk scores to source companies with lower risk profiles before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com