


EN
DAIHEN (TSE:6622) Could Be 49% Overvalued As DCF Clashes With P E View
Recent share price moves have put DAIHEN (TSE:6622) on the radar again, with the stock up 2.6% in the latest session but down over the past month and past three months.
That 1-day share price gain comes after a tougher stretch, with the 7-day share price return down 4.69% and the 30-day share price return down 10.36%. Even so, DAIHEN still posts an 8.72% year-to-date share price return and a 1-year total shareholder return of 21.55%, suggesting longer term momentum has held up better than the near term pullback implies.
Scan beyond DAIHEN’s recent pullback and compare it with other industrials that pair solid operations with potential mispricing using the curated 16 high quality undervalued stocks.
Bulls see DAIHEN’s recent pullback as a chance to buy a stronger long term track record at a cheaper entry point, while bears see a valuation trap forming. Which side do the current numbers support?
Price-to-Earnings of 18.3x: Is it justified?
On the surface, DAIHEN trades on a P/E of 18.3x, which points to a richer tag than many Electrical peers despite the recent share price pullback.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors pay for each unit of profit. For a manufacturer of transformers, welding equipment, power systems, and industrial robots, earnings power and its consistency often sit at the center of how the market sets that multiple.
DAIHEN shows several ingredients that can support a higher earnings tag, including earnings growth of 5.5% per year over the past 5 years, a stronger 12.3% growth rate over the last year, and management guidance that feeds into forecasts of 18.6% annual profit growth and 11.9% annual revenue growth. That growth profile, combined with high quality earnings and improving net profit margins from 5.7% to 6.1%, helps explain why investors might be willing to pay a premium multiple now compared with many peers. The estimated fair P/E of 22.4x suggests the current 18.3x level could still be below where the market might eventually settle for this earnings stream.
Compared with the JP Electrical industry average P/E of 13.2x and a peer group around 15.7x, DAIHEN trades at a clear premium, signaling that the market is pricing in stronger profit expansion and relatively resilient profitability than for the wider group. The fair ratio model pointing to 22.4x is even more assertive, indicating a level the valuation could gravitate toward if current earnings quality and forecast growth play out as expected.
Explore the SWS fair ratio for DAIHEN.
Result: Price-to-Earnings of 18.3x (OVERVALUED)
Still, the upbeat P/E story for DAIHEN runs into clear risks if forecast profit growth disappoints or if sector sentiment shifts away from capital goods suppliers.
Find out about the key risks to this DAIHEN narrative.
Another View: Our DCF Model Paints A Harsher Picture For DAIHEN
The SWS DCF model points a different way for DAIHEN. On that measure, the stock at ¥2,318 trades above an estimated future cash flow value of ¥1,173.89. That indicates an overvalued signal and raises a simple question: Are you more comfortable relying on earnings multiples or projected cash flows?
Look into how the SWS DCF model arrives at its fair value.
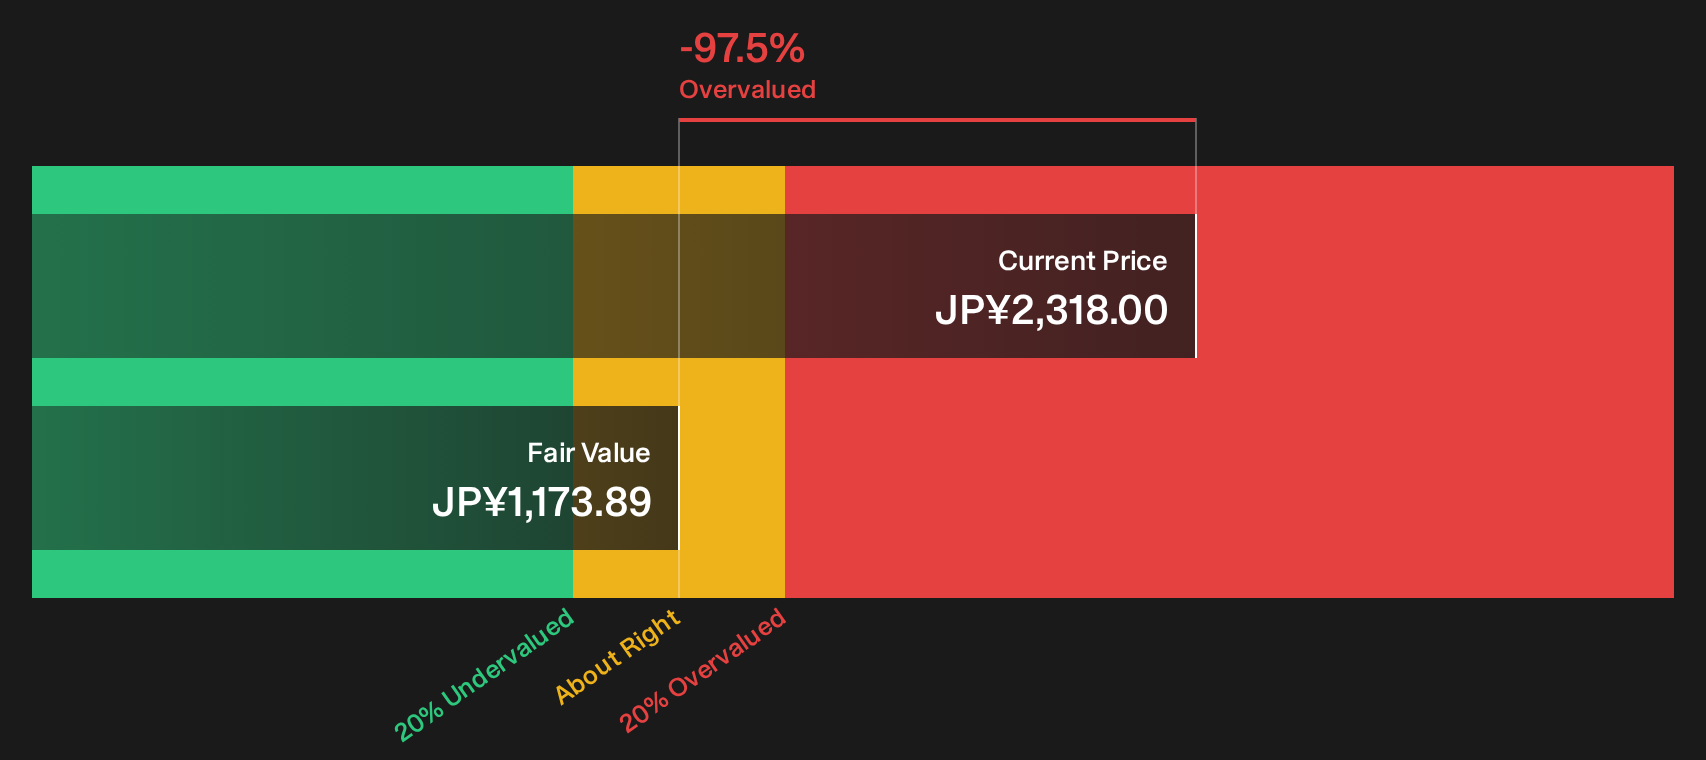
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DAIHEN for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on DAIHEN so far. If you want to move quickly and judge the balance of concerns and upsides for yourself, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DAIHEN?
If DAIHEN has you thinking harder about price, quality, and risk, broaden your watchlist now and give yourself more options before the next move.
- Target income-oriented opportunities by reviewing a curated set of yield focused companies through the 29 dividend fortresses.
- Look for financially sturdy businesses by scanning the list of solid balance sheet and fundamentals (23 results) that may be better positioned to withstand shocks.
- Identify potential emerging leaders by reviewing the 72 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com