


EN
Does New Note Offering Change The Bull Case For Main Street Capital Stock (MAIN)?
- Main Street Capital Corporation recently issued a new fixed rate, non convertible unsecured note offering that includes callable senior and subordinated bonds, expanding its fixed income funding options.
- The mix of callable senior and subordinated unsecured notes gives Main Street Capital additional flexibility to reshape its liability profile and funding costs over time.
- This article examines how Main Street Capital's decision to raise capital through fixed rate unsecured notes could influence its broader investment narrative.
Scan beyond Main Street Capital and explore other income focused opportunities by reviewing our hand picked 5 dividend fortresses that focus on sizeable yields and robust cash generation.
Main Street Capital Investment Narrative Recap
Main Street Capital shareholders need to believe the lower middle market and private loan engines can keep throwing off enough interest income and realized gains to support distributions, even as earnings per share have been under pressure and dividend income from portfolio exits has softened. The key short term swing factor is simple: Can new deals and fee streams fill the gap left by higher funding costs and less equity dividend flow?
The biggest risk sits on the liability side. Recent refinancings have already lifted interest expense, and the new fixed rate unsecured notes add more long term obligations. If portfolio yields, fair value marks or credit quality weaken at the same time, dividend coverage and net asset value resilience could come under more scrutiny.
The fresh fixed rate unsecured note issuance is the announcement that matters most here because it directly interacts with that higher cost funding base analysts have been flagging. A thicker layer of callable senior and subordinated debt can give Main Street Capital timing options around refinancing, but the coupons still feed into an already tight net interest margin picture.
For catalysts, attention turns to whether new lower middle market platforms and private loans can shoulder this more expensive capital stack without pushing payout ratios to uncomfortable levels. Execution on credit selection and nonaccrual control looks central now, since even modest deterioration would hit both fair value marks and interest income while the new notes keep interest expense fixed in place.
What The Analyst Forecasts Assume For Main Street Capital
Main Street Capital's current analyst framework points to forecast revenue of US$731.9 million and consensus earnings of US$375.5 million by 2029, which compares with earnings today of US$451.3 million and assumes revenue growth of 8.4% per year. This implies an earnings decline of US$75.8 million from the current base if those projections play out.
Uncover how Main Street Capital's fair value indicates a 13% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
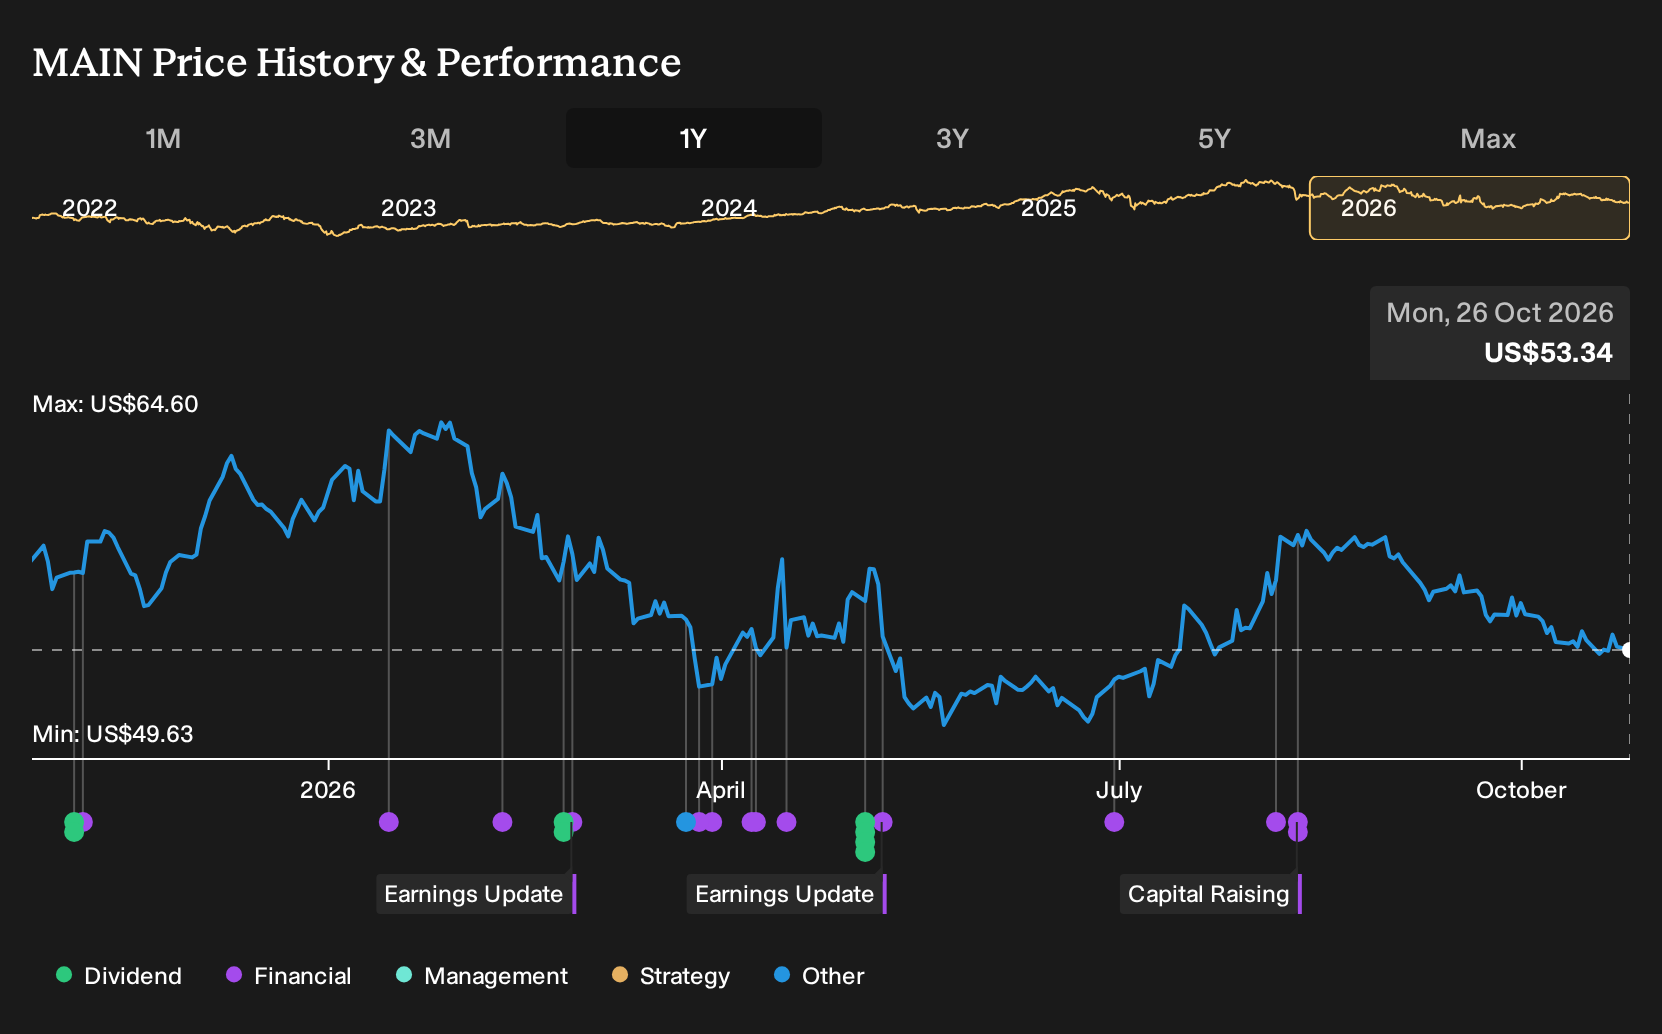
Three fair value estimates from the Simply Wall St Community cluster between about US$43.75 and US$60.33 per share, so you are seeing very different takes on Main Street Capital even before factoring in the new fixed rate notes. When you also consider funding cost pressure and shifting dividend income, exploring multiple viewpoints becomes essential.
Explore 2 other Main Street Capital fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Main Street Capital research is our analysis highlighting 1 key reward and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Main Street Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Main Street Capital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Main Street Capital?
If the Main Street Capital story has you rethinking where income, value and resilience might come from next, broaden your watchlist by running a few targeted screens on the Simply Wall St platform.
- For investors who want income potential with support from balance sheet strength, scan a curated list of solid balance sheet and fundamentals (24 results) that can help anchor a more conservative portfolio.
- If you prefer paying less for quality and are hunting for possible mispriced opportunities, check out a focused set of 29 high quality undervalued stocks that may line up better with your return goals.
- For those who want yield to carry more of the total return load, review a concentrated pool of 5 dividend fortresses that aim to blend sizeable payouts with underlying cash support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com