


EN
Could ROSA Knee Launch Alter The Investment Case For Zimmer Biomet Stock?
- Zimmer Biomet Holdings reported several robotics milestones, including the past launch of ROSA Knee with OptimiZe in India, the extension of its TMINI partnership with THINK Surgical, and the first reported ROSA Shoulder procedures at MemorialCare Orthopedic & Spine Institute in South Los Angeles County.
- Together with founding sponsorship of the Arthritis Foundation’s Comeback Club, these moves show Zimmer Biomet pushing deeper into digitally planned, robotic assisted joint replacement and engaging directly with post surgery patient communities.
- We will now look at how Zimmer Biomet’s ROSA Knee with OptimiZe launch could reshape the broader investment narrative around the business.
Zimmer Biomet Holdings Investment Narrative Recap
To own Zimmer Biomet Holdings, you need to believe its push into robotics and digital surgery can offset pricing pressure, higher manufacturing costs and near term margin strain. The recent ROSA Knee with OptimiZe launch in India and ROSA Shoulder progress both sit within that same technology story, but do not fundamentally change it yet.
The short term swing factor still looks like execution on Project Optima and the broader manufacturing and cost reset, while managing an 80 basis point pricing headwind and planned operating margin pressure in 2026. The biggest risk remains operational disruption or weaker profitability as the firm retools its network and commercial model.
The first ROSA Shoulder procedures at MemorialCare matter because they show Zimmer Biomet taking its robotics platform into more complex joints where precise planning and navigation are critical. Shoulder replacement is technically demanding, so early clinical adoption here is a useful proof point for the broader Technology & Data category story analysts already highlight.
For catalysts, real value comes if ROSA Shoulder and systems like TMINI feed higher technology mix and support the U.S. commercial overhaul rather than staying as isolated wins. The operational test is whether surgeons keep using these platforms at scale, supporting utilization, while the business still contains manufacturing costs and restructuring risk.
Zimmer Biomet Holdings is currently modeled on a 3.4% yearly increase in revenue, with analysts expecting earnings to move from US$806.7 million today to US$1.3 billion by 2029, a rise of about US$493 million. This outlook is supported by a revenue target of US$9.4 billion and consensus earnings of US$1.3 billion in that same 2029 forecast year.
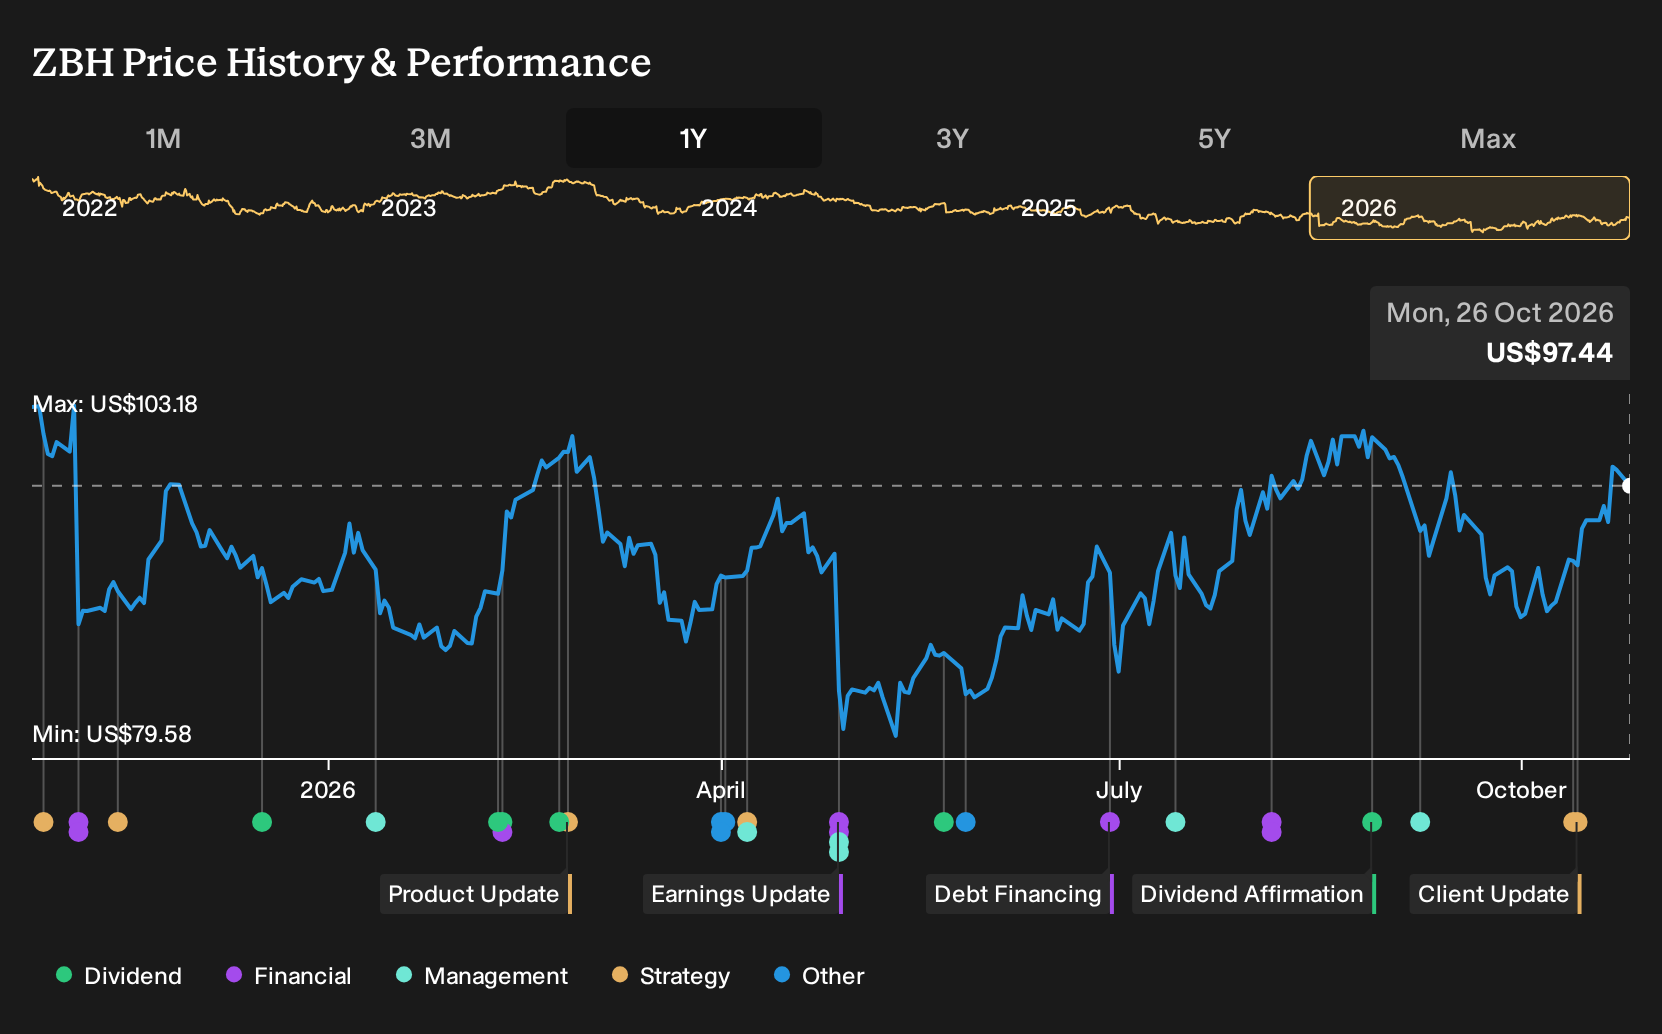
Uncover why Zimmer Biomet Holdings' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from about US$108 to US$266, so retail views on Zimmer Biomet Holdings sit far apart. You are seeing pre news opinions. Weigh that spread against pricing pressure, margin strain and robotics driven catalysts. Then explore several contrasting viewpoints before forming your own stance.
Explore 2 other Zimmer Biomet Holdings fair value estimates, including one that suggests it could be worth just $107.57.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgement.
- A great starting point for your Zimmer Biomet Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zimmer Biomet Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zimmer Biomet Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Zimmer Biomet Holdings?
If Zimmer Biomet Holdings has sharpened your focus on quality and risk, use that same lens to sort through a wider opportunity set with the Simply Wall St Screener.
- If capital protection is your priority, start with companies flagged as having resilient profiles through the 30 resilient stocks with low risk scores.
- If balance sheet strength matters most to you, filter for businesses that pass strict financial health checks using the list of solid balance sheet and fundamentals (24 results).
- If you prefer to hunt for underfollowed stories, cast a wider net with a curated pool of 21 high quality undiscovered gems that may not yet be widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com