


EN
How Inmazeb Deal Extension Will Impact Regeneron Stock (REGN)
- Regeneron Pharmaceuticals extended its BARDA agreement to supply additional Inmazeb Ebola treatment through 2031 for about US$270 million, while also reporting nearly four years of positive Phase 3 C-POST data for Libtayo in high risk cutaneous squamous cell carcinoma.
- These updates highlight how Regeneron Pharmaceuticals is pairing durable government procurement revenue from Inmazeb with expanding oncology evidence around Libtayo. This combination can influence the future mix between partnered and direct product sales.
- The next step is to examine how this extended BARDA procurement for Inmazeb could reshape Regeneron Pharmaceuticals broader investment narrative.
Regeneron Pharmaceuticals Investment Narrative Recap
To own Regeneron Pharmaceuticals, you need to believe the business can gradually rebalance away from heavy reliance on EYLEA, while keeping Dupixent growth and the late stage pipeline moving. The extended BARDA deal and fresh Libtayo data mostly affect smaller franchises, so they do not change the main near term swing factor, which remains retinal competition and pricing pressure.
The biggest operational risk still sits around EYLEA and potential share or price erosion, especially as rivals like Kodiak’s Zenkuda push longer dosing intervals. In the near term, the most important positive catalyst is continued execution across Dupixent, EYLEA HD conversion and late stage readouts. The new contracts and oncology readout look supportive, but not transformational.
The C POST update for Libtayo is the clearest link to the latest news, because it reinforces the oncology side of Regeneron Pharmaceuticals, while Inmazeb brings more stable government backed volume. Nearly four years of follow up with a 37% reduction in risk of death and consistent safety helps management argue that Libtayo has durable clinical value in high risk CSCC.
For you as an investor, this matters less for today’s earnings and more for future optionality. A stronger Libtayo label and broader use could help offset pressure if EYLEA volumes or pricing weaken and could also be relevant if litigation around earlier melanoma disclosures affects sentiment. Execution on label expansions and uptake in routine practice is the key thing to watch.
Regeneron Pharmaceuticals is currently modeled to grow revenue by 9.7% a year, with analysts projecting about US$20.5b in sales and US$6.5b in earnings by 2029, compared with earnings of US$4.3b today. This implies an increase of roughly US$2.2b in profit over that period.
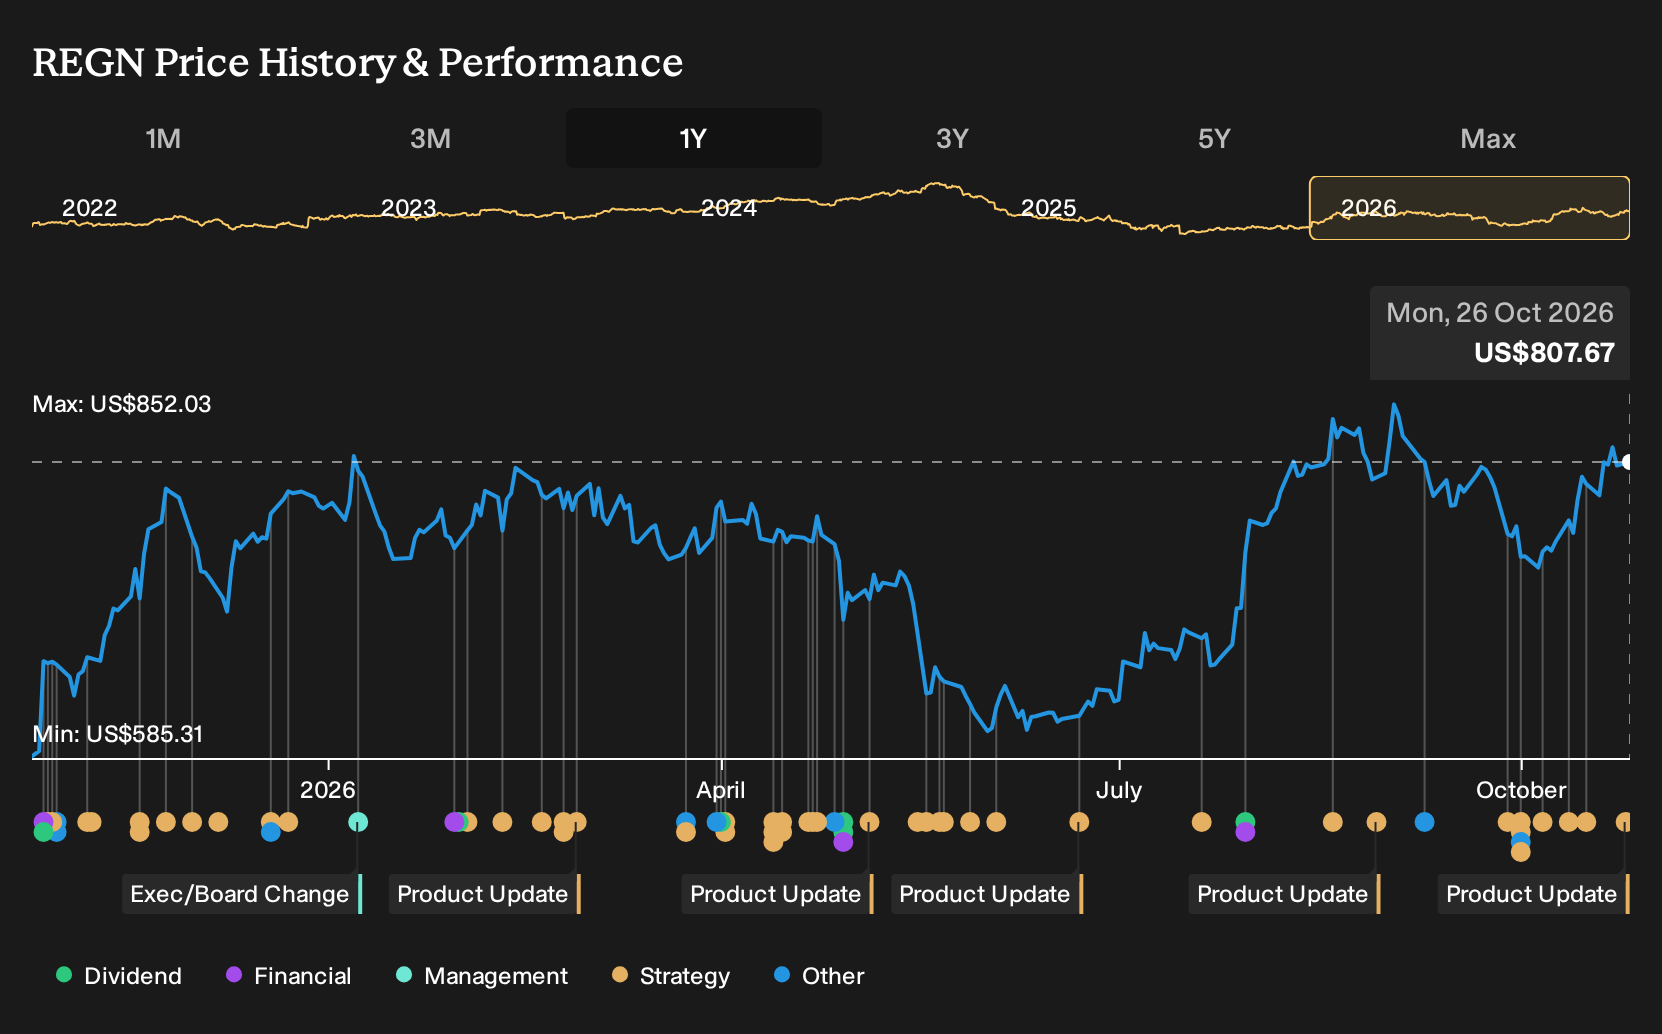
Uncover why Regeneron Pharmaceuticals' fair value indicates a 5% potential upside to its current price. This opportunity could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most bearish analysts focus on the risk that Regeneron Pharmaceuticals does not turn Libtayo and other oncology drugs into a large, durable franchise. Before this news, the lowest group only penciled in about US$18.5b of revenue and US$5.6b of earnings for 2029. You should treat that as one lens and compare several viewpoints.
Explore 4 other Regeneron Pharmaceuticals fair value estimates, including one that suggests it could be worth just $841.59.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Regeneron Pharmaceuticals research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Regeneron Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regeneron Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Regeneron Pharmaceuticals?
Once you are comfortable with where Regeneron Pharmaceuticals fits in your portfolio, it can help to compare it with other opportunities that offer different types of risk, income, or balance sheet strength. The Simply Wall St Screener is a practical way to surface those alternatives quickly and keep your watchlist fresh.
- If you want potential mispriced opportunities with stronger fundamentals, start with a focused group of 29 high quality undervalued stocks that may offer a better balance between quality and price.
- For investors who care most about resilience and capital preservation, filter for 30 resilient stocks with low risk scores that score well on stability and downside protection.
- If balance sheet strength is your priority, concentrate on companies from the list of solid balance sheet and fundamentals (24 results) to find businesses that rely less on heavy debt and more on internal firepower.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com