


EN
Third Quarter Earnings Could Be A Big Test For Alliant Energy Stock (LNT)
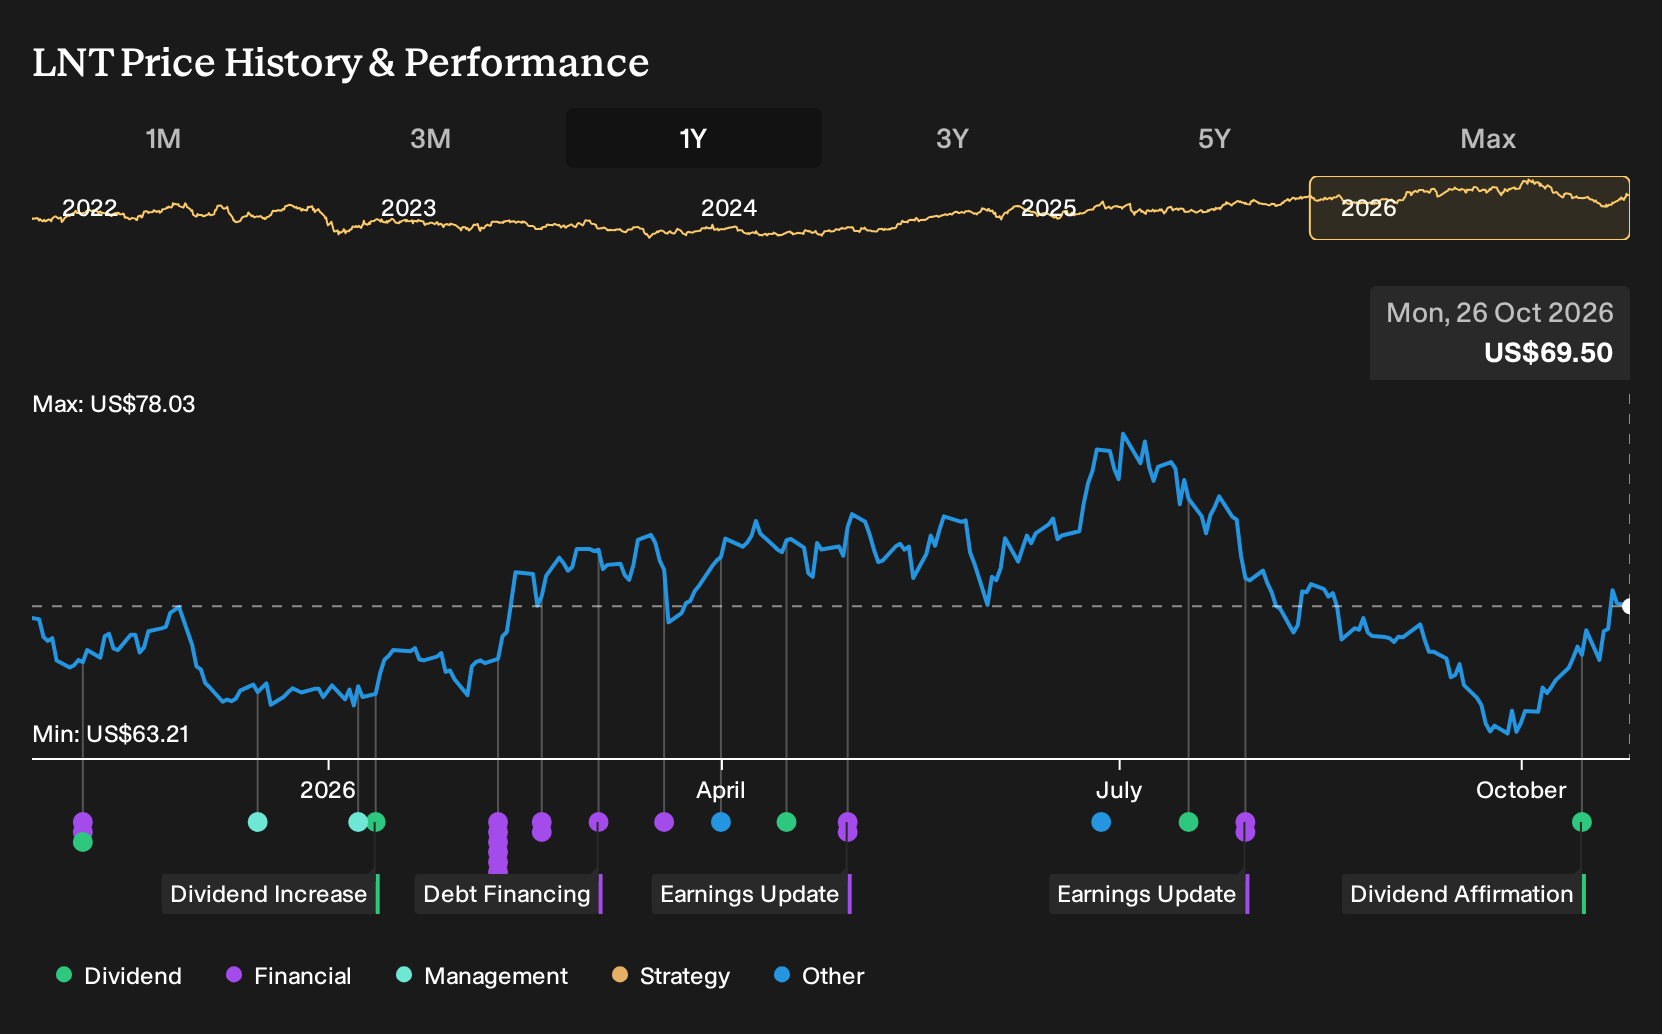
- Alliant Energy's board previously declared a quarterly cash dividend of US$0.535 per share, payable on November 16, 2026, to investors holding shares as of October 30, 2026, alongside continued investment in grid upgrades and data center related demand.
- The combination of steady dividend payments, large load agreements tied to data centers, and ongoing capital projects highlights how Alliant Energy is leaning on contracted customer demand to support its long term infrastructure build out.
- We will now look at how anticipation around Alliant Energy's third quarter earnings release could reshape the broader investment narrative.
Scan beyond Alliant Energy and line up other grid and data center beneficiaries using the hand picked 42 power grid technology and infrastructure stocks that are poised to capture similar long term infrastructure demand.
Alliant Energy Investment Narrative Recap
An investor in Alliant Energy needs to believe that regulated electric and gas operations in Iowa and Wisconsin can absorb a large wave of data center load without eroding profitability. The short term focus is on execution, and Q3 results on October 29 will show how higher operations, maintenance and financing costs are tracking against that incoming demand.
The most pressing risk is concentration around those hyperscale agreements and the capital required to support them. Any slowdown in data center ramp or further pressure from interest expense would work against the current build out plan. The latest dividend affirmation does not materially change that near term catalyst and risk balance.
The fresh US$0.535 quarterly dividend declaration matters mainly because it sits alongside a heavy capital plan. Alliant Energy is planning about US$13.4b of projects and expects to raise roughly US$500m in equity through 2029, so consistent cash returns to shareholders sit next to sizeable funding needs.
For you as a holder or potential holder, the key question is whether Alliant Energy can keep funding grid upgrades and generation for those large load customers while managing interest coverage and cash flow. The steady dividend track record can be viewed as a signal of confidence, but it also tightens the margin for error if costs continue to climb.
Alliant Energy's current analyst story points to about US$5.4b in revenue and US$1.2b in earnings by 2029, based on a 6.8% yearly increase in revenue and an uplift in earnings from US$817.0m today to that US$1.2b level over the same period.
Uncover why Alliant Energy's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from about US$68 per share to nearly US$94,478, which shows how far opinions on Alliant Energy can stretch. Some members focus on data center load and the US$13.4b capex pipeline. Others flag equity funding needs and higher expenses. Use that spread to test your own view.
Explore 2 other Alliant Energy fair value estimates, including one that suggests it could be worth just $67.53.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alliant Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alliant Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alliant Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alliant Energy?
If you want to pressure test your view on Alliant Energy, compare it with other opportunities that fit your risk, income, or balance sheet preferences using the Simply Wall St Screener. Mix and match different filters until you land on a shortlist that matches how you like to invest.
- For investors looking for smaller companies with higher potential, review 7 elite penny stocks with strong financials that meet strict financial quality checks instead of relying on hype.
- If valuation discipline is a priority for you, consider opportunities trading below their estimated worth by reviewing 29 high quality undervalued stocks that pair solid cash flows with stronger balance sheets.
- Those who put income first can focus on reliability by checking out 5 dividend fortresses that aim to combine higher yields with more durable payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com