


EN
Kinder Morgan (KMI) Could Be 9% Below Fair Value Following Earnings And Dividend Rise
Kinder Morgan (KMI) just paired higher third quarter earnings with a 2% dividend increase and fresh 2026 net income guidance, giving investors new data points on cash generation and capital returns.
That backdrop has kept Kinder Morgan in focus, with the share price up 10.37% over the past month and 22.48% year to date, even after a 1-day share price decline of 1.42%. Total shareholder return of 35.00% over the last year and very large gains over five years suggest longer term momentum has been strong.
Scan other energy infrastructure plays that show similar earnings and dividend momentum using our curated list of 29 high quality undervalued stocks.
After a move like that, Kinder Morgan now sits at a point where you have to ask a simple thing: Is most of the easy upside already cashed in, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 8% Undervalued
Kinder Morgan’s most followed narrative pegs fair value at $37 per share, ahead of the recent $33.94 close. This raises a clear question about whether the current price fully reflects its cash flow potential under those assumptions.
The current roughly $9.6b Board approved growth backlog, which is mainly tied to take or pay natural gas projects with an average in service date in the first half of 2028, is expected by management to translate into about $1.7b of incremental EBITDA over time, which could lift Kinder Morgan's future cash generation as these assets move from construction to operation.
See why 73 investors see Kinder Morgan as 8% undervalued.
Result: Fair Value of $37 (UNDERVALUED)
Still, the Kinder Morgan story can fray if big gas projects stall in permitting or if expansion spending pushes leverage toward the top of management’s target range.
Find out about the key risks to this Kinder Morgan narrative.
Another View: Kinder Morgan On Earnings Multiples
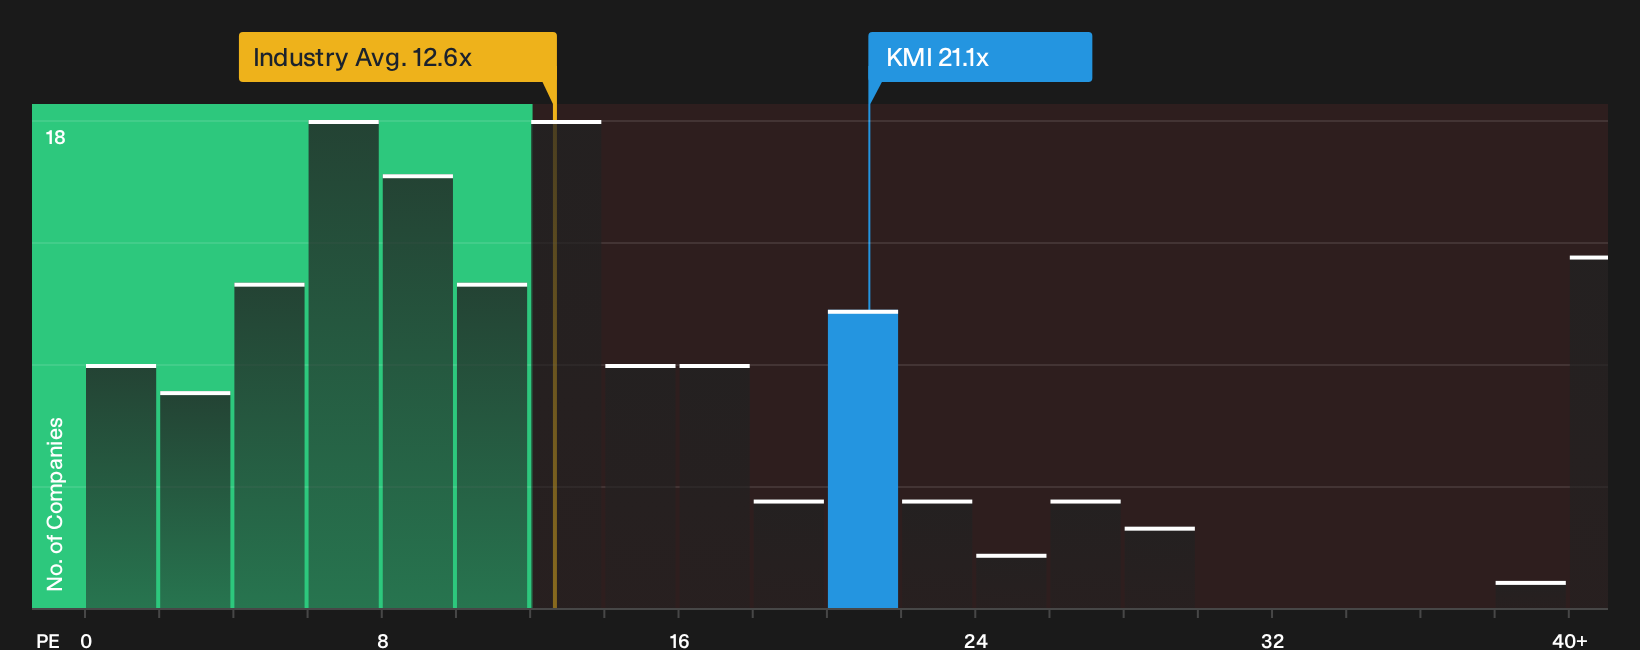
The DCF work suggests Kinder Morgan is undervalued, yet the P/E ratio tells a tighter story. Shares trade at 21.1x earnings, above the US Oil and Gas industry at 12.6x and above a fair ratio of 20x. That richer multiple points to less margin for error if growth cools.
For a closer look at what this gap between current P/E, peers and the fair ratio could mean for future pricing pressure or support, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Kinder Morgan draws mixed reactions in this piece, so treat it as a starting point and move fast to pressure test the data yourself. To see both sides of the argument in one place, review the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kinder Morgan?
If Kinder Morgan has sharpened your view on income and value, do not stop here. Broaden your watchlist now so you are not chasing the next move late.
- Target dependable cash generators by scanning a 5 dividend fortresses that focuses on high-yield companies with the financial strength to keep those distributions coming.
- Hunt for mispriced opportunities using a curated 21 high quality undiscovered gems that highlights strong fundamentals before they attract wider attention.
- Prioritise resilience with a 30 resilient stocks with low risk scores tailored to businesses that score well on financial stability and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com