


EN
Loop Capital Lowers Apple Stock Price Target on iPhone Shipment Concerns
Apple (AAPL) spent September showing off its newest devices, including a first-ever foldable iPhone. Following the event, AAPL stock rose roughly 10%, valuing the iPhone maker at a market cap of $5 trillion.
Apple’s biggest challenge this fall is to make devices that meet consumer demand. Apple’s former CEO Tim Cook had said demand is running ahead of what the company can build.
Loop Capital expects Apple to ship about 10% fewer iPhones than planned in the September and December quarters, due to supply chain issues.
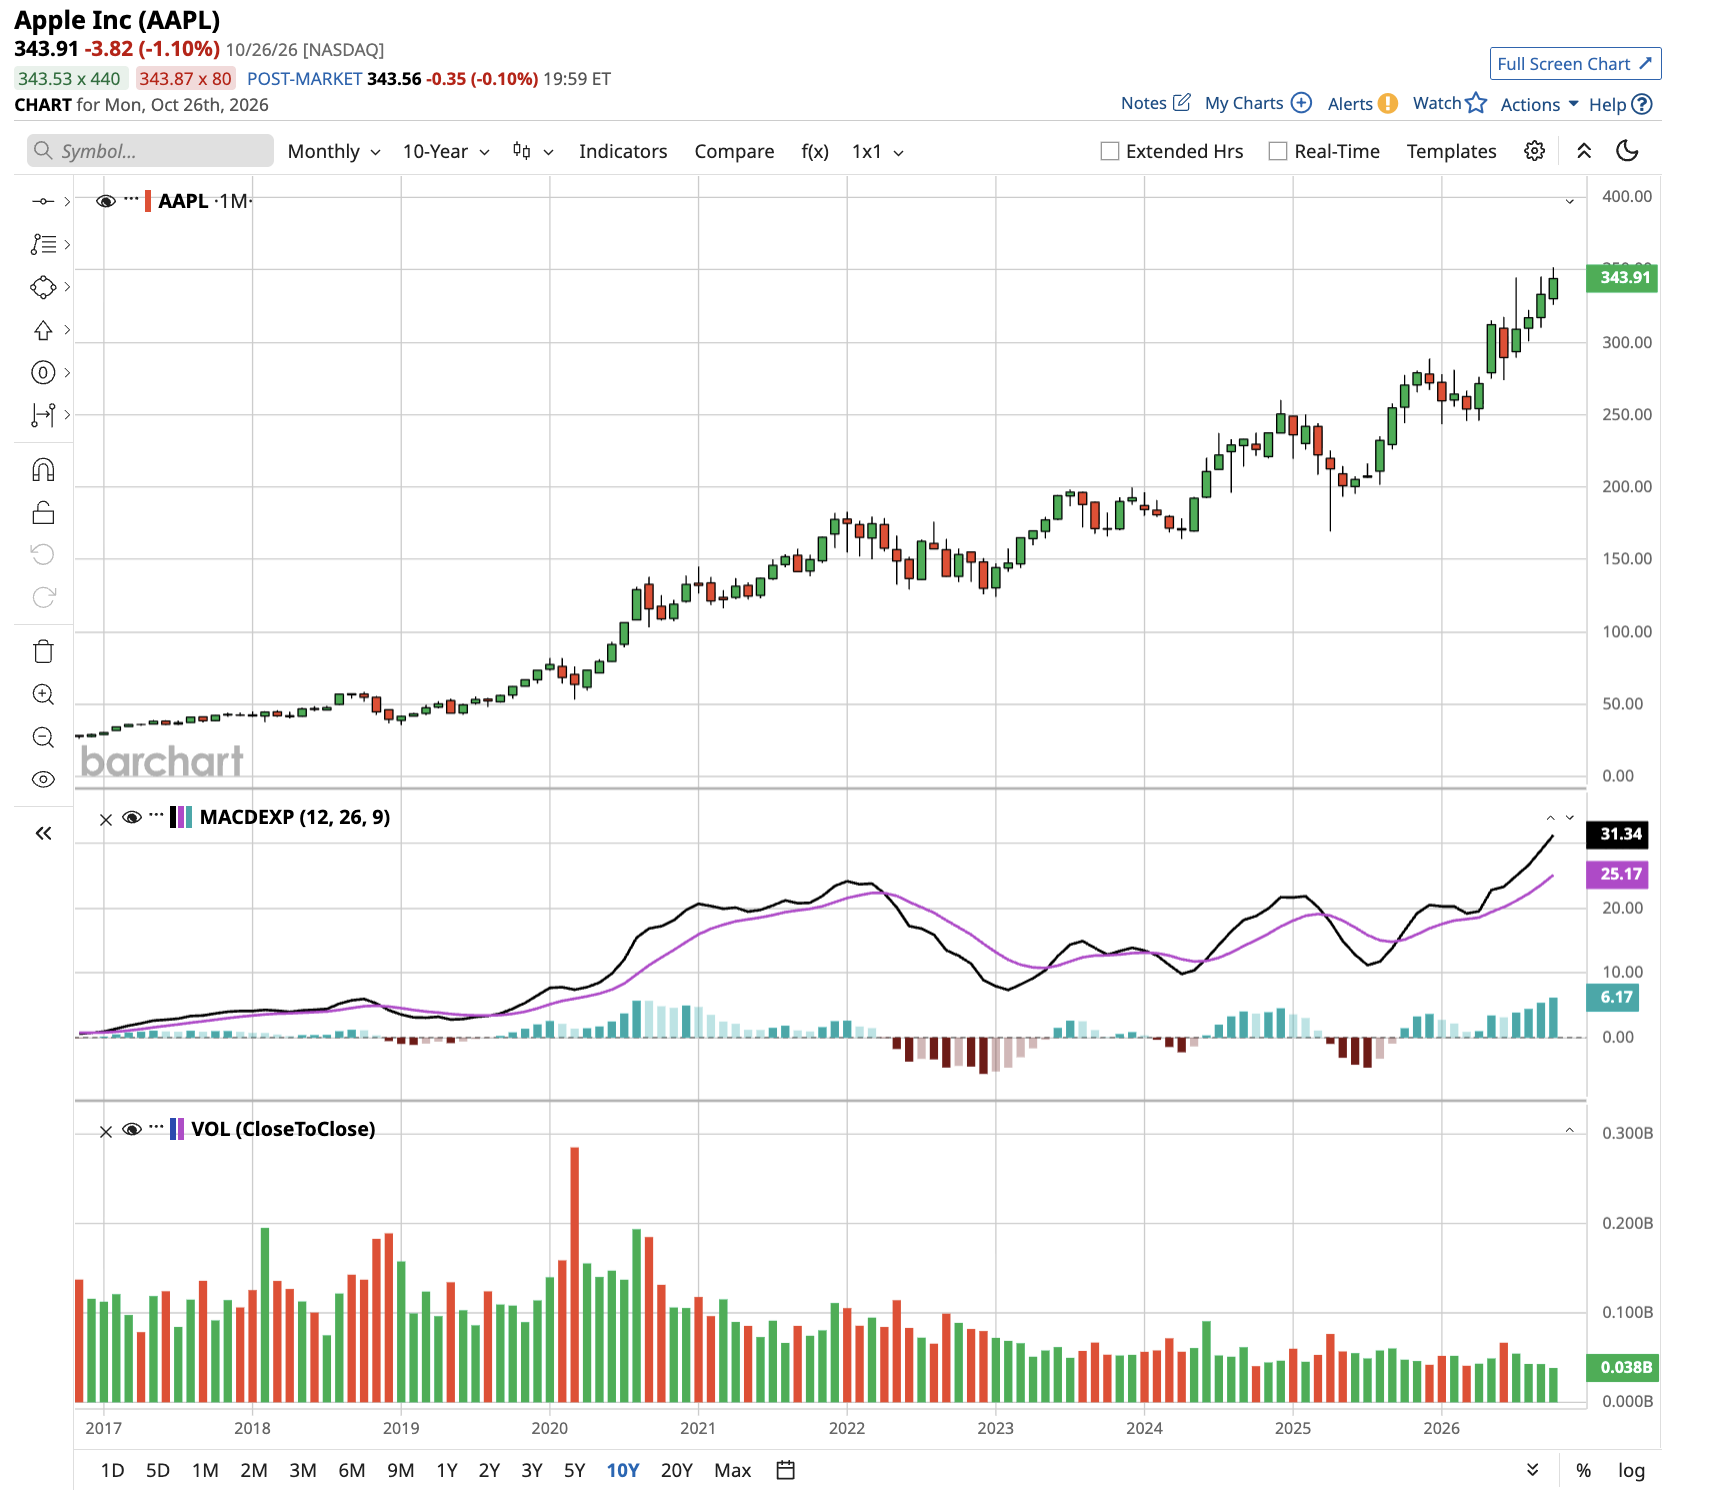
Apple's Blockbuster iPhone Year Runs Into Supply Limits
In fiscal Q3 of 2026 (ended in June), Apple reported revenue of $109.4 billion, an increase of 16% year over year.
iPhone revenue grew 22% to $54.3 billion, and Mac sales rose 29%. Cook called it the most popular iPhone lineup the company has ever had. However, Cook also said supply constraints would grow "significantly" in the September quarter, impacting device shipments across categories.
Management confirmed that chip capacity is the main limit and that the advanced manufacturing that makes Apple’s processors is tight. But he said the root cause is not a supplier failure, as Apple also underestimated demand.
Apple guided September quarter revenue growth of 9% to 11%, which is slower than fiscal Q3.
Apple also warned about memory, as Cook said the company paid more for memory in the June quarter than in the March quarter. Apple was forced to raise product prices due to higher input costs, which could negatively impact demand.
Loop Capital Cuts Apple Price Target to $330 From $370
Loop Capital downgraded Apple to “Hold” from “Buy” and also lowered its price target to $330 from $370. The firm trimmed its normalized earnings per share (EPS) estimate to $11.00 from $12.00. Normalized EPS smooths out one-time items to show steady earnings power.
Loop Capital applied Apple's median price-to-earnings (P/E) ratio of 30 times to the $11.00 estimate, which translates to a price target of $330. At the time of writing, AAPL stock trades at $344. Today, Apple trades at 37.5x forward earnings, above the 10-year average of 24.3x.
Apple’s EPS between 2016 and 2026 grew at a compounded annual growth rate of 15.6%. Over the next five years, EPS is projected to grow 12.5% annually.
Loop Capital had expected Apple to cut iPhone shipments by about 10% in the September and December quarters. It believed Apple would win those units back through 2027. Now, the firm says that no longer appears to be the case.
Memory Costs Could Squeeze Apple's Profit Margin
Loop Capital also flagged gross margin risk as memory prices keep surging.
Company gross margin was 50.1% in the June quarter as Apple said tariff refunds boosted that figure by about two percentage points. For the September quarter, Apple expects gross margin between 47% and 48%, which includes about one point of boost from tariff refunds.
Apple now trades at 37x earnings, a five-year high, according to Loop Capital. Basically, investors are paying more for a company that is shipping fewer phones.
Loop Capital still likes Apple's long-term share gains and its Services business. Services revenue hit $30.7 billion in the June quarter, up 12% year over year. But the firm says the big tech stock needs a fundamental catalyst reset after its recent run.
Wall Street Stays Split on Apple's iPhone Demand
IDC reported a 22% drop in global smartphone shipments in the September quarter tied to rising memory costs, which impacted profit margins across the smartphone sector.
Loop Capital is not alone in watching iPhone demand. Other analysts have weighed in with very different views, according to Investing.com.
- JPMorgan: An Overweight rating and a $360 price target. It noted preorders for the new iPhone Duo pushed delivery times into next year. The firm revised its 2026 iPhone Duo volume projections.
- UBS: A “Neutral” rating and a $296 price target. Its data showed shorter iPhone wait times than last year. Pro wait times were shorter in Europe and Japan but longer in the U.S.
- KeyBanc: An “Underweight” rating and a $250 price target. It cited concerns about upgrade intentions after a consumer survey. It also noted a 44% rise in indexed spending in September, driven by interest in the iPhone 18.
Out of the 40 analysts covering AAPL stock, 19 recommend “Strong Buy”, three recommend “Moderate Buy”, 15 recommend “Hold”, one recommends “Strong Sell”, and two recommend “Strong Sell”.
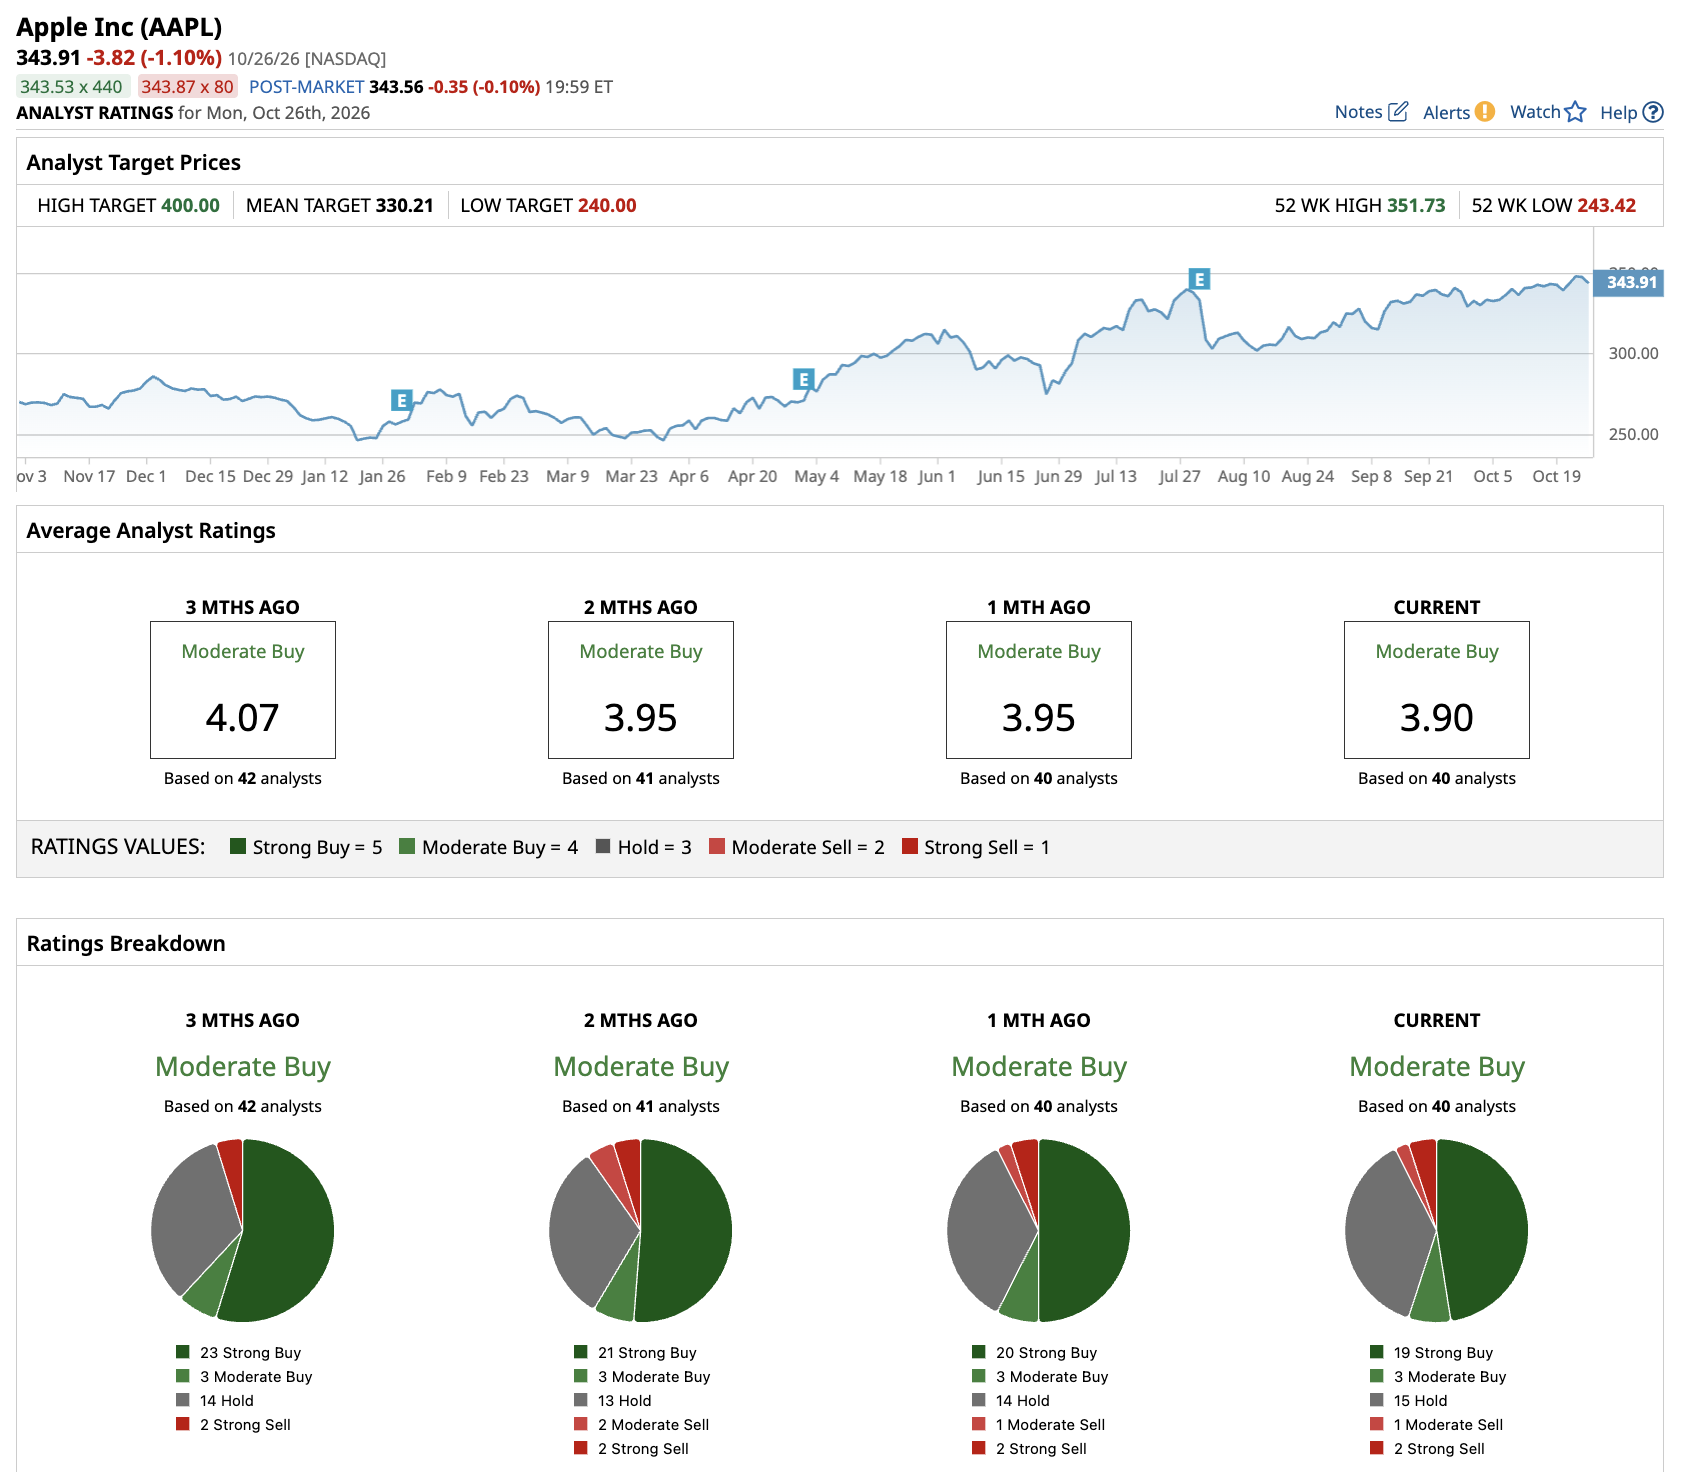
The average Apple stock price target is $330, below the current price of $344.
What Apple Investors Should Watch Next
The setup is easy to follow. Demand is strong, and supply looks tight while input costs are elevated. Apple's iPhone Duo starts at $1,999 and recently went on sale. Long delivery times could be a sign of strong interest but could also test buyers' patience.
Parekh said Apple will not give guidance beyond the September quarter. So, investors must wait for the next earnings report for clues on December. Loop Capital's message is short. Great products do not guarantee a rising stock. Apple now has to deliver enough of them, at a healthy margin, to justify a premium price.
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.