


EN
PARK24 (TSE:4666) Could Be 41% Undervalued As Data Breach Cuts Profit Outlook
PARK24 (TSE:4666) cut its full year profit outlook after a personal data breach led to expectations of an extraordinary loss and customer compensation costs, while sales and operating profit guidance stayed unchanged.
Investors have already been reassessing PARK24 in recent months, with the share price down 11.5% year to date and about 9.1% lower over the past 30 days, even though the 1 year total shareholder return of 2.1% and 3 year total shareholder return of 10.4% point to a more resilient longer term picture as the latest guidance cut adds a fresh layer of perceived risk around cybersecurity costs.
Position your portfolio for risks like the PARK24 data breach by reviewing companies on our 22 resilient stocks with low risk scores, which focuses on more resilient balance sheets and lower overall risk profiles.The cyber hit has dented PARK24’s earnings path and knocked confidence, yet the longer term return record is not broken. Do the current figures still justify taking on this new layer of risk?
Preferred P/E of 7.4x for PARK24: Is it justified?
PARK24 last closed at ¥1,831 and is described as trading at good value, with a P/E of 7.4x compared with peers and wider industry averages. That low earnings multiple sits alongside an intrinsic value estimate of ¥3,111.48 based on future cash flows, which frames the current quote as heavily discounted relative to the SWS DCF model.
The P/E ratio compares what you pay per share with the profit that PARK24 generates per share. For a parking and mobility operator with established earnings and a history of profit growth over the past five years, this is a straightforward way to see how the market is pricing its current and expected profitability.
At a P/E of 7.4x, the stock is described as good value against both its Commercial Services peers on 13x and a fair P/E estimate of 11.7x. That gap suggests investors are assigning a much lower price to each yen of earnings than the modelled fair ratio points to. This gap could close if sentiment around debt levels, forecast earnings declines and the recent data breach risk improves over time.
Explore the SWS fair ratio for PARK24.
Result: Price-to-earnings of 7.4x (UNDERVALUED)
Still, data breach costs and any further slowdown in net income growth could pressure confidence in PARK24 and keep that low P/E in place.
Find out about the key risks to this PARK24 narrative.
Another view on PARK24’s value
The P/E story paints PARK24 as cheap, yet the SWS DCF model also points to a much higher intrinsic value of ¥3,111.48 versus the current ¥1,831 share price. Both methods lean in the same direction. The real question is whether you trust the cash flow assumptions behind that gap.
Look into how the SWS DCF model arrives at its fair value.
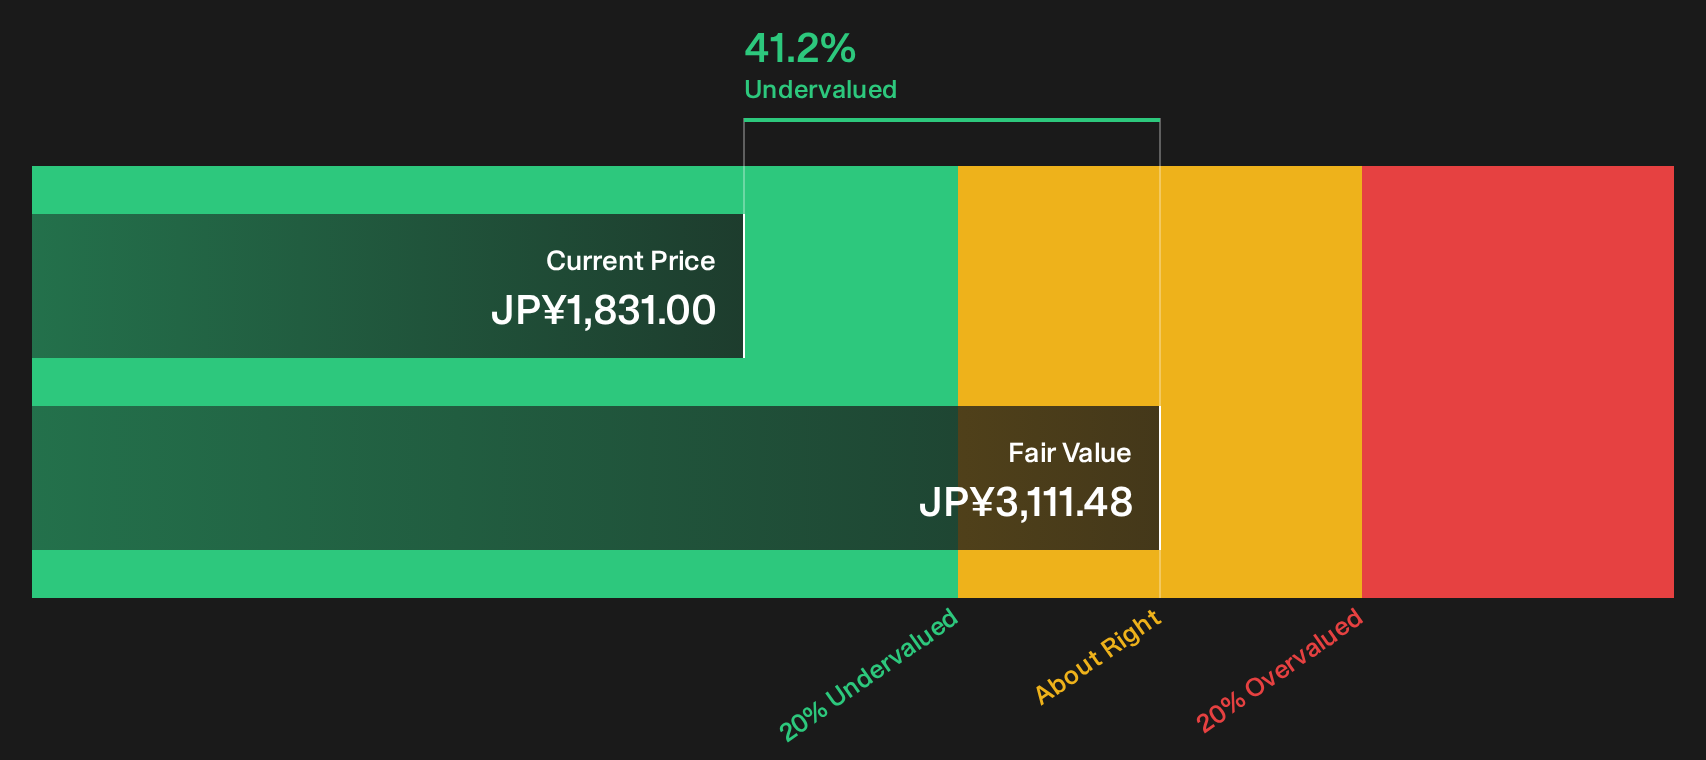
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PARK24 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about PARK24 after this guidance cut and data breach? Act while the information is fresh and form your own view with the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond PARK24?
If PARK24’s situation has sharpened your focus on risk and opportunity, do not stop here. Broaden your watchlist and test fresh ideas with targeted screeners.
- Spot potential mispricings early and review companies trading on attractive valuations with the 16 high quality undervalued stocks.
- Build a steadier income stream by focusing on reliable payers listed in the 29 dividend fortresses.
- Strengthen capital protection by filtering for companies with healthier finances using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com