


EN
IDEXX Laboratories (IDXX) Ahead Of September 2026 Earnings Has Valuation Back In Focus
IDEXX Laboratories (IDXX) is in focus as Wall Street looks ahead to its September 2026 quarter report. Expectations center on higher earnings and revenue, and optimistic sentiment is drawing fresh attention to the stock.
Recent trading has been more upbeat, with a 1-month share price return of 9.81% and a 7-day gain of 2.59% at a last close of US$570.21. However, the stock is still down 14.89% on a year to date share price basis and 11.92% on a 1-year total shareholder return, which suggests short term momentum is improving while longer term holders have faced a tougher stretch.
Spot emerging earnings stories that could follow IDEXX Laboratories with a curated set of 21 high quality undiscovered gems that may be poised for their own rerating moments.After a sharp short term rebound but a tougher 1-year stretch, the question around IDEXX Laboratories now hinges on simple trade offs. Does the current valuation still leave enough upside to justify the risk buyers take from here?
Most Popular Narrative: 19% Undervalued
At a last close of $570.21 versus a most-followed fair value of about $701.33, the current IDEXX Laboratories price sits below what that framework implies, which puts attention firmly on whether its recurring diagnostics engine can justify the gap.
Rapid adoption of platforms such as inVue Dx, Catalyst, and Cancer Dx is now supported by 11% year over year VetLab installed base growth and early inVue Dx utilization that already sits within the targeted annual recurring revenue range per instrument. This can deepen IDEXX Laboratories consumables revenue and support gross margin resilience.
See why 29 investors see IDEXX Laboratories as 19% undervalued.
Result: Fair Value of $701.33 (UNDERVALUED)
Still, softer U.S. clinic visits and heavier spending on expansion and AI projects could pressure IDEXX Laboratories margins and weaken the recurring diagnostics thesis if progress stalls.
Find out about the key risks to this IDEXX Laboratories narrative.
Another View: What IDEXX Laboratories’ P/E Is Telling You
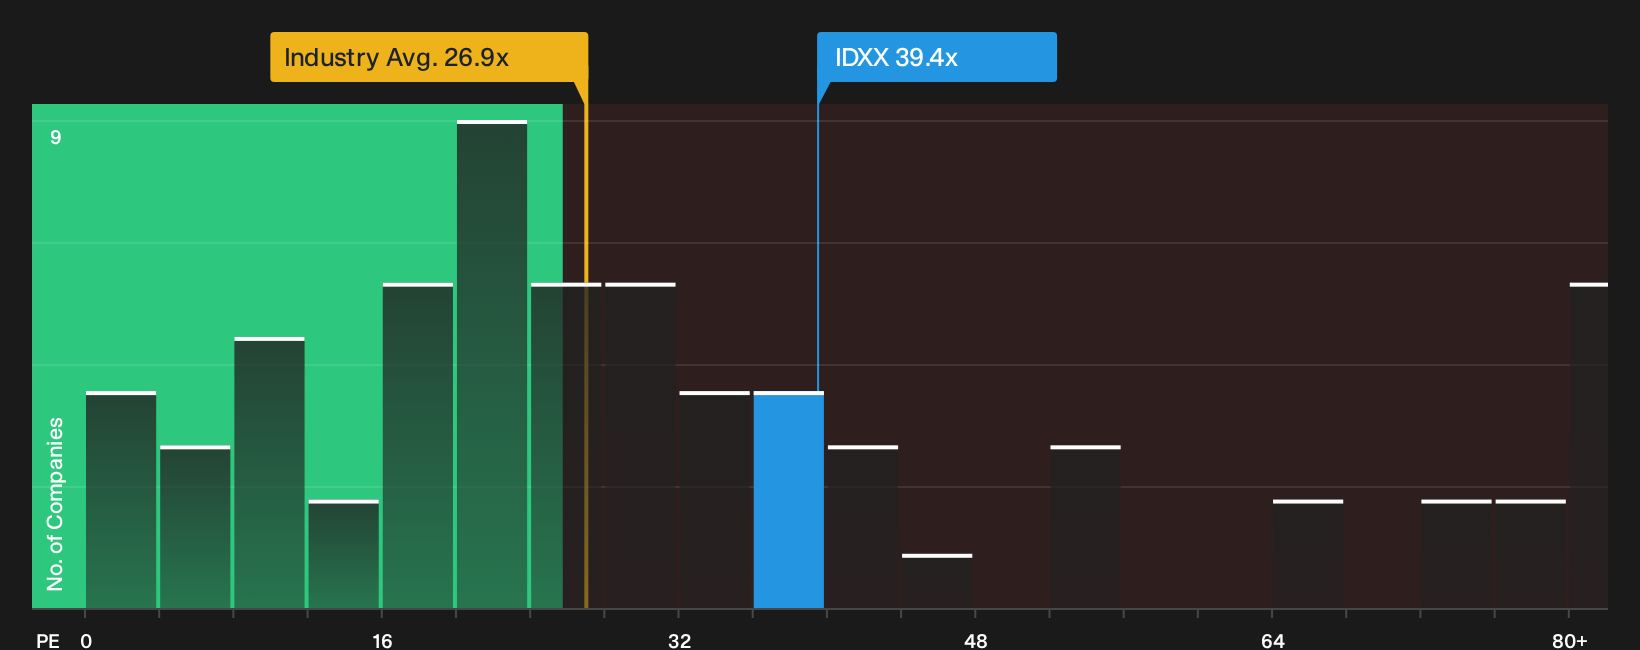
The first narrative leans on a fair value of $701.33, yet the current P/E of 39.4x tells a different story. That multiple sits above the US Medical Equipment industry at 26.9x and peers at 31.4x, and it is well ahead of the 28.9x fair ratio our work points to. The gap signals that, on earnings alone, buyers today are paying up and taking valuation risk if sentiment cools.
To see how those earnings based signals compare with the rest of the valuation work, and whether the current premium still looks reasonable as assumptions shift, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on IDEXX Laboratories so far, with valuation questions on one side and recurring diagnostics potential on the other, mean the next step is yours. Act while the data and market mood are fresh and weigh up the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond IDEXX Laboratories?
If IDEXX Laboratories has sharpened your focus on quality, do not stop here. Broaden your watchlist now and give yourself more options when conditions change.
- Target higher-quality value opportunities by scanning a curated set of 29 high quality undervalued stocks that combine robust fundamentals with prices that may not fully reflect them yet.
- Strengthen the income side of your portfolio by reviewing 5 dividend fortresses that aim for yield backed by resilient business models and consistent cash generation.
- Dial down potential shocks in your holdings by focusing on 30 resilient stocks with low risk scores that score well on balance sheet strength and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com