


EN
Earnings Beat Could Be A Game Changer For Alliance Resource Partners Stock (ARLP)
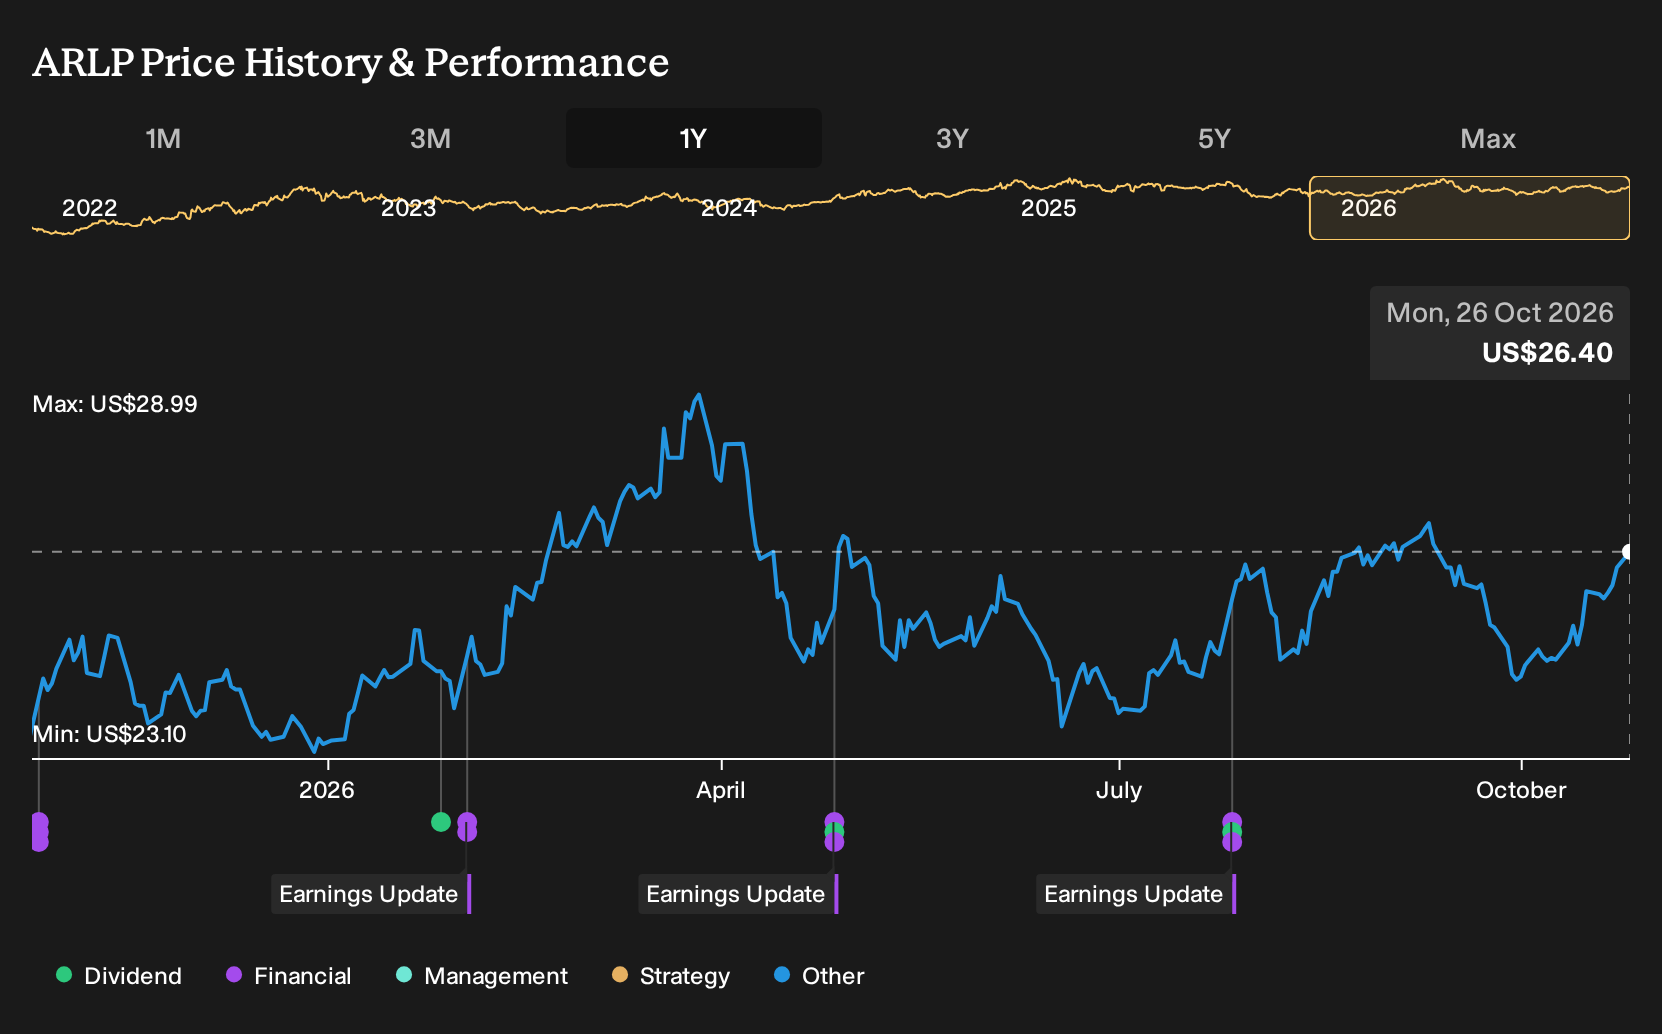
- Alliance Resource Partners reported third quarter 2026 revenue of US$603.02 million and net income of US$139.6 million, with basic and diluted earnings per unit of US$1.08 from continuing operations.
- Although nine-month net income and per unit earnings remained broadly flat year on year, higher third quarter profits, together with a US$0.60 cash distribution and updated 2026 guidance, highlight the partnership’s focus on cash generation from both coal and oil and gas royalties.
- The key question now is how Alliance Resource Partners' investment narrative may be influenced by stronger quarterly earnings and continued cash distributions.
Alliance Resource Partners Investment Narrative Recap
To own Alliance Resource Partners, an investor needs to believe that a dual engine of coal production and oil and gas royalties can keep throwing off cash even as coal pricing normalizes. The latest quarter supports that idea in the near term, with higher quarterly revenue and net income plus flat nine month earnings per unit suggesting operations are holding up through that transition.
The near term catalyst still sits in execution on contracted coal volumes and the royalty growth story tied to prior minerals investments. The biggest risk remains pressure on realized coal pricing and any further mine level disruptions or impairments. The Bitcoin holdings and distribution coverage also stay on the risk radar, but the new results do not radically change that balance.
The most relevant fresh data point is the third quarter 2026 report itself. Revenue of US$603.02 million and net income of US$139.6 million, alongside US$1.08 in basic and diluted earnings per unit from continuing operations, show how Alliance Resource Partners is converting a full quarter of Hamilton and the AllDale III and IV acquisition into the income statement.
Those figures link directly to the key catalysts investors are watching. Record royalty revenue and volumes support the thesis that over US$1b already put into minerals interests can keep lifting the royalty mix. At the same time, tightened 2026 coal volume and pricing guidance, backed by strong contracting, sharpens the focus on whether unit costs and pricing can offset the risks from lower priced index linked coal contracts and any future mine adjustments.
What The Current Forecasts Assume For Alliance Resource Partners
Alliance Resource Partners' narrative links directly to a set of explicit analyst assumptions about where the business could be by 2029 and what that might mean for income focused investors. These forecasts help you frame whether the recent third quarter 2026 cash generation lines up with the longer term expectations currently embedded in the consensus models.
Analysts are working off a view that revenue climbs at about 3.7% a year over the next three years as the mix of coal operations and oil and gas royalties shifts. They also see profit margins moving from 12.1% today to 16.5% in three years, which implies more of each dollar of sales dropping through to the bottom line if those assumptions hold.
On earnings, the current consensus points to US$263.7 million in profit today and US$401.5 million by 2029, with earnings per unit of about US$3.08 on that later number. That is an increase of roughly US$138 million in annual earnings between now and the 2029 estimate year, so the models are baking in a meaningfully larger profit pool even before any discussion of distributions or buybacks.
Those same forecasts plug into a revenue line of about US$2.4b in 2029 and use them to infer what multiple the stock would need to trade on for the analyst price target to hold. The implied P/E on the 2029 consensus earnings is 12.4x compared with around 12.0x today and a current industry P/E for US Oil and Gas of 12.3x, which keeps the valuation debate anchored in relatively modest changes rather than extreme multiple expansion.
Alliance Resource Partners' narrative projects US$2.4b revenue and US$401.5 million earnings by 2029. This assumes 3.7% yearly revenue growth and an earnings increase of about US$138 million from US$263.7 million today.
Uncover why Alliance Resource Partners' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value views from the Simply Wall St Community are wide, with 2 retail investors landing anywhere between roughly US$31 and US$117 per unit for Alliance Resource Partners. That spread reflects real business crosscurrents. On one side are coal pricing pressure and Bitcoin mark to market swings. On the other side are expanding royalties and firm coal contracting. Investor opinions can differ sharply, so treat these estimates as starting points and explore several alternative viewpoints before deciding how this income story fits your portfolio.
Explore another Alliance Resource Partners fair value estimate, including one that suggests it could be worth just $31.17.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent research and judgment.
- A great starting point for your Alliance Resource Partners research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alliance Resource Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alliance Resource Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alliance Resource Partners?
If you want to put Alliance Resource Partners in context, compare it with a broader set of income and quality focused opportunities using the Simply Wall St Screener. These tools help you test different angles, from higher yield to sturdier balance sheets, without having to build filters from scratch.
- Target resilient income first, then assess price and quality by running your own screen built around 5 dividend fortresses that prioritise payout strength and balance sheet support.
- Hunt for mispriced quality where fundamentals matter more than hype by scanning through a curated pool of 29 high quality undervalued stocks that blend robust cash flows with disciplined financial profiles.
- Start with financial strength and work backward to your watchlist by filtering for a list of solid balance sheet and fundamentals (24 results) that can help anchor a more defensive corner of your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com