


EN
Progyny (PGNY) Could Be 18% Undervalued On New Menopause Outcomes Data
Progyny (PGNY) is back in focus after publishing new clinical outcomes data on its Menopause and Midlife program, with the study reporting symptom improvements for more than 70% of participating members.
Progyny shares closed at US$28.13, with the 1 month share price return up 10.57% even as the 3 month share price return declined 8.55%. That mix of near term momentum against a weaker recent patch sits beside a 1 year total shareholder return of 44.03%, but a 5 year total shareholder return that is down 54.63%, suggesting that recent enthusiasm around the business, including its menopause outcomes data, is occurring after a much tougher longer stretch.
Scan Progyny’s menopause results against a wider set of women’s health opportunities by reviewing the hand picked 34 healthcare AI stocks now benefiting from connected care and data driven models.
Progyny’s recent rebound and solid 1 year return raise a simple issue: Is the menopause momentum and connected care story mostly reflected in the US$28 share price, or is the valuation still giving investors room to move?
Most Popular Narrative: 18% Undervalued
Progyny’s most followed thesis pegs fair value at about $34.42 per share, comfortably above the recent $28.13 close. This frames the menopause data as one piece of a broader cash flow and platform story.
The main thing that has to go right is that Progyny converts its ongoing platform and product investments, including newer women's and family health offerings and health plan partnerships, into sustained adoption that supports its roughly 17% adjusted EBITDA margin profile while addressing concerns about growth and scale.
See why 27 investors see Progyny as 18% undervalued.
Result: Fair Value of $34.42 (UNDERVALUED)
Still, two pressure points hang over the Progyny story: employer benefit cost cutting that slows fertility and women’s health uptake, and softer treatment volumes that weigh on margins.
Find out about the key risks to this Progyny narrative.
Another View: What Progyny’s P/E Is Telling You
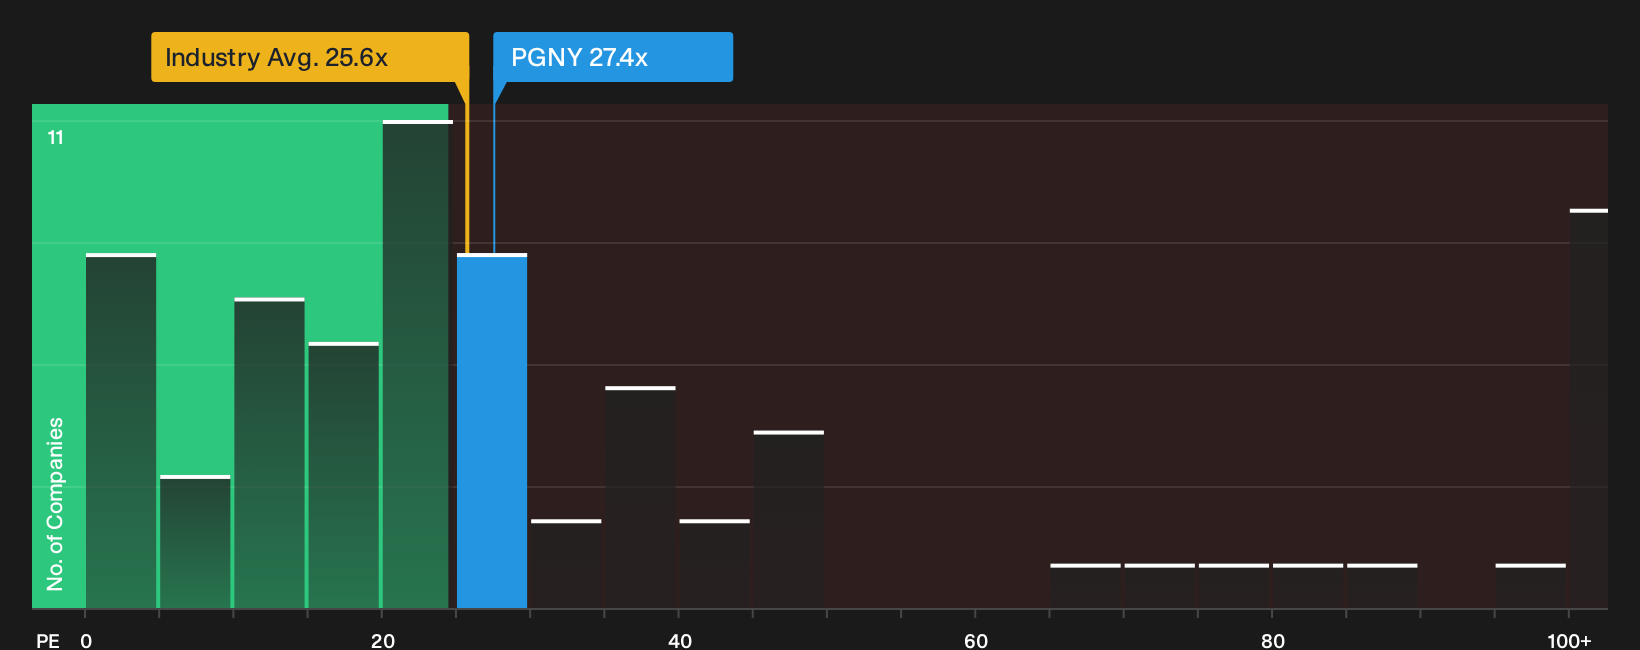
The early takeaway is that Progyny looks cheap against a US$34.42 fair value, yet the P/E story is less forgiving. At 27.4x earnings, the stock trades above the US Healthcare industry on 25.7x and only slightly richer than its own fair ratio of 27.1x. That narrow gap hints at limited margin for error if growth or margins underwhelm, so the question becomes whether you see that premium as comfort or constraint.
For a closer look at how this price compares with peers and the market, and how that might shape your risk tolerance, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Progyny story feels finely balanced between promise and pressure, move quickly on the homework and make the call using the 4 key rewards.
Looking for more Progyny sized investment ideas?
Do not stop at Progyny. Use the Simply Wall Street Screener to spot other opportunities that fit your risk, return, and quality checklist before the crowd catches on.
- Target potential mispricing by scanning a curated pool of companies that score well on quality and valuation signals through the 29 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with cleaner balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by checking the 21 high quality undiscovered gems that pair robust financials with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com