


EN
How Fourth Quarter Earnings Guidance Will Impact United Community Banks Stock
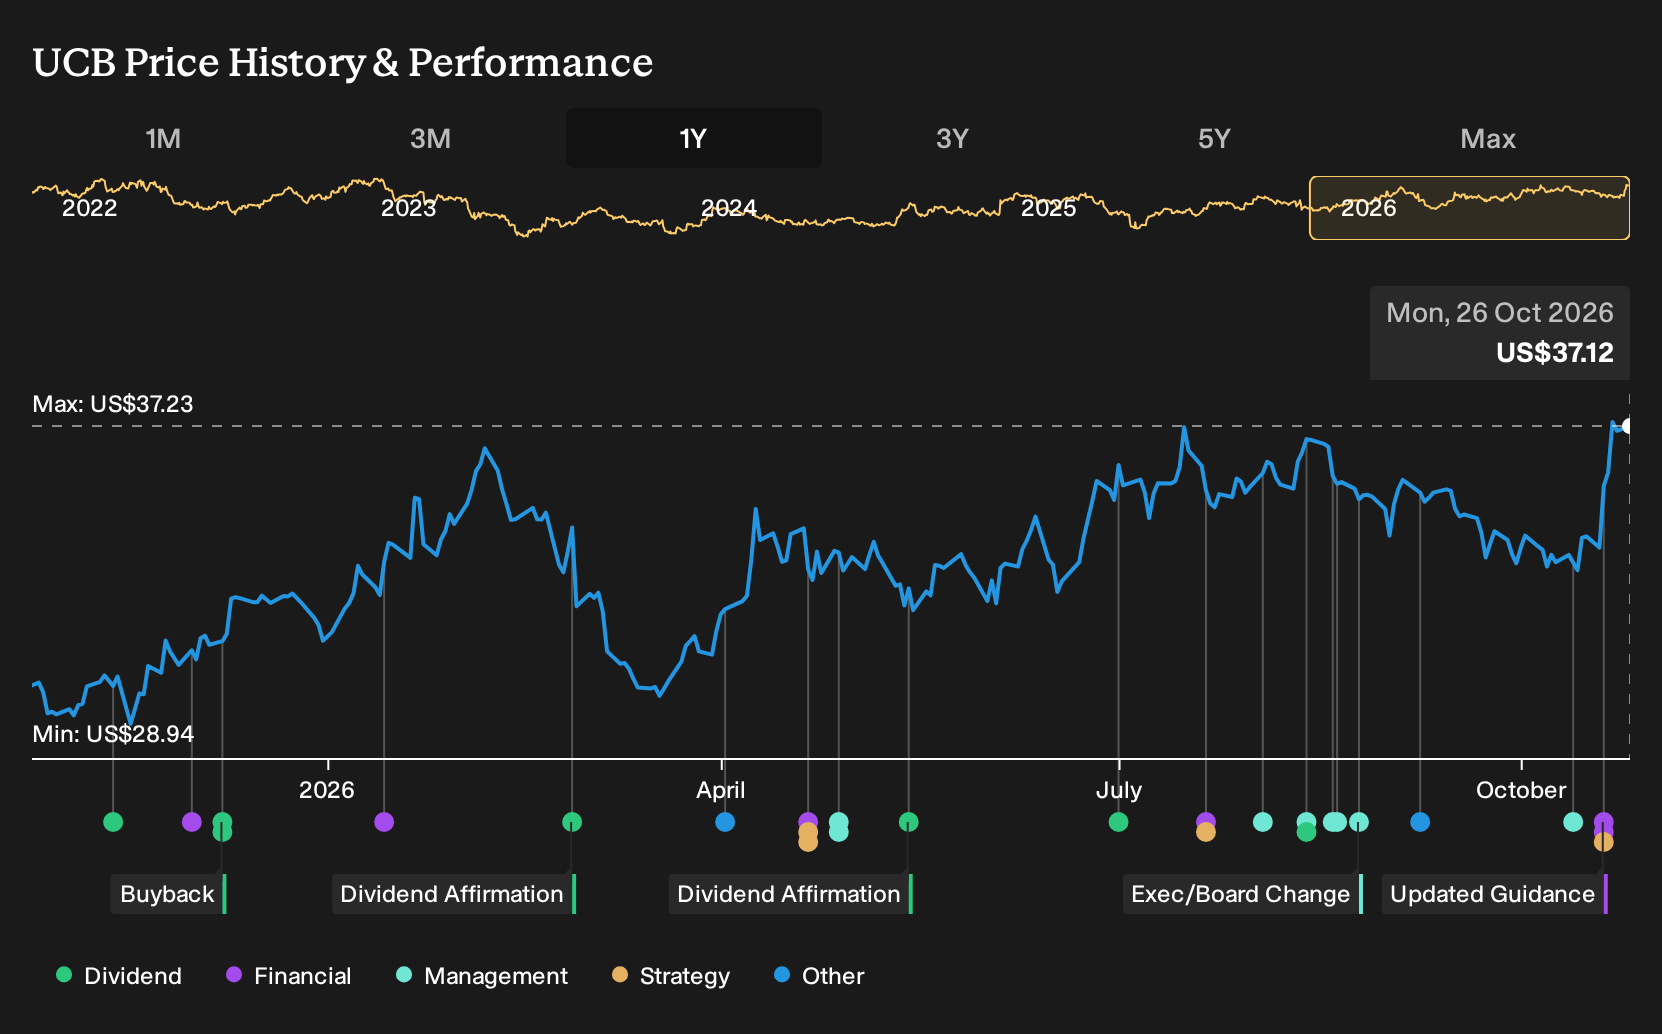
- United Community Banks reported third quarter 2026 results with higher net interest income but a shift to a net loss, alongside reduced net charge offs, updated buyback activity, and new fourth quarter earnings guidance of US$0.80 to US$0.83 per share.
- The bank is pairing earnings guidance and capital returns with an expanded international banking and foreign exchange team, signaling a push to support U.S. clients with more complex cross border trade and payment needs.
- We will look at how United Community Banks' fourth quarter earnings guidance reshapes its investment narrative after these mixed quarterly results.
United Community Banks Investment Narrative Recap
To stay invested in United Community Banks, you need to be comfortable with a simple trade off. The bank is leaning on higher net interest income and pre provision net revenue to carry it through a period where reported earnings have been hit, including a third quarter net loss of US$139.75 million and weaker margins than a year ago.
The near term catalyst now hangs on whether fourth quarter earnings per share actually land in the guided US$0.80 to US$0.83 range. That would help rebuild confidence after recent shortfalls. The biggest risk is that rising deposit costs and any further guidance reset keep compressing returns on equity that are already described as low.
The most relevant fresh data point is that fourth quarter 2026 earnings per share guide. Management is pointing to US$0.80 to US$0.83, supported by solid pre provision net revenue. For you, the key question is whether that level feels sustainable once the securities portfolio reshuffle, higher funding costs, and Peach State integration all flow through.
Hitting that range would show United Community Banks translating its stronger balance sheet and loan producer build out into cleaner, recurring profitability after the third quarter loss. Missing it, especially after two prior shortfalls versus expectations, would keep execution risk front and center and could make investors focus more on margin pressure than on growth catalysts.
United Community Banks' narrative projects US$1.2b revenue and US$468.1 million earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about US$97.4 million from US$370.7 million today.
Uncover how United Community Banks' fair value indicates an 8% potential upside to its current price before investors close that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$40 to US$58 per share, which already shows how far opinions on United Community Banks can stretch. Those views pre date the latest net loss, securities portfolio hit, and EPS guidance, so use them as a starting point. Then weigh deposit cost risk, the securities reset, and Peach State integration to test your own narrative.
Explore another United Community Banks fair value estimate, including one that suggests it could be worth just $40.17.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Community Banks research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Community Banks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Community Banks' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Community Banks?
If United Community Banks has sharpened your focus on earnings resilience, funding costs, and capital returns, it can help to line those themes up against a wider watchlist. The Simply Wall St Screener lets you scan other companies through the same lens, so you can compare balance sheet strength, cash generation, and income potential side by side.
- For investors who care about capital preservation first and returns second, start with a curated set of resilient businesses through the 30 resilient stocks with low risk scores.
- If value is your priority and you want solid fundamentals at a sensible price, filter for opportunities using the 29 high quality undervalued stocks.
- For readers building a portfolio with income as a core goal, focus on dependable payout profiles using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com